
Did Strong Earnings Expectations Just Shift Southwest Gas Holdings (SWX) Investment Narrative?
- Southwest Gas Holdings is set to report quarterly results for the period ended September 2026, with analysts expecting higher year over year earnings supported by stronger revenue.
- The key angle for investors is how any earnings surprise might reflect underlying drivers such as rate case progress, customer growth and capital deployment rather than short term sentiment.
- We now look at how Southwest Gas Holdings' investment narrative could be affected by the anticipated earnings strength hinted at in this update.
Scan other potential beneficiaries of similar rate, customer and capital trends by reviewing our hand picked list of solid balance sheet and fundamentals (24 results) alongside Southwest Gas Holdings ahead of earnings season.
Southwest Gas Holdings Investment Narrative Recap
For a shareholder in Southwest Gas Holdings, the core belief is simple. The utility can keep turning population growth in Arizona and Nevada, plus a US$6.3b capital program, into a larger regulated rate base and steadier earnings over time. The upcoming quarterly results might show whether earnings are tracking this plan, but the report itself is just one data point.
The key short term focus is continued constructive decisions on Arizona and Nevada rate mechanisms and cost recovery, because that is what converts heavy spending into allowed returns. The biggest current risk is execution on the US$2.3b Great Basin 2028 Expansion Project, where permitting delays or higher costs could affect that earnings story.
The most relevant context for this earnings update is management’s enlarged capital agenda, anchored by Great Basin’s planned US$2.3b build out and the broader US$6.3b utility investment pipeline. Quarterly numbers will sit against this backdrop, because investors are watching whether current profitability supports that construction schedule and related funding needs.
Customer growth of about 1% over the past 12 months and cost discipline, including operations and maintenance expense that management aims to hold roughly flat per customer, frame how Southwest Gas Holdings can handle that spending. Any commentary around timing, contracting and regulatory treatment for Great Basin, and tools such as Nevada’s SB 417 alternative ratemaking, will likely matter more than a single quarter’s earnings beat or miss.
What The Current Forecasts Assume For Southwest Gas Holdings
Southwest Gas Holdings' current analyst narrative points to revenues of US$2.3b and earnings of US$470.7m by 2029, built on assumed yearly revenue growth of 10.5% and an earnings step up of about US$186m from US$284.3m today.
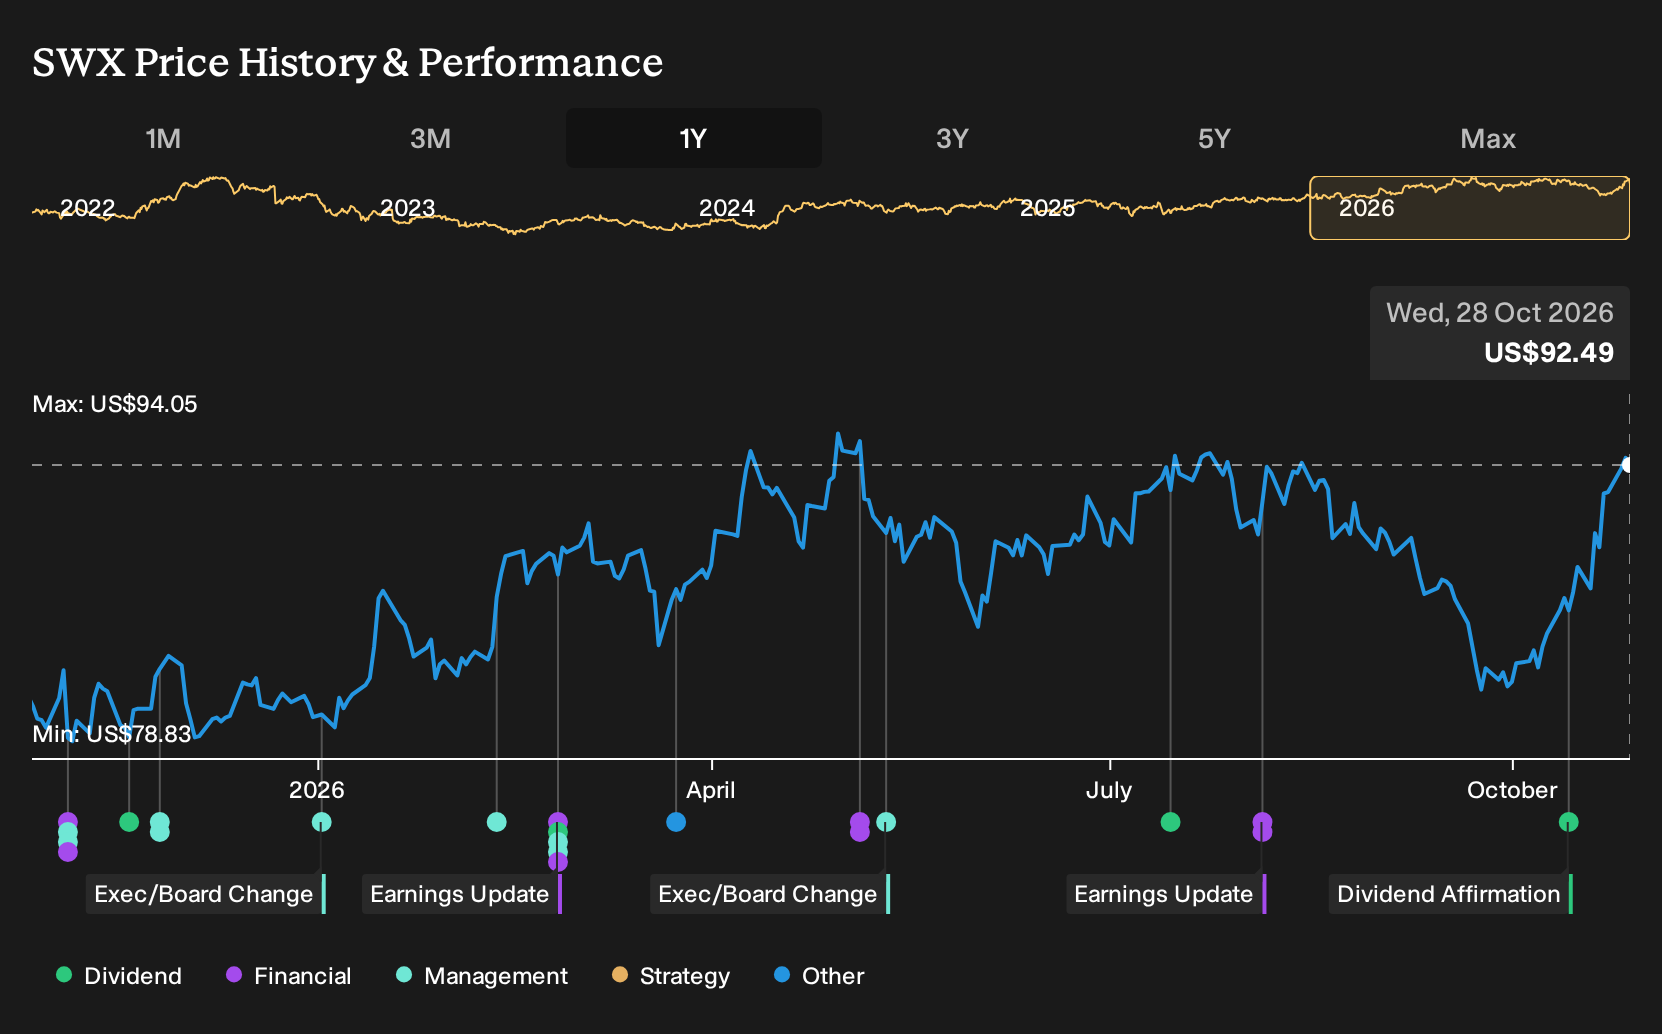
Uncover why Southwest Gas Holdings' fair value indicates a 9% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$32 to just over US$100 per share, so opinions on Southwest Gas Holdings spread widely. Consider that dispersion alongside risks around decarbonization, regulatory decisions and Great Basin execution, and then actively compare these contrasting views before anchoring your own expectations.
Explore 2 other Southwest Gas Holdings fair value estimates, including one that suggests as much as 65% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Southwest Gas Holdings research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Southwest Gas Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Southwest Gas Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Southwest Gas Holdings?
If Southwest Gas Holdings has your attention, use this earnings moment as a springboard to refresh your wider watchlist. You can compare the utility's profile with other companies that have different return drivers, income profiles and risk levels by using targeted screeners on Simply Wall St.
- For investors who care most about financial resilience, start with a list of solid balance sheet and fundamentals (24 results) and see which businesses pair healthy balance sheets with fundamental strength.
- If value is your priority, scan a 26 high quality undervalued stocks that filters for companies where quality metrics and current pricing may not fully match up.
- For income focused portfolios, review a 6 dividend fortresses that highlights stocks offering 5%+ yields with an emphasis on stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com