
European Stock Picks That Could Be Trading Below Estimated Value
The European stock market has recently faced challenges, with the pan-European STOXX Europe 600 Index experiencing a decline amid soaring oil prices, Middle East tensions, and heightened inflationary pressures. Despite these hurdles, investors are on the lookout for opportunities in undervalued stocks that may offer potential value amidst current market conditions. Identifying such stocks involves assessing their intrinsic value compared to current trading prices, especially during times of economic uncertainty.
Top 10 Undervalued Stocks Based On Cash Flows In Europe
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Valmet Oyj (HLSE:VALMT) | €28.88 | €57.55 | 49.8% |
| Stille (OM:STIL) | SEK250.00 | SEK470.13 | 46.8% |
| PORR (WBAG:POS) | €31.65 | €62.46 | 49.3% |
| Peab (OM:PEAB B) | SEK96.05 | SEK180.16 | 46.7% |
| Koninklijke BAM Groep (ENXTAM:BAMNB) | €12.14 | €23.33 | 48% |
| Grupa Pracuj (WSE:GPP) | PLN55.00 | PLN108.78 | 49.4% |
| Goodtech (OB:GOD) | NOK15.25 | NOK28.50 | 46.5% |
| DWS Group GmbH KGaA (XTRA:DWS) | €65.45 | €126.72 | 48.3% |
| Boliden (OM:BOL) | SEK499.00 | SEK943.12 | 47.1% |
| Apator (WSE:APT) | PLN25.50 | PLN50.18 | 49.2% |
Here we highlight a subset of our preferred stocks from the screener.
Airbus (ENXTPA:AIR)
Overview: Airbus SE, along with its subsidiaries, is involved in the design, manufacture, and delivery of aeronautics and aerospace products, services, and solutions globally with a market cap of €151.90 billion.
Operations: The company generates revenue through its segments, including Airbus Helicopters (€8.96 billion), Airbus Defence and Space (€13.91 billion), and the main Airbus division, which encompasses holding functions and bank activities (€55.63 billion).
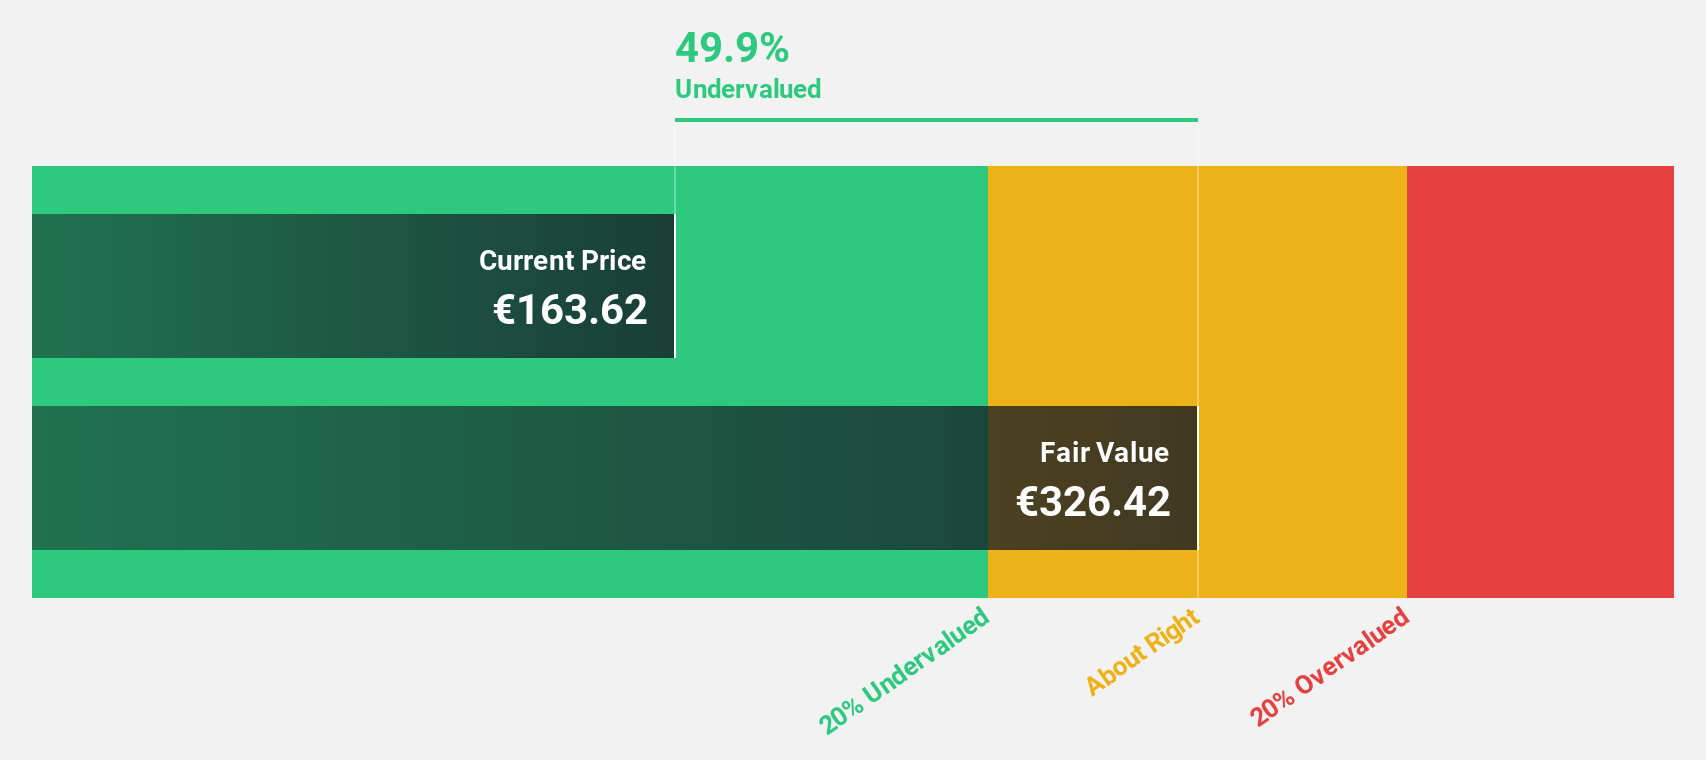
Estimated Discount To Fair Value: 36.8%
Airbus is trading at €191.92, significantly below its estimated future cash flow value of €303.57, indicating it may be undervalued based on cash flows. The company's earnings are forecast to grow 14.68% annually, outpacing the French market's 12.2%. Recent orders for A320neo and A330neo aircraft from major clients like Aviation Capital Group and Avolon strengthen Airbus's long-term revenue prospects, supporting its attractive valuation relative to peers and industry standards.
- Insights from our recent growth report point to a promising forecast for Airbus' business outlook.
- Take a closer look at Airbus' balance sheet health here in our report.
AddLife (OM:ALIF B)
Overview: AddLife AB (publ) operates through its subsidiaries to supply instruments, equipment, consumables, and reagents mainly to sectors such as medical care, research, educational institutions, and the food and pharmaceutical industries with a market cap of approximately SEK22.23 billion.
Operations: The company's revenue segments consist of SEK4.10 billion from Labtech and SEK6.61 billion from Medtech.
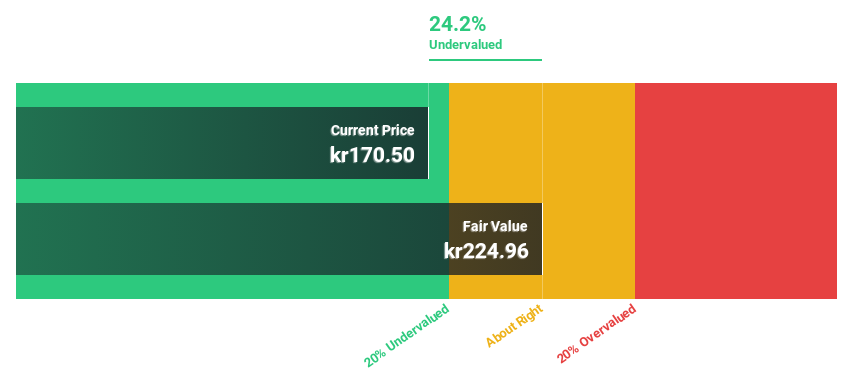
Estimated Discount To Fair Value: 23.5%
AddLife is trading at SEK 182.4, below its estimated future cash flow value of SEK 238.34, highlighting potential undervaluation based on cash flows. The company's earnings grew by a substantial 63.5% over the past year and are forecast to grow annually at 14%, surpassing the Swedish market's growth rate of 7.2%. Despite high debt levels, AddLife's revenue growth is expected to outpace the negative trend in the Swedish market, enhancing its relative value appeal.
- According our earnings growth report, there's an indication that AddLife might be ready to expand.
- Dive into the specifics of AddLife here with our thorough financial health report.
Palfinger (WBAG:PAL)
Overview: Palfinger AG, along with its subsidiaries, offers hydraulic lifting solutions in Austria and internationally, with a market cap of approximately €1.04 billion.
Operations: Revenue Segments (in millions of €): The company generates revenue through its core segments, including Loader Cranes (€1,200.50), Timber and Recycling Cranes (€350.75), Marine Systems (€450.30), and Railway Systems (€200.25).
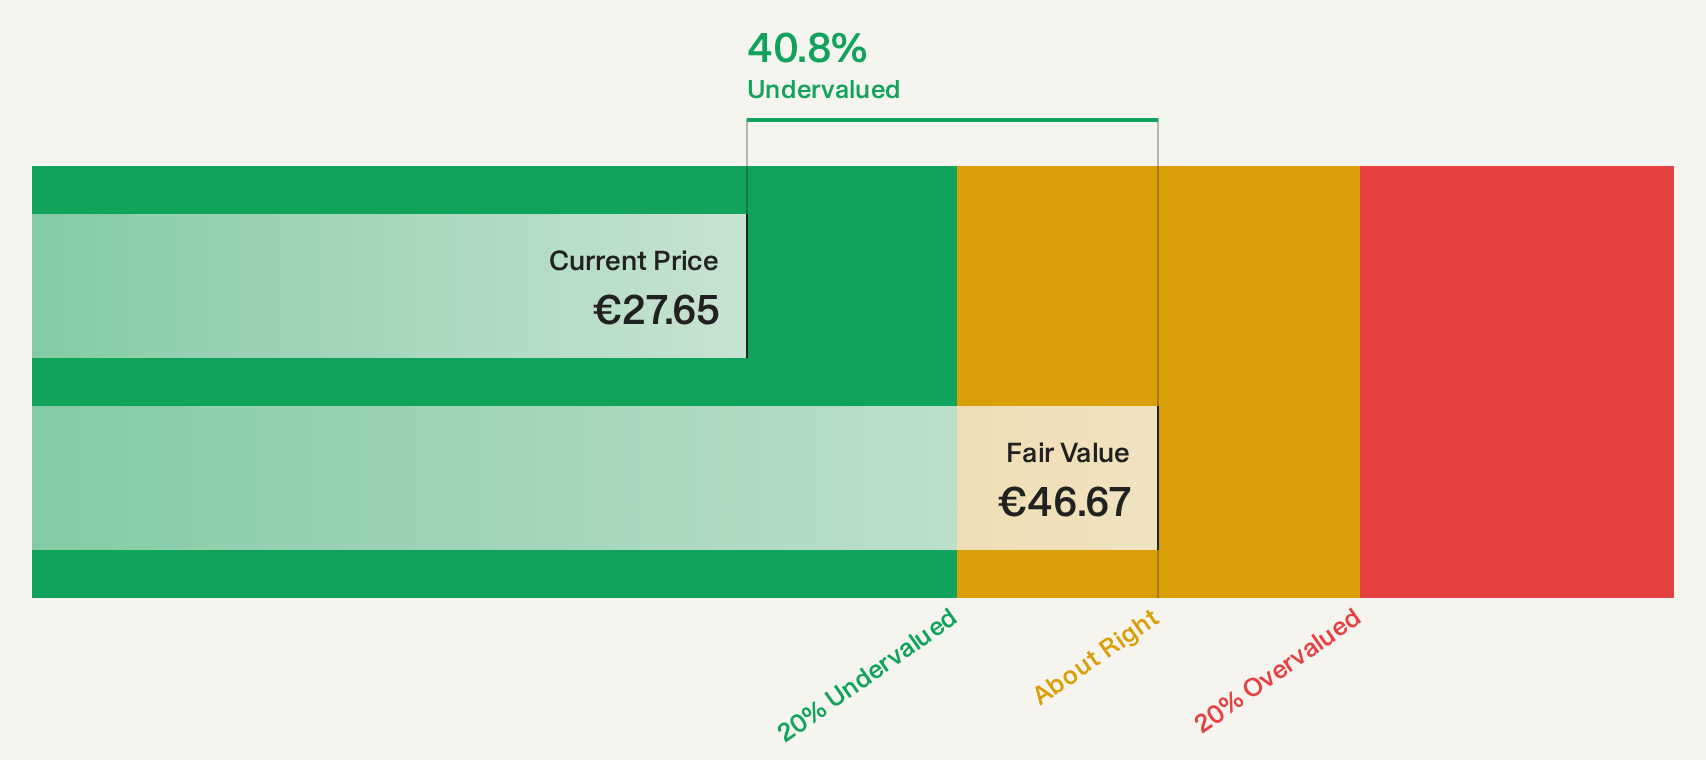
Estimated Discount To Fair Value: 38.8%
Palfinger is trading at €27.7, significantly below its estimated future cash flow value of €45.23, suggesting undervaluation based on cash flows. Despite a recent net loss of €61.55 million due to write-downs in Russia, earnings are forecast to grow annually by 25.7%, outpacing the Austrian market's growth rate of 9%. However, revenue growth is expected to lag behind the market slightly at 4.1% per year, and high debt levels remain a concern.
- The analysis detailed in our Palfinger growth report hints at robust future financial performance.
- Navigate through the intricacies of Palfinger with our comprehensive financial health report here.
Where To Now?
- Click through to start exploring the rest of the 63 Undervalued European Stocks Based On Cash Flows now.
- Have a stake in these businesses? Integrate your holdings into Simply Wall St's portfolio for notifications and detailed stock reports.
- Simply Wall St is a revolutionary app designed for long-term stock investors, it's free and covers every market in the world.
Want To Explore Some Alternatives?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com