
Gjensidige Forsikring (OB:GJF) Q3 Earnings Strength Keeps Undervalued Narrative In Play
Gjensidige Forsikring (OB:GJF) just posted third quarter figures that caught investor attention, with net income of NOK 2,076.7 million and basic earnings per share of NOK 4.08 from continuing operations.
Despite the stronger third quarter, Gjensidige Forsikring’s share price has drifted lower, with a 90 day share price return down 8.1% and a year to date share price return down 13.7%, while the 3 year total shareholder return of 79.6% still highlights a solid longer term history.
Compare Gjensidige Forsikring’s latest earnings momentum with a hand picked 228 resilient stocks with low risk scores that have kept returns steadier while markets have swung around them.
Earnings are moving in one direction, while Gjensidige Forsikring’s share price has slipped in the other. Is this a strong insurer that is temporarily marked down, or is the current valuation already fair?
Most Popular Narrative: 9% Undervalued
On the most followed view of Gjensidige Forsikring, a fair value of NOK 286.22 sits above the last close at NOK 260.40. This puts the recent share price weakness against a valuation that still screens as supportive when set beside the company’s earnings profile.
The current valuation implies the market is discounting the sustainability of recent underwriting profitability, capital strength and customer dividend practices, leaving the share price below what this narrative views as fair for Gjensidige Forsikring.
See why 17 investors see Gjensidige Forsikring as 9% undervalued.
Result: Fair Value of NOK286.22 (UNDERVALUED)
Still, the Danish workers compensation ruling and the pension segment’s Q1 2026 loss of NOK 298 million could yet unsettle the bullish Gjensidige Forsikring narrative.
Find out about the key risks to this Gjensidige Forsikring narrative.
Another View: Gjensidige Forsikring Looks Expensive On Earnings
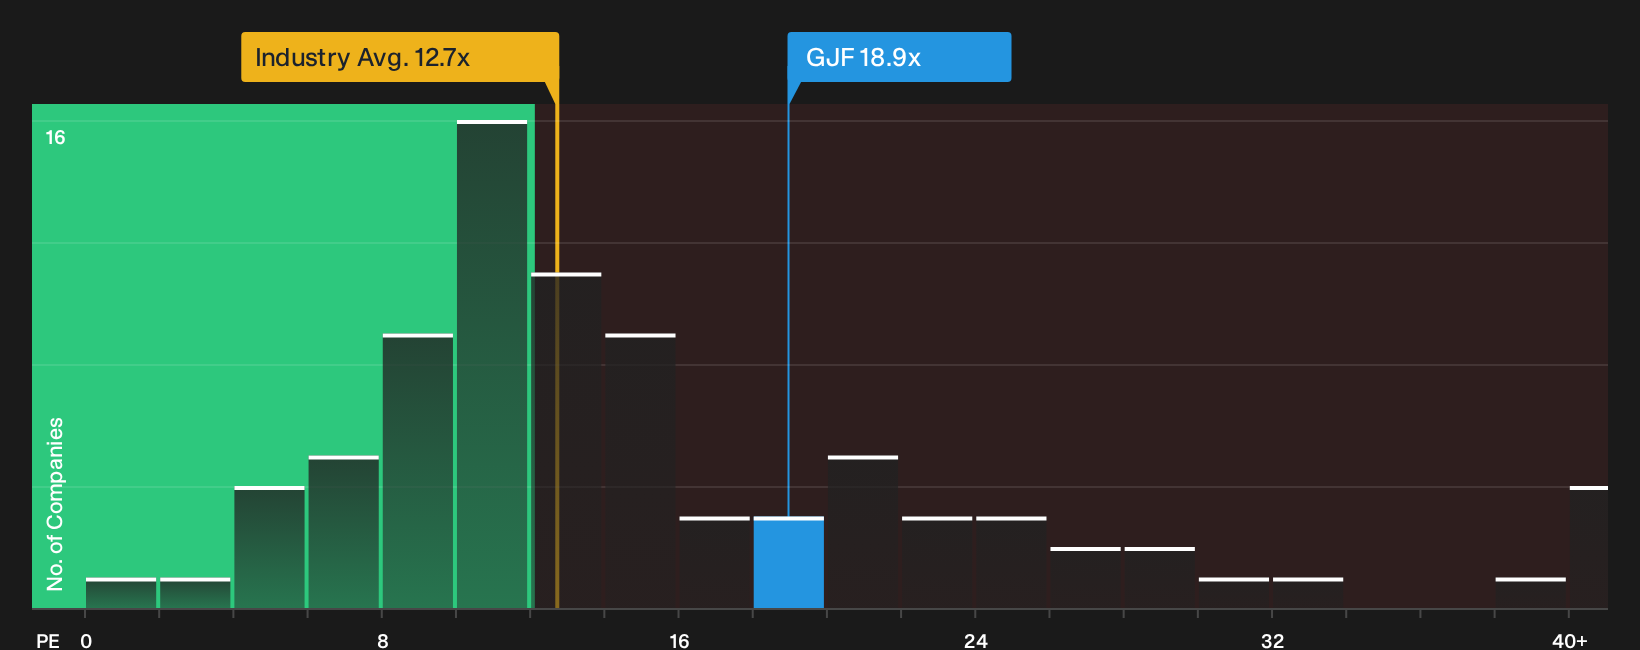
The popular narrative points to Gjensidige Forsikring as undervalued against a fair value of NOK 286.22, yet the current P/E of 18.9x tells a different story. The insurer trades richer than the European insurance industry on 12.6x and its peer average of 13.4x, and is also slightly above its own fair ratio of 18.7x. That kind of premium can signal quality, or it can leave less room for error if expectations slip. Which side do you think it is on?
To see how this richer earnings multiple compares with a cash flow based view, review how the SWS DCF model treats Gjensidige Forsikring in detail, including the assumptions behind that higher cash flow value, in See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages now, or a clear setup forming for Gjensidige Forsikring in your view? Weigh the downside and upside, then move fast to frame your own stance with 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Gjensidige Forsikring?
If Gjensidige Forsikring has sharpened your focus on risk, reward and valuation, do not stop here. Broaden your watchlist with a few targeted shortcuts.
- Target potential mispricing by scanning a 191 high quality undervalued stocks that filters for quality businesses still trading at what could be bargain valuations.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (203 results) that highlights companies with sturdier finances when conditions become more challenging.
- Get ahead of the crowd by tracking a 609 high quality undiscovered gems that surfaces underfollowed stocks with fundamentals that may deserve a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com