
Did Rising Charge Offs Just Shift Western Alliance's (WAL) Investment Narrative?
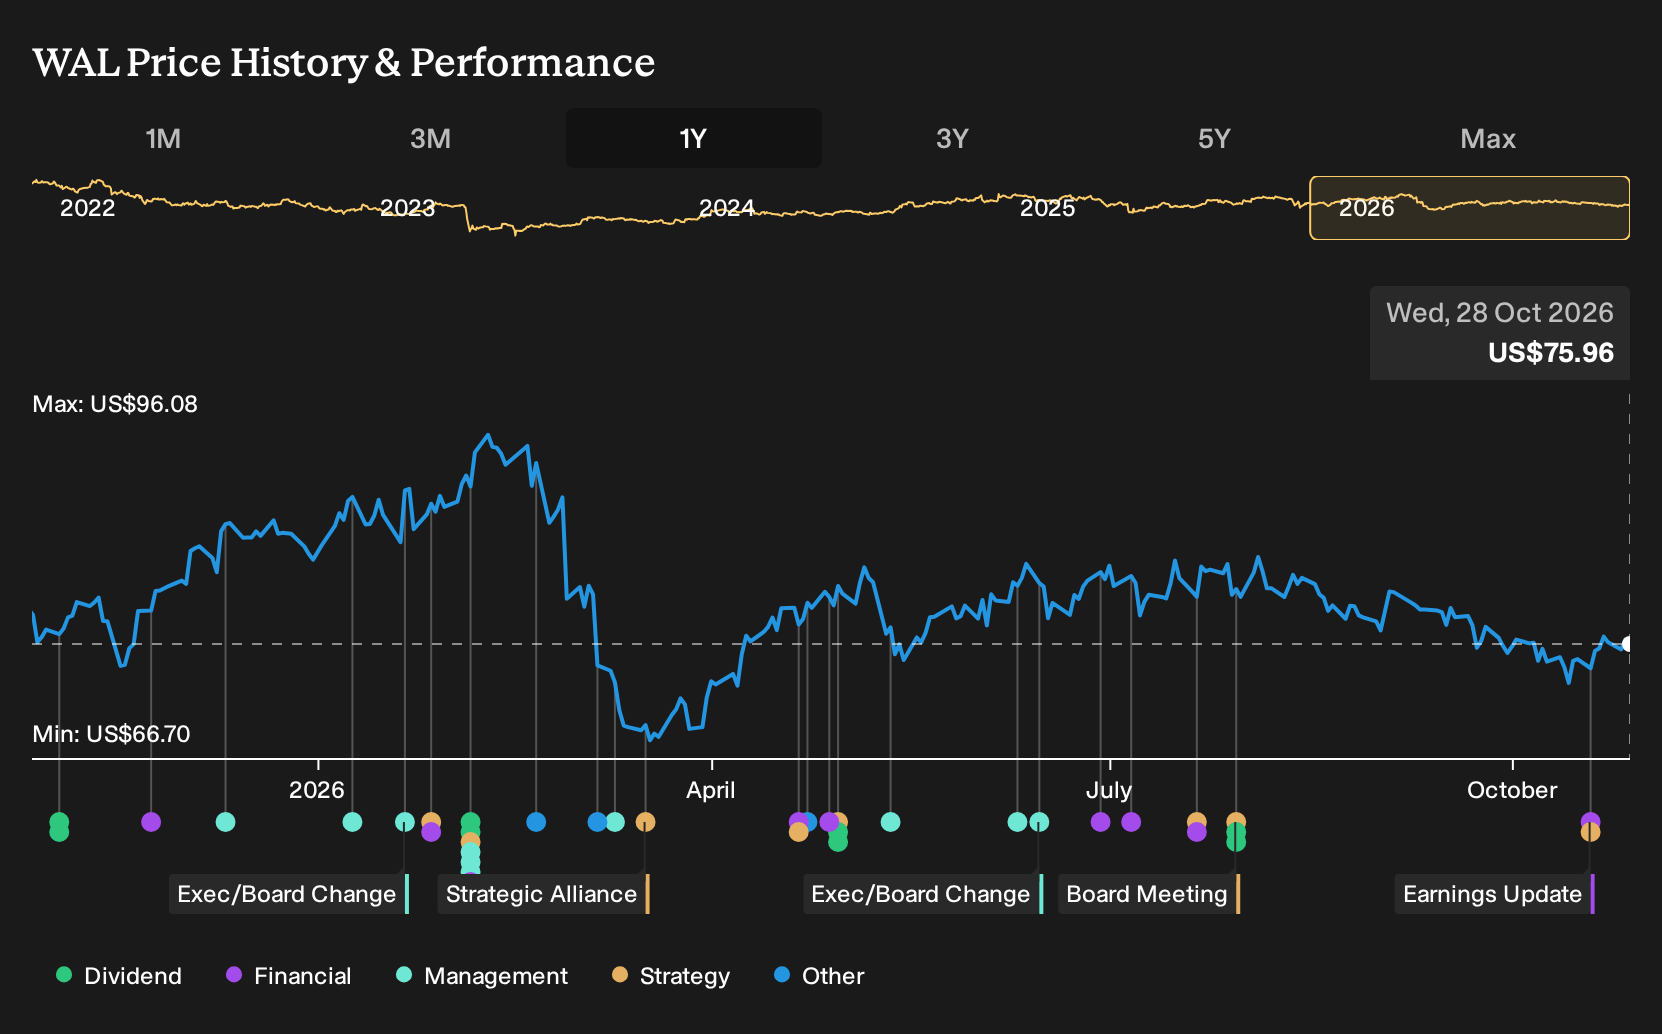
- Western Alliance Bancorporation reported third quarter 2026 results, with net interest income of US$807.6 million, net income of US$270.1 million, and net loan charge offs of US$45.8 million compared with US$31.1 million in the same period a year earlier.
- The mix of higher profitability and rising credit losses gives investors a clearer view of how Western Alliance Bancorporation is balancing earnings against emerging loan quality pressure.
- This article examines how Western Alliance Bancorporation's higher net loan charge offs might reshape the investment narrative investors have been relying on.
Western Alliance Bancorporation Investment Narrative Recap
For you to stay interested in Western Alliance Bancorporation, you need to be comfortable with a story built on higher net interest income and tighter balance sheet management, while accepting bumpier credit costs. The latest quarter fits that pattern. Earnings power looked solid with US$807.6 million of net interest income and US$270.1 million of net income.
The short term swing factor now is whether credit losses settle down or keep edging higher after net loan charge offs reached US$45.8 million. The main risk is that this pressure combines with rising operating expenses, which could keep net margins under strain even if deposit mix and funding costs continue to improve.
The clearest recent data point for this debate is the third quarter earnings release. Western Alliance Bancorporation showed higher net interest income and net income compared with a year earlier, while diluted EPS from continuing operations moved to US$2.45. You can see the core banking engine still producing earnings despite the credit drag.
That same update also framed the trade off you are weighing as a shareholder. Management is pushing balance sheet optimization, deposit remixing and loan book reshaping, yet credit costs and a relatively low allowance for bad loans remain a watch item. How cleanly the bank executes on this mix will shape how the current valuation gap closes, if at all.
Western Alliance Bancorporation's narrative projects US$4.8b revenue and US$1.4b earnings by 2029. This aligns with analysts' assumption of 10.2% yearly revenue growth and implies an earnings increase of about US$413m from US$987.2m today.
Uncover why Western Alliance Bancorporation's fair value indicates an 18% potential upside to its current price, which could narrow quickly as sentiment catches up.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$89.9 to US$178.8 per share, which shows how far Western Alliance Bancorporation opinions can spread before fresh news hits the models. Rising net loan charge offs and higher operating costs provide reasons to test these community views against alternative scenarios.
Explore 2 other Western Alliance Bancorporation fair value estimates, including one that suggests it could be worth just $89.93.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Western Alliance Bancorporation research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Western Alliance Bancorporation. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Western Alliance Bancorporation's overall financial health at a glance.
Looking for more Western Alliance Bancorporation investment ideas?
If Western Alliance Bancorporation has put regional banks back on your radar, it can help to compare this story with other businesses that have different balance sheet profiles, income patterns and risk levels. The Simply Wall St Screener gives you a fast way to line up alternatives that match the kind of trade off you want between resilience, value and income.
- For investors who want potential mispricing with quality fundamentals, scan a curated set of 19 high quality undiscovered gems that might not yet be heavily followed by the market.
- If capital preservation sits higher on your list, focus on businesses that score well on financial strength by reviewing a 32 resilient stocks with low risk scores that filters for sturdier balance sheets and lower risk profiles.
- Income oriented investors can zero in on cash return potential by reviewing a 6 dividend fortresses that concentrates on stronger yield and payout characteristics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com