
Should Earnings Beat Require Action From Hawkins (HWKN) Investors?
- Hawkins reported second quarter fiscal 2027 results with sales of US$313.82 million and net income of US$27.78 million, alongside ongoing dividends and buybacks. The water treatment segment expanded through the Dave Symonds & Associates and Eagle Labs acquisitions completed before October 28, 2026.
- The combination of record adjusted EBITDA, higher earnings per share from continuing operations, and a long dividend track record since 1985 shows how Hawkins is using stronger cash generation to both grow its water treatment footprint and return capital to shareholders.
- We will now look at how Hawkins’ investment narrative is shaped by record adjusted EBITDA alongside expansion in its water treatment operations.
Scan beyond Hawkins and see how other hand-picked water treatment and infrastructure plays stack up on cash generation and balance sheet strength in our list of solid balance sheet and fundamentals (24 results).
What Is Hawkins' Investment Narrative?
The big picture with Hawkins is simple. You are tying your capital to a chemicals operator that leans heavily into water treatment, food and health ingredients, and industrial solutions, and is trying to turn consistent cash generation into both expansion and payouts. The latest quarter fits that story. Higher sales, record adjusted EBITDA and steady dividends, plus buybacks, suggest the business is converting demand into cash and recycling it into acquisitions like Dave Symonds & Associates and Eagle Labs, which extend the water treatment footprint.
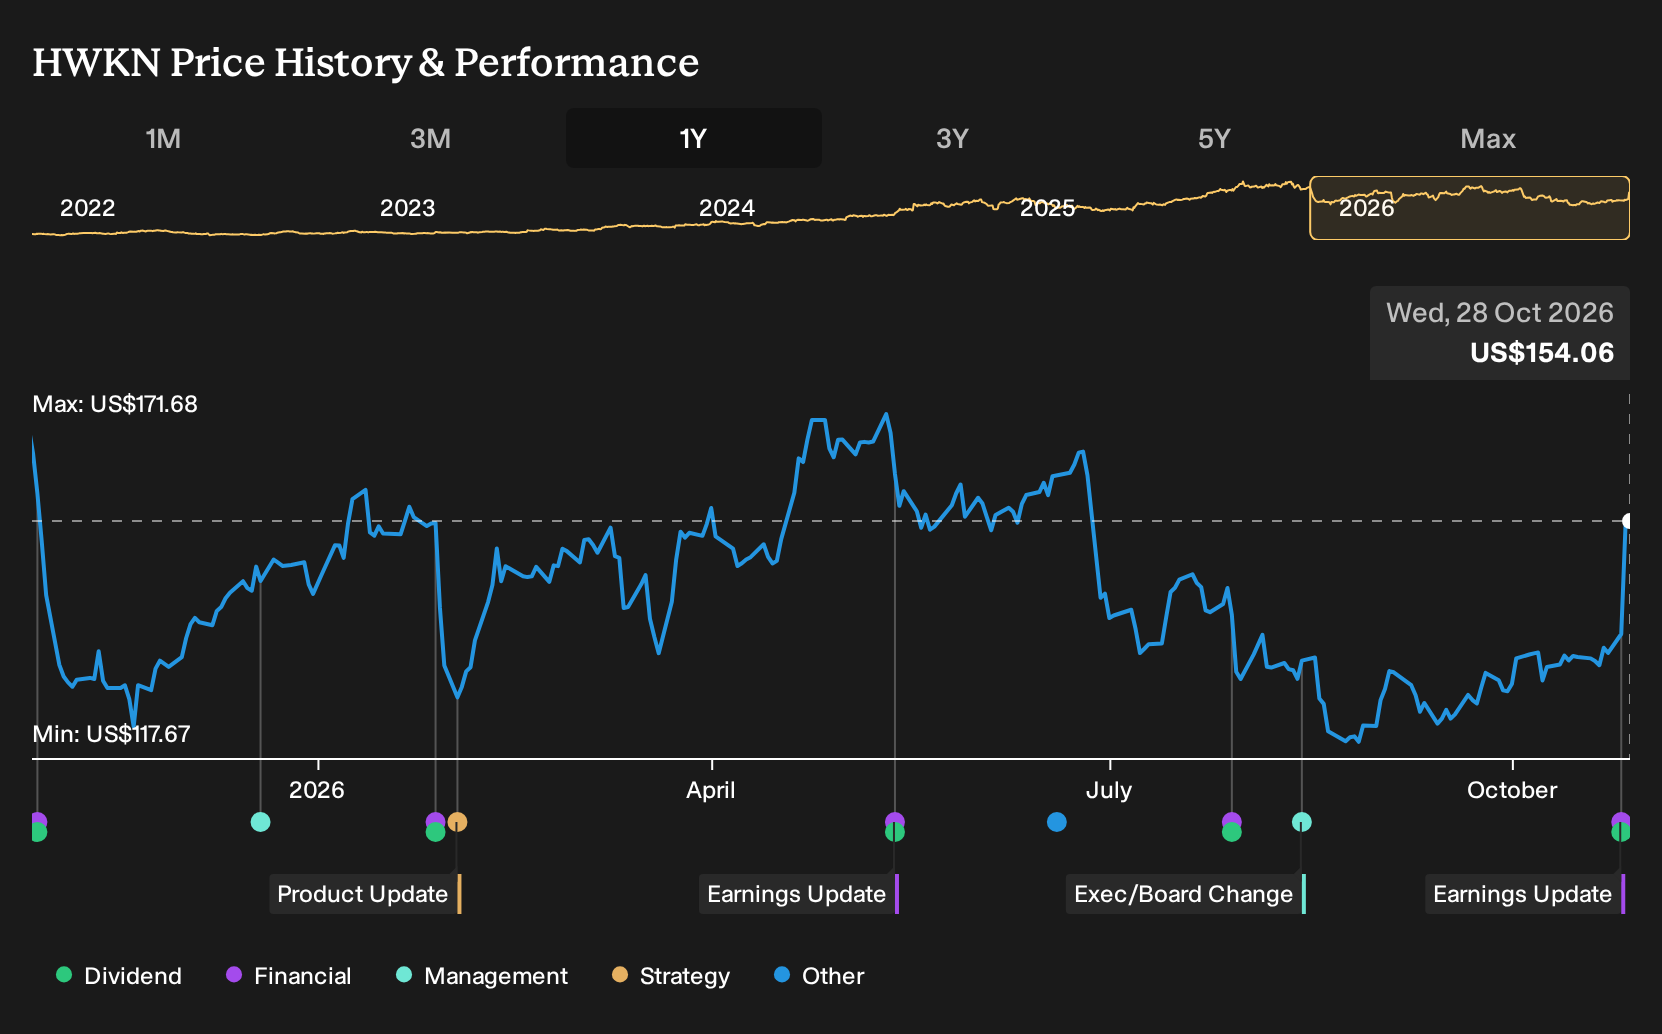
In the short term, the key levers remain execution on recent deals, pricing discipline on core chemicals, and the capital intensity of keeping plants, tanks and logistics running efficiently. The strong quarter and 8% share price move hint that a lot of this positive news may already be reflected in the current valuation, especially with Hawkins trading on a 37.3x P/E while DCF work points to the stock close to estimated fair value. Earnings growth forecasts in the low double digits help the story, yet the slightly softer recent profit growth and P/E premium underline that the margin for error on operations is not wide.
Even so, there is a specific operational pressure point in Hawkins' model that could matter far more than the latest beat if...
There's only one way to know the right time to buy, sell or hold Hawkins. Head to Simply Wall St's company report for the latest analysis of Hawkins's Fair Value.
Exploring Other Perspectives
The Simply Wall St Community currently contributes 2 fair value estimates for Hawkins, ranging from about US$158.53 to US$174 per share. Those views predate the October 26 earnings beat, dividend affirmation, and water treatment acquisitions, so you are seeing opinions that may not yet reflect the latest shift in Hawkins' scale and cash generation profile.
Explore another Hawkins fair value estimate, including one that suggests as much as 13% upside from the current price.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Hawkins research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Hawkins. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hawkins' overall financial health at a glance.
Looking For More Investment Ideas Beyond Hawkins?
If Hawkins has sharpened your thinking about cash generation, payouts and balance sheet strength, you can use that same lens across the wider market with a few targeted screeners on Simply Wall St.
- For investors who want potential mispricings with solid fundamentals behind them, start with a curated set of 19 high quality undiscovered gems that may not yet be widely followed.
- If capital preservation matters as much as upside for you, focus on a basket of 32 resilient stocks with low risk scores that score well on resilience and financial stability.
- Income focused investors can zero in on companies built around regular payouts by scanning a list of 6 dividend fortresses with yields that may fit a long term portfolio.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com