
Could Shanghai Henlius Biotech (SEHK:2696) Be 76% Below Fair Value After ASTRIDE Data?
Shanghai Henlius Biotech (SEHK:2696) moved back into focus after reporting positive ASTRIDE data, where serplulimab plus chemotherapy showed numerically longer overall survival and similar safety to atezolizumab in U.S. extensive-stage small cell lung cancer.
Investors have treated the ASTRIDE update as a fresh catalyst for Shanghai Henlius Biotech, yet the HK$50.6 share price still reflects a year to date share price return that is down 13.65%, while the 3 year total shareholder return of 277.61% points to powerful longer term momentum.
Scan beyond Shanghai Henlius Biotech and see how other oncology focused players with potential catalysts are lining up in our curated 130 healthcare AI stocks today.
The share price reaction to ASTRIDE looks modest compared with Shanghai Henlius Biotech’s multiyear gains, which leaves a simple tension for investors: Is most of the big move already behind it, or not yet priced in?
Preferred P/E of 27x for Shanghai Henlius Biotech: Is it justified?
On simple earnings maths, Shanghai Henlius Biotech trades on a P/E of 27x, which is rich against both its own fair P/E estimate of 20.7x, and the last close at HK$50.6 does not change that conclusion.
P/E compares the current share price to earnings per share and is often used for profitable biopharma groups, where cash flows are tied closely to the product portfolio and pipeline progress.
For Shanghai Henlius Biotech, a 27x P/E suggests investors are paying a premium for each unit of earnings, even though earnings are forecast to grow 12.8% per year and revenue is projected at 6% per year, which is slower than the broader Hong Kong market revenue forecast of 8.6% per year.
The market is applying a far higher P/E than the Hong Kong Biotechs industry average of 12.3x and above the peer group at 20.5x. This signals a strong valuation premium that could compress if sentiment cools or the market leans closer to the estimated fair P/E of 20.7x.
Explore the SWS fair ratio for Shanghai Henlius Biotech.
Result: Price-to-Earnings of 27x (OVERVALUED)
Still, the Shanghai Henlius Biotech story can be knocked off course if key pipeline trials underperform, or if high P/E expectations meet weaker earnings delivery.
Find out about the key risks to this Shanghai Henlius Biotech narrative.
Another view on Shanghai Henlius Biotech’s value
The same Shanghai Henlius Biotech that screens as expensive on a 27x P/E appears very different on our DCF work. At HK$50.6 the shares are trading at a 76.2% discount to an SWS DCF fair value estimate of HK$212.39, which puts the multiple-based view in a very different context.
Both lenses cannot be fully right at the same time, so the key question for you is which set of assumptions feels more realistic for how cash flows and sentiment might evolve from here.
Look into how the SWS DCF model arrives at its fair value.
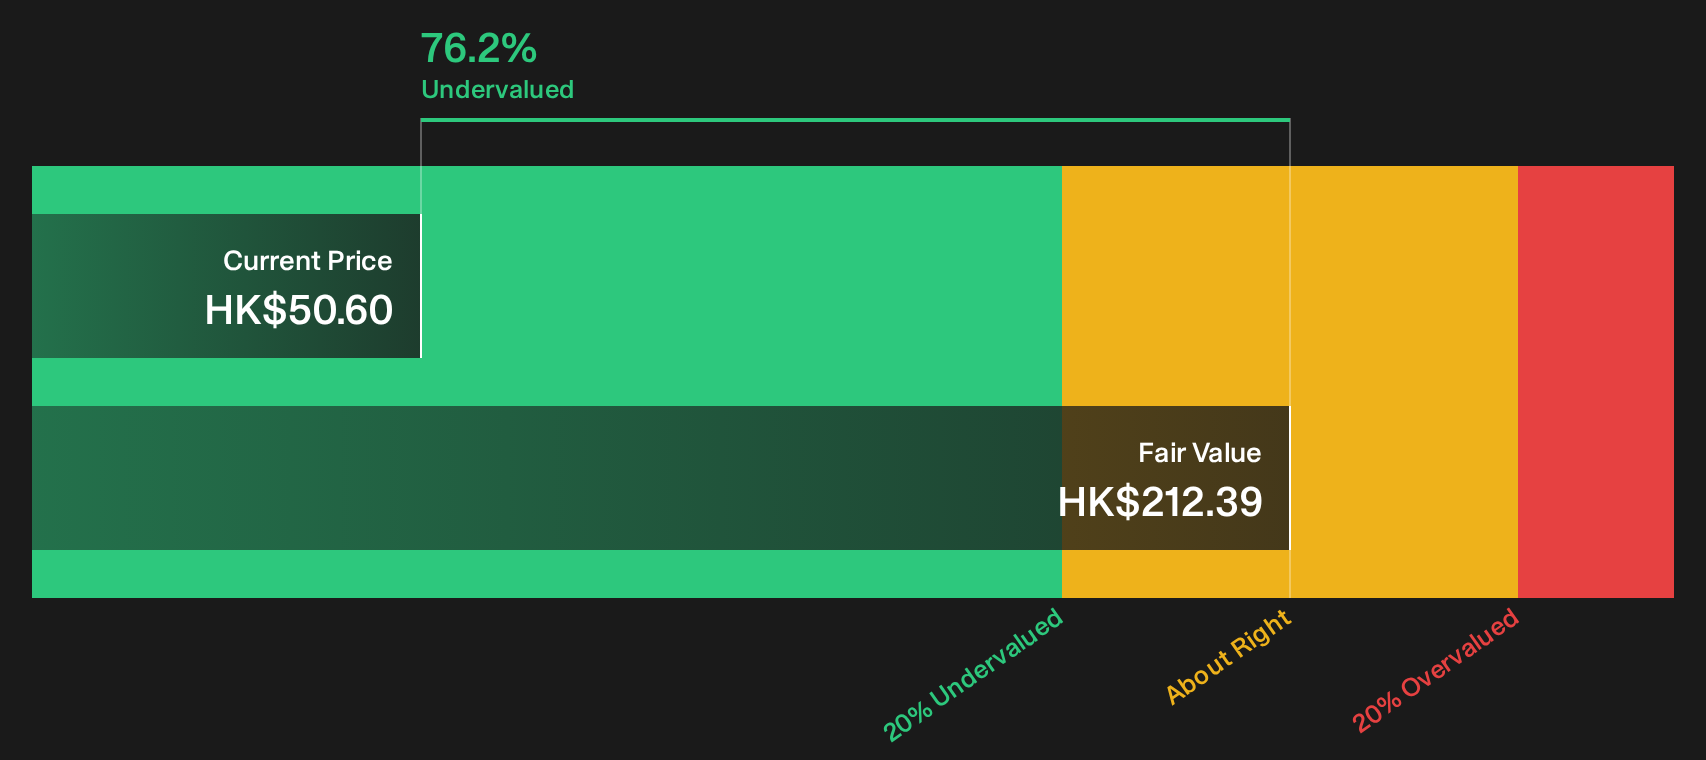
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Shanghai Henlius Biotech for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 191 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
The split view on Shanghai Henlius Biotech is clear enough. Now move fast, review the numbers yourself and decide where you land on the story by weighing the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Shanghai Henlius Biotech?
If Shanghai Henlius Biotech has sharpened your focus on opportunity and risk, do not stop here. Fresh ideas often sit where the market is not yet looking.
- Target potential mispricing by scanning a curated pool of companies that combine quality fundamentals with discounted valuations through the 191 high quality undervalued stocks.
- Build a steadier income stream by hunting for robust payers with higher yields using the 226 dividend fortresses.
- Prioritise resilience by filtering for businesses with cleaner balance sheets and stronger financial footing in the list of solid balance sheet and fundamentals (203 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com