
Raised Outlook Could Be A Game Changer For OBICLtd Stock (TSE:4684)
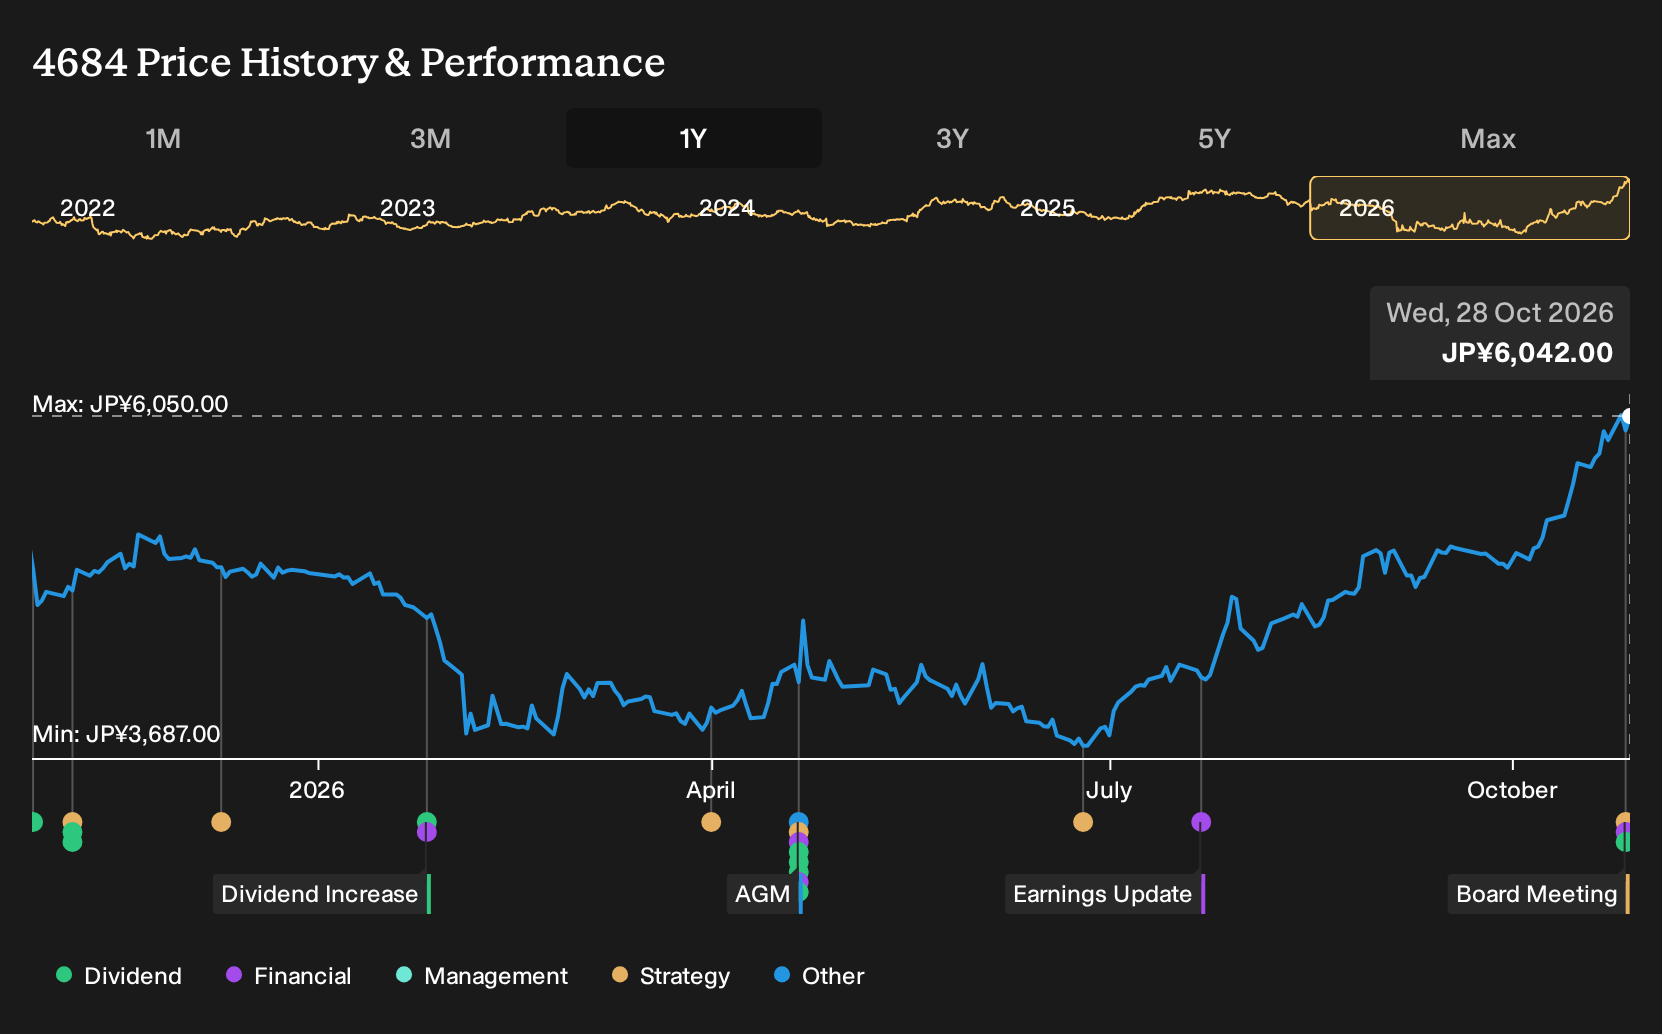
- OBIC Co., Ltd. held a board meeting on 27 October 2026 and announced upward revisions to its full-year earnings forecast and a higher year-end dividend projection for the fiscal year ending 31 March 2027. This includes a planned year-end cash dividend of JPY 53 per share.
- The group linked these forecast changes to stronger than expected business progress in the first half, with higher anticipated net sales, operating profit and profit attributable to owners of parent. It also reiterated a policy of stable and continuous shareholder returns supported by a solid financial base.
- We will look at how OBIC Co., Ltd.'s raised earnings outlook and higher dividend guidance may reshape the company’s broader investment narrative.
Scan how OBICLtd’s dividend revision compares with other income ideas by reviewing the handpicked 30 dividend fortresses in the market right now.
What Is OBICLtd's Investment Narrative?
To own OBICLtd, you need to believe in a fairly simple story. This is a software and systems integrator that lives or dies on execution, sticky ERP style solutions and the ability to keep Japanese enterprise clients renewing and expanding contracts. Recent guidance points to higher expected net sales, operating profit and earnings per share for the year ending March 2027. This ties the upgraded JPY 53 year-end dividend directly to operating progress rather than financial engineering.
In the short term, the raised outlook and dividend increase clarify two things. Management is leaning into a model that converts high net margins into cash distributions, and the business remains relatively light on capital intensity compared with hardware heavy peers. The flip side is that the share price has already risen over 1 month and 1 year. With a P/E of 33.2x on forecast EPS and a market cap above JPY 2.6b, expectations for OBICLtd are not low.
Even so, there is a less comfortable angle to this dividend and guidance upgrade story that sits in the background around ...
There's only one way to know the right time to buy, sell or hold OBICLtd. Head to Simply Wall St's company report for the latest analysis of OBICLtd's Fair Value.
Exploring Other Perspectives
Only two fair value estimates from the Simply Wall St Community currently span roughly JPY 4,643 to JPY 5,680 per share, which already shows how far opinions on OBICLtd can stretch. Those views predate the earnings and dividend guidance upgrades, so treat them as a starting point and compare several fresh opinions before drawing conclusions.
Explore another OBICLtd fair value estimate, including one that suggests it could be worth as much as ¥5680.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your OBICLtd research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for OBICLtd. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate OBICLtd's overall financial health at a glance.
Looking For More Investment Ideas Beyond OBICLtd?
If OBICLtd's updated guidance has you rethinking where fresh opportunities might sit in your portfolio, it can help to scan a broader field of companies with different strengths and risk profiles.
- For investors who want income but still care about balance sheet strength, check out a curated 30 dividend fortresses that pair yield with more resilient financial profiles.
- If value is your priority and you prefer stocks where quality and pricing both matter, review a focused 14 high quality undervalued stocks that match stronger fundamentals with more modest valuations.
- When capital preservation and smoother ride matter more than chasing every rally, consider a handpicked 24 resilient stocks with low risk scores that aim to keep overall risk scores in check.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com