
Earnings Preview: What to Expect From Cisco’s Report
Headquartered in San Jose, California, Cisco Systems, Inc. (CSCO) has built a global business around networking, cybersecurity and communications, keeping businesses connected in an increasingly digital world.
With a market cap of nearly $431.8 billion, the company offers network infrastructure, cloud and wireless technologies, data center solutions, collaboration tools, security software, technical support, and managed services, giving it a broad foothold across the technology landscape.
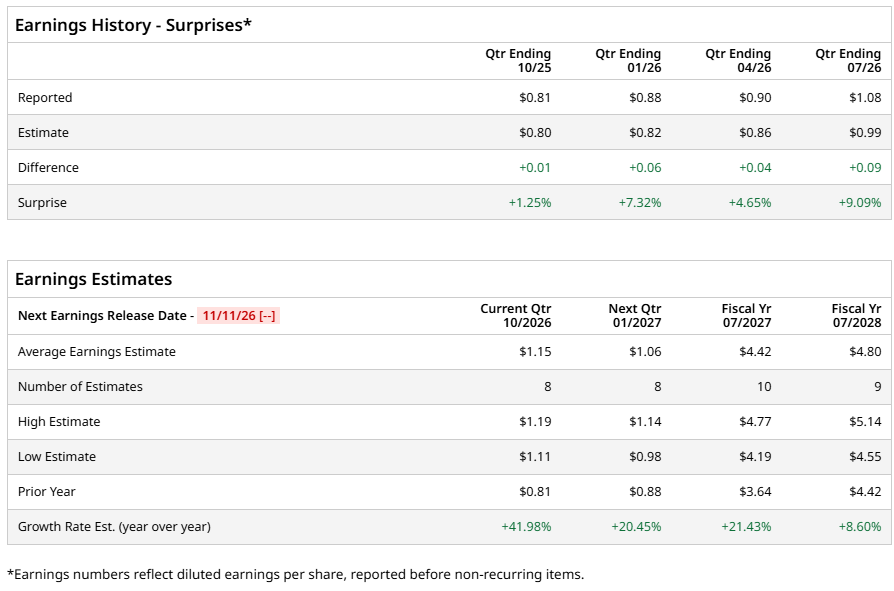
The extensive reach sets the stage for Cisco’s upcoming Q1 FY2027 earnings report, with Wall Street expecting diluted EPS of $1.15, a 42% increase from the year-ago quarter. Cisco has also beaten EPS estimates in each of the past four quarters, setting a strong precedent ahead of its latest results.
The earnings outlook beyond the current quarter looks equally encouraging, with analysts projecting diluted EPS of $4.42 for full-year FY2027, representing year-over-year (YOY) growth of 21.4%. Analysts also expect the bottom line to reach $8.6 for FY2027, marking a 4.8% increase from the previous year.
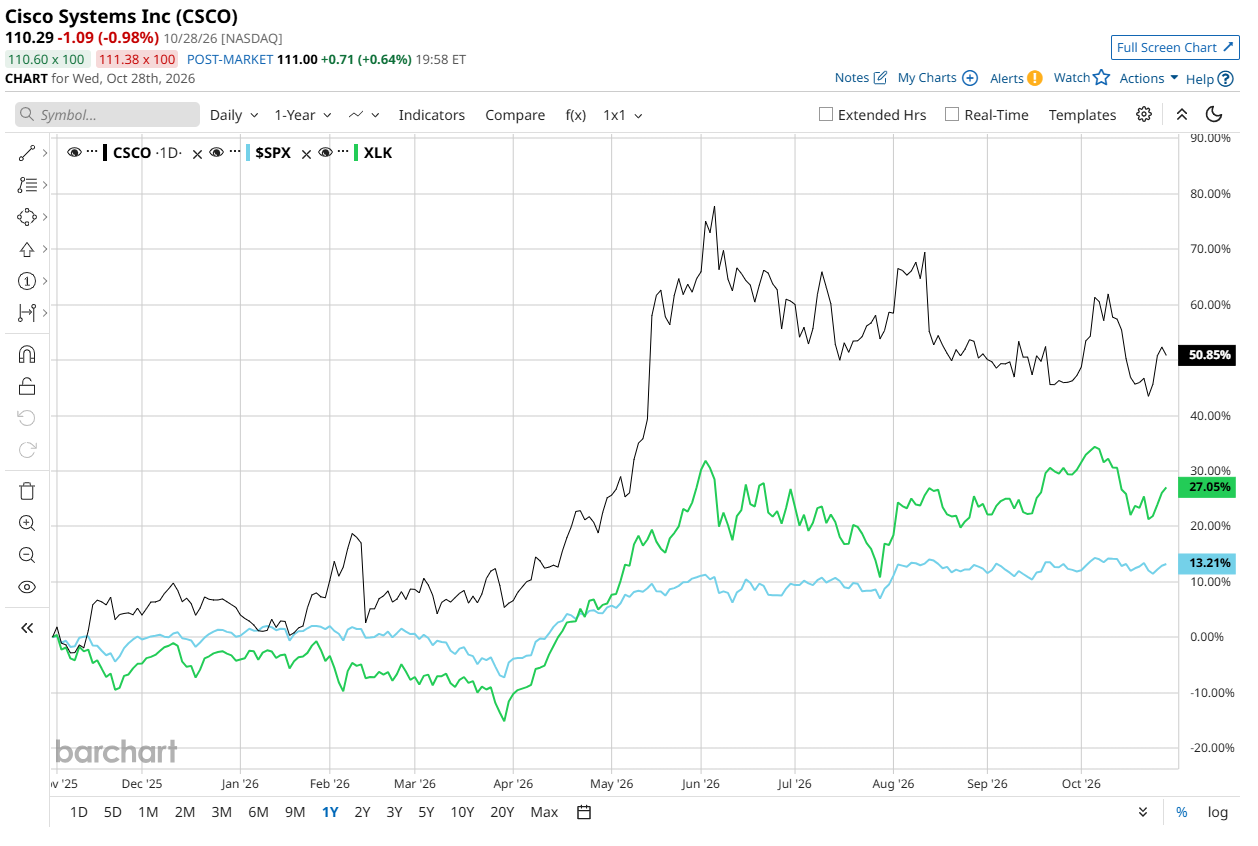
The market has already taken notice, sending CSCO stock up 51.9% over the past 52 weeks, far ahead of the S&P 500 Index ($SPX), which gained 12.4%. Cisco has carried that momentum into 2026, with shares advancing 43.2% year-to-date (YTD), compared with a 13.1% rise for the broader benchmark.
Cisco’s performance looks even more impressive against the technology sector, where the State Street Technology Select Sector SPDR ETF (XLK) has gained 26.5% over the past 52 weeks and advanced 32.7% YTD. Although those returns reflect a strong run for technology stocks, Cisco has comfortably outpaced the sector.
At the heart of that transformation lies Cisco’s push into artificial intelligence (AI) infrastructure, which has breathed new life into its established networking business. The company reported record Q4 FY2026 revenue of $17.3 billion, up 17.6% YOY, while hyperscaler AI orders reached $4 billion. These orders lifted FY2026 orders to $9.3 billion, roughly 4.5 times the previous year’s total.
Cisco’s momentum also extends beyond hyperscalers, broadening its market reach. Networking orders climbed 40%, Silicon One chips secured new design wins, and enterprise and sovereign customers continued upgrading their infrastructure. Looking ahead, management expects hyperscaler AI revenue to reach $7.5 billion in FY2027, nearly double this year’s roughly $4 billion.
Wall Street’s ratings reflect this improving outlook, with the 27 analysts covering Cisco arriving at an overall “Moderate Buy” rating. 16 analysts recommend a “Strong Buy,” one assigns a “Moderate Buy,” and 10 rate the stock “Hold.”
Price targets provide another measure of Wall Street’s expectations, with the average target of $133.08 indicating potential upside of 20.7%. Meanwhile, the Street-High target of $165 points to a possible gain of 49.6% from current levels.
On the date of publication, Aanchal Sugandh did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.