
European Oil Stocks Worth Watching As Brent Stays 50% Higher
Oil prices are biting consumers and fuel heavy industries as EU petroleum import costs rise by about €10b per month and Brent sits roughly 50% above 2025 levels. That kind of shock can punish some sectors while creating potential opportunity in others. This piece looks at three European integrated oil majors exposed to these forces and explains how the same headline can offer very different risk and reward profiles.
The stocks covered below are just a small sample, and the full screen surfaced 24 more large European oil majors with similarly detailed stories that are not included in this article. If you want to identify and analyze the highest conviction integrated producers quickly, head straight to the Integrated Oil & Gas Producers (Oil Majors) screener.
Galp Energia SGPS (ENXTLS:GALP)
Galp Energia SGPS is one of the purest examples of what this European oil majors screen is about, with upstream barrels, Portuguese refining and a growing renewables arm all linked to Brent, so it earns a closer look as crude prices reset higher.
Galp Energia runs a full-cycle energy platform, with upstream oil and gas anchored in Brazil, Mozambique and Namibia, and refining, logistics and fuel marketing concentrated in Portugal and Europe. Commercial activities generated about €11.9b in revenue last year, Industrial & Midstream around €10.7b, and Upstream roughly €3.9b, supported by smaller Renewables and Other lines. The group is valued at about €15.6b by the market.
"The ramp up of the newly onstream Bacalhau FPSO, one of the most efficient oil units globally, is expected to lift high margin upstream production volumes through 2026. This supports EBITDA growth and higher operating cash flow."
What really matters next is how one still unresolved pressure affects the balance between rich refining economics and the cost of keeping that growth funded.
That tension is exactly what the full narrative for Galp Energia SGPS unpacks, separating short term cash swings from longer term value drivers that markets may be mispricing.

Orlen (WSE:PKN)
Orlen is the heavyweight of this integrated oil majors screen, tying together refining, petrochemicals, power, gas and fuel retail in Central Europe at a scale where shifts in crude prices and product spreads quickly feed into earnings.
"Orlen's continued investment in low and zero emission capacity, including Baltic Power, Baltic East and Baltic West projects and multiple CCGT plants, is expected to increase electricity and heat output and could support revenue and EBITDA growth from the Energy segment."
What investors really need to watch now is how one hard to quantify funding choice filters through to future margins and dividend flexibility.
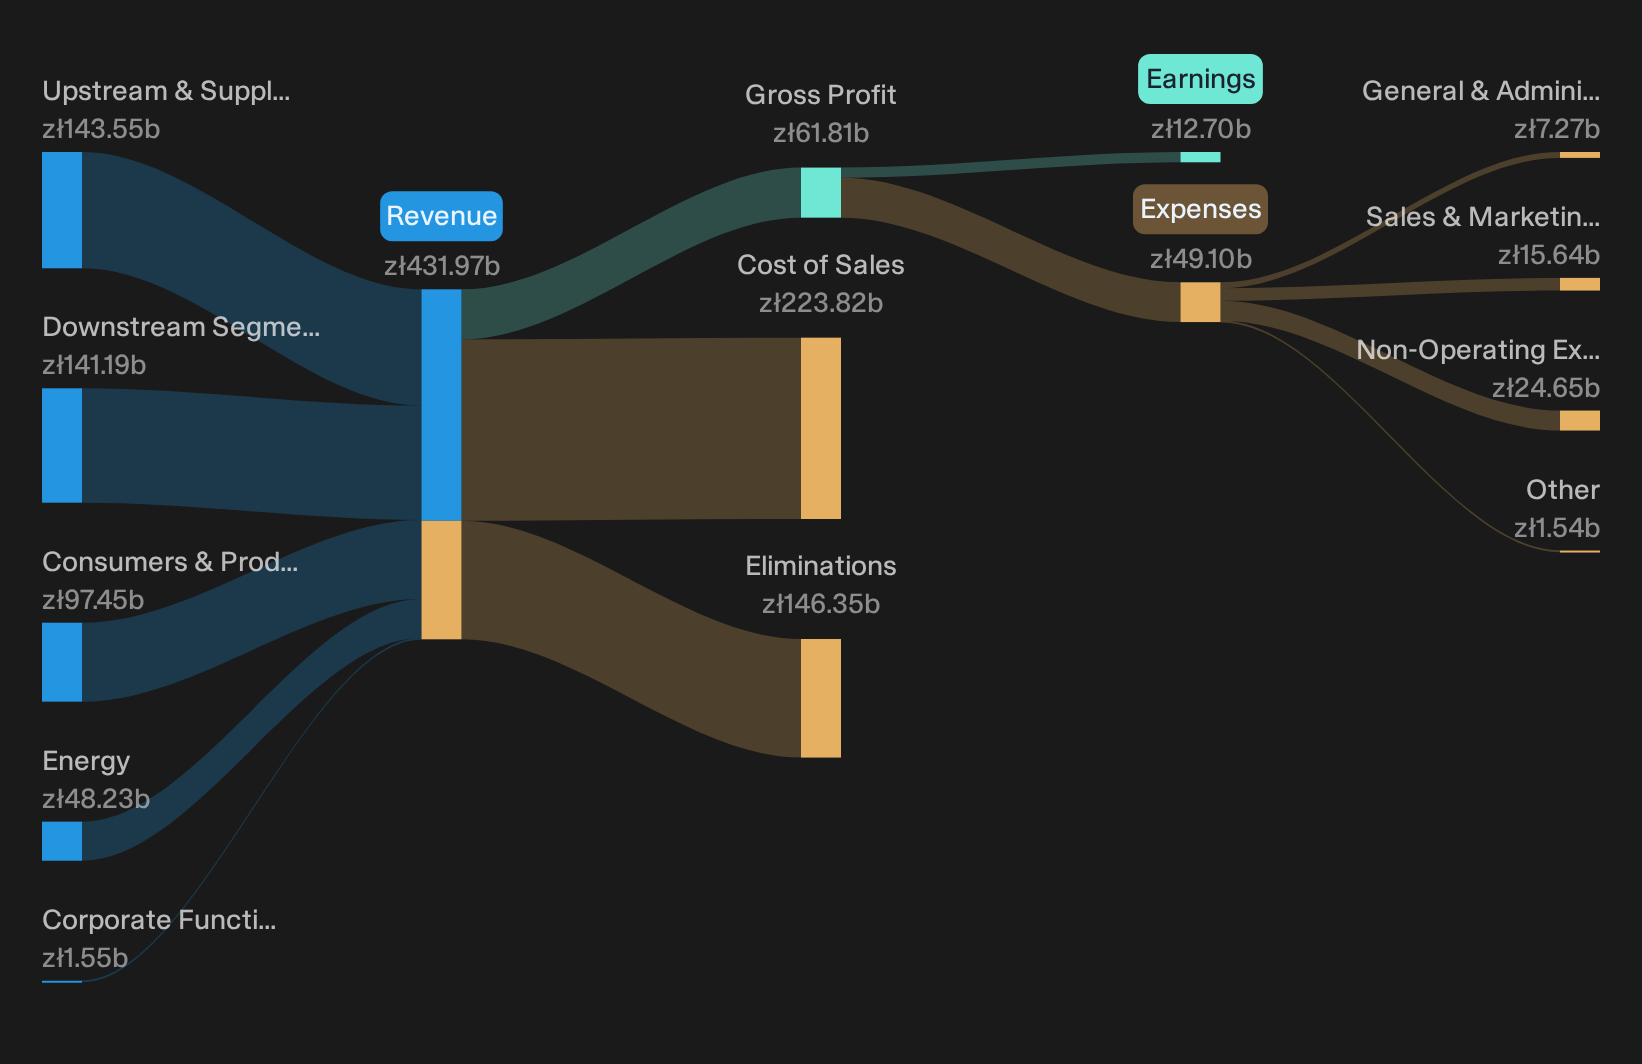
As a European integrated producer, Orlen runs a broad energy platform from crude processing and petrochemicals through to electricity, gas and retail fuels. Upstream & Supply generated about PLN143.6b, the Downstream Segment PLN141.2b, Consumers & Products PLN97.5b and Energy PLN48.2b in revenue, against a market value near PLN173.7b.
That funding trade off is exactly where the full narrative for Orlen picks up, showing how Orlen's capital choices could accelerate or quietly cap the Energy segment story.
MOL Magyar Olaj- és Gázipari Nyilvánosan Muködo Részvénytársaság (BUSE:MOL)
MOL Magyar Olaj- és Gázipari Nyilvánosan Muködo Részvénytársaság is a fully integrated European oil and gas group, linking upstream production, refining, petrochemicals and a wide retail network. Most revenue comes from Downstream on about HUF7,713.5b, with Consumer Services adding HUF3,428.5b, and the business is valued near HUF3,213.7b.
MOL fits the integrated producers theme tightly, with crude linked earnings spread across wells, refineries and service stations. This makes its next growth leg especially interesting as oil prices reset higher.
"Farm in to the Aphrodite gas field offshore Cyprus through the acquisition of a 35% non operated interest in Cyprus Offshore Block 12, with best estimate contingent resources of around 640 million barrels of oil equivalent before host country share, creates an option for MOL Magyar Olaj és Gázipari Nyilvánosan Muködo Részvénytársaság to add a material new reserve base and future gas revenue stream once Final Investment Decision and first gas are achieved, which is not yet reflected in reported earnings or reserves."
What really shapes how MOL benefits from stronger oil and gas markets now is how one still unresolved factor eventually flows through to cash returns.
That unresolved factor is exactly where the full narrative for MOL Magyar Olaj- és Gázipari Nyilvánosan Muködo Részvénytársaság steps in, mapping how Aphrodite, capital choices and pricing could reshape MOL's cash engine beyond headline reserves.

Curious About Fresh Alternatives?
Momentum can shift quickly, and the next breakout list may not stay under the radar for long. Spot fresh ideas before the crowd and act now.
- Target reliable income streams while others chase stories by scanning the curated 226 dividend fortresses, built to highlight potential high-yield payers before yields get compressed.
- Identify businesses with pricing power by running the focused list of solid balance sheet and fundamentals (203 results) and filter for financially resilient companies.
- Explore the buildout of next generation computing momentum by reviewing the tightly filtered 25 quantum computing stocks before more investors focus on potential quantum leaders.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com