
Hims & Hers Health (HIMS) Faces A Valuation Test After Peptide Rule Shift
The catalyst for renewed attention on Hims & Hers Health (HIMS) is a temporary shift in U.S. peptide rules, which opens a window for the business to use its in house compounding capabilities.
Recent headlines around peptides and the expanded testosterone offering arrive after a choppy stretch for Hims & Hers Health, with a 5.01% 1 day share price return and an 8.43% 90 day share price return contrasting with a year to date share price decline of 12.24% and a 1 year total shareholder return that fell 37.12%. The 3 year total shareholder return is very large at nearly 4x and the 5 year total shareholder return is also a multiple of the initial investment. Together, these figures suggest momentum that has cooled in the short term but reflect substantial gains for longer term holders.
Spot 36 healthcare AI stocks that, similar to Hims & Hers Health leaning into peptides and hormone care, are positioned to benefit when regulation, technology, or patient demand quickly shifts.The latest move in Hims & Hers Health looks tied to real shifts in peptide and hormone demand, while the swing in sentiment has been just as sharp. Which side does the current valuation reflect more?
Most Popular Narrative: 83% Undervalued
Hims & Hers Health last closed at $29.32, while the most followed narrative anchors fair value at $171.19 per share. That gap frames peptides, hormones and international expansion as more than just product news, but as key inputs to how some investors are thinking about upside.
Over ten years, Hims & Hers has an unusually large addressable market ahead.
Growth comes from several reinforcing dimensions:
• Market expansion. Digital healthcare adoption globally.
• Category expansion. Hormonal health, longevity, sleep and more.
• International scaling. Canada, Australia, the UK, Germany and further markets, with Brazil and other opportunities ahead.
• Growth within existing categories. Deeper penetration and cross-selling.
Together these form the Multi-Dimensional Growth Engine.
See why 82 investors see Hims & Hers Health as 83% undervalued.
According to Deep_Insights, that long-term view leans on several moving parts. The narrative applies a 7% discount rate, assumes a 9% profit margin and uses a future P/E of 25, then arrives at a fair value of $171.19 per share, which is an 82.9% discount to the current price on this framework.
The same story highlights annual revenue growth of 33% and frames Hims & Hers Health as undervalued relative to that growth and margin mix, even though the business is currently reporting a loss of $142.03m on revenue of $2,578.11m. It also points to international revenue and category expansion as key reasons the fair value in that model sits far above both the recent close and the average analyst price target of $31.15.
Result: Fair Value of $171.19 (UNDERVALUED)
Still, if GLP 1 rules tighten again or international rollouts slow, the bullish Hims & Hers Health narrative could reset very quickly.
Find out about the key risks to this Hims & Hers Health narrative.
Another View: Market Pricing Looks Less Generous
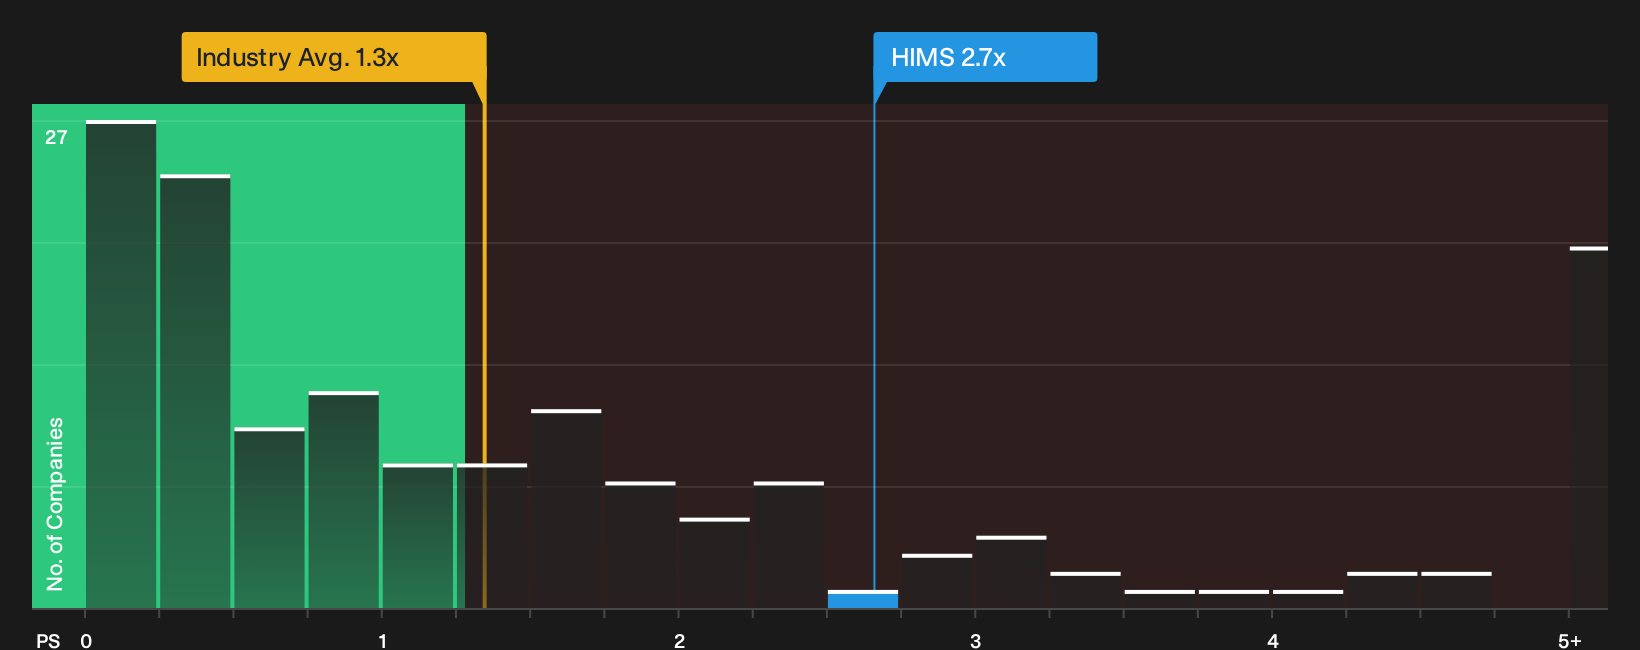
That 83% upside story leans on long-range assumptions. The simpler read is the current P/S of 2.7x for Hims & Hers Health, which screens as expensive versus both the US Healthcare industry on 1.3x and peers on 2.3x, even if it still sits below a fair ratio of 4.6x. Is the gap a cushion or a warning sign?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed feelings on Hims & Hers Health so far, or does the setup feel clearer now that you have the numbers in front of you? Act while the peptide debate and sentiment are still moving, and stress test the bullish and cautious angles for yourself by reviewing the 2 key rewards and 1 important warning sign.
Looking for more Hims & Hers Health style investment ideas?
If the Hims & Hers Health setup has you thinking about what else could be hiding in plain sight, broaden your watchlist before the next move passes you by.
- Target potential mispricing early by scanning companies that screen as high quality yet out of favor through the 26 high quality undervalued stocks.
- Prioritize resilience by focusing on businesses with stronger finances using the list of solid balance sheet and fundamentals (24 results).
- Hunt for lesser known opportunities with robust fundamentals via the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com