
Sweco (OM:SWEC B) Framework Wins Put Its Undervalued Narrative Back In Focus
Sweco (OM:SWEC B) has landed several large framework agreements in recent weeks, including new consultancy roles with Aalborg Forsyning, Dutch transport operator GVB and Swedish property group Specialfastigheter.
These contract wins come as Sweco’s share price has picked up recently, with a 1-day share price return of 1.85%, a 7-day gain of 7.73% and a 30-day increase of 11.33%. This is even though the year to date share price return is down 3.5% and the 1-year total shareholder return has declined 13.58%, while the 3-year total shareholder return is up 50.92% and the 5-year total shareholder return is 14.58%. This pattern suggests that momentum has improved in the short term, while the longer record still reflects mixed outcomes for different holding periods.
Scan other infrastructure focused engineers showing similar contract momentum with our curated 44 power grid technology and infrastructure stocks as you weigh Sweco’s latest framework wins.
Sweco looks like a capable infrastructure adviser with fresh contract visibility, yet the share price has only recently started to recover. The question is whether that recent rebound still leaves room for a reasonable entry valuation.
Most Popular Narrative: 16% Undervalued
Sweco last closed at SEK143.5, while the most followed narrative points to a fair value of SEK170.5, so the current quote sits below that anchor and puts the recent contract wins against a discounted starting point.
The broad roll out of AI tools across Sweco, including an internal platform used weekly by over 70% of employees and targeted at productivity and process automation, creates scope for higher revenue per employee and improved net margins as these tools are embedded in client work. The structural shortage of STEM talent in Europe of roughly 2 million experts, together with Sweco's efforts to use AI to raise productivity and to support higher pricing, can sustain pricing power and support both revenue levels and EBITA margin over the coming years.
See why 6 investors see Sweco as 16% undervalued.
Result: Fair Value of SEK170.5 (UNDERVALUED)
Still, weak demand in real estate related work and slower progress in Finland could weigh on Sweco’s margins and challenge the current undervaluation case.
Find out about the key risks to this Sweco narrative.
Another View On Sweco’s Valuation
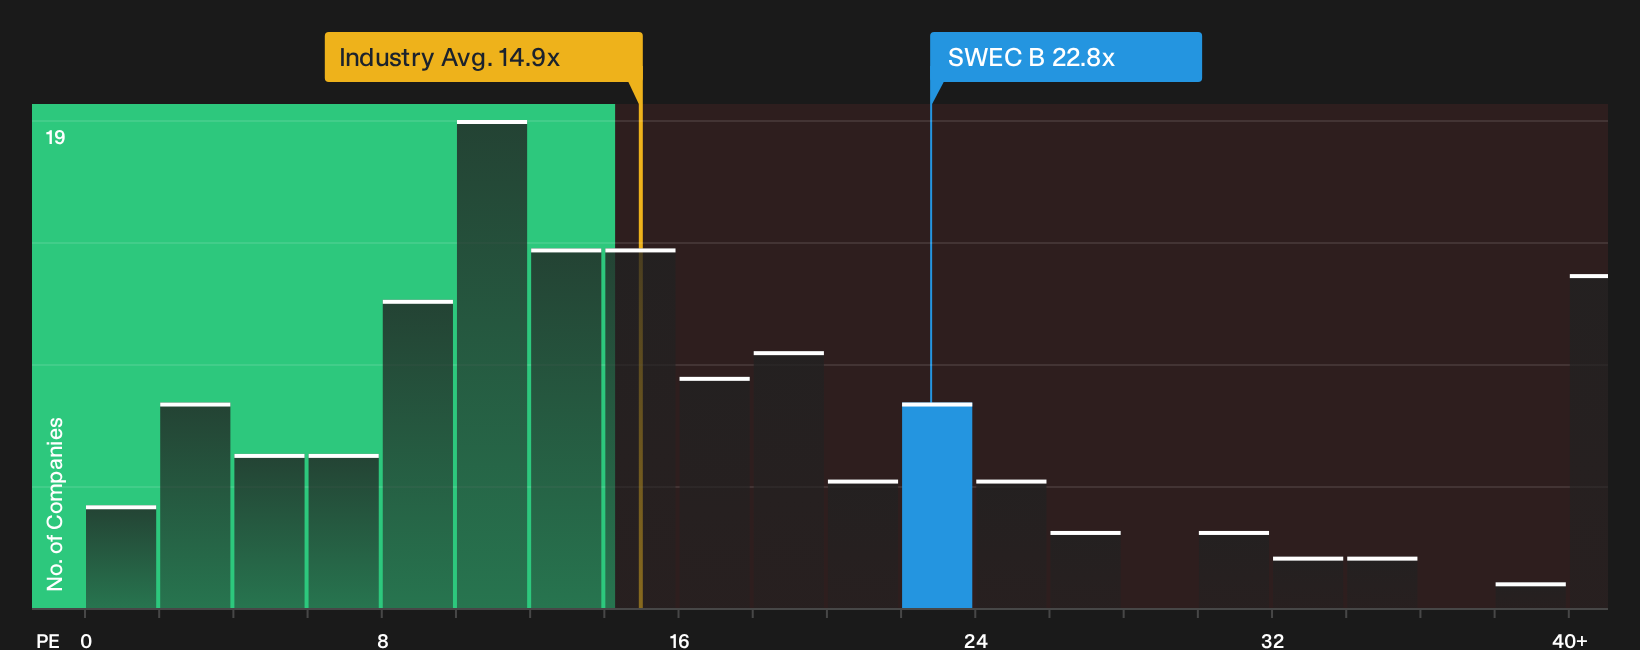
The first narrative leans on discounted cash flows to argue Sweco is undervalued. A simple P/E cross check tells a different story. Sweco trades on 22.8x earnings, above the European Construction sector at 15x and above peers at 17.3x, even though the fair ratio sits at 23.8x. That combination of relatively high current pricing and a fair ratio that is only slightly higher raises the question of how much potential upside may remain if sentiment cools.
For a closer look at how these earnings multiples compare, including where valuation risk may sit if the market shifts toward the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Sweco so far and the clock is always ticking on sentiment shifts, so pull up the data, test the assumptions and weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Sweco?
You have done the work on Sweco. Now widen the lens and pressure test your thesis against other opportunities that match your risk, income and value priorities.
- Target steadier compounding by checking companies with resilient fundamentals and low perceived risk through our 228 resilient stocks with low risk scores.
- Hunt for mispriced quality by scanning the 191 high quality undervalued stocks that combine solid finances with value focused pricing.
- Spot potential early stage opportunities by reviewing the 131 elite penny stocks with strong financials that also clear basic financial strength checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com