
What Coca Cola FEMSA Shares Strong Q3 Earnings Means For Shareholders
- Coca-Cola FEMSA reported Q3 2026 sales of MXN 79,360 million and net income of MXN 6,223 million, with both sales and profit higher than the prior year period.
- The nine month figures show revenue of MXN 227,190 million and net income of MXN 16,784 million, while management still called out margin pressure in Mexico and Central America despite record volumes.
- We will now look at how Coca-Cola FEMSA's investment narrative is shaped by strong Q3 earnings alongside ongoing margin pressure.
Coca-Cola FEMSA. de Investment Narrative Recap
To back Coca-Cola FEMSA, an investor needs to believe that its large Latin American footprint, strong brands and execution tools like Juntos+ can keep volumes and pricing resilient while consumers in markets such as Mexico remain cautious. The latest quarter supports that idea, with higher sales and net income and record volumes giving the story fresh momentum.
The key short term catalyst is whether Coca-Cola FEMSA can translate this volume strength into steadier profitability as marketing, freight and tax related costs bite in Mexico and Central America. Margin pressure remains the biggest operational risk, and recent results highlight that this issue is still very much live.
The most relevant update for that debate is the Q3 2026 report itself. Coca-Cola FEMSA booked quarterly revenue of MXN 79,718 million and net income of MXN 6,223 million, while nine month revenue reached MXN 227,190 million and net income was MXN 16,784 million. Management also pointed to record volumes, which matters for operating leverage over time.
Those figures sit alongside comments about ongoing margin strain in Mexico and Central America as higher operating expenses and regulatory costs meet a subdued consumer. Execution on digital tools, product mix toward zero sugar and affordability levers now looks central to any catalyst. The near term question is whether those efforts can offset cost pressure without sacrificing volumes.
Coca-Cola FEMSA. de's current narrative points to revenue of MX$376.2b and earnings of MX$31.3b by 2029, based on analysts' assumption of 8.3% yearly revenue growth and an earnings increase of about MX$7.4b from MX$23.9b today.
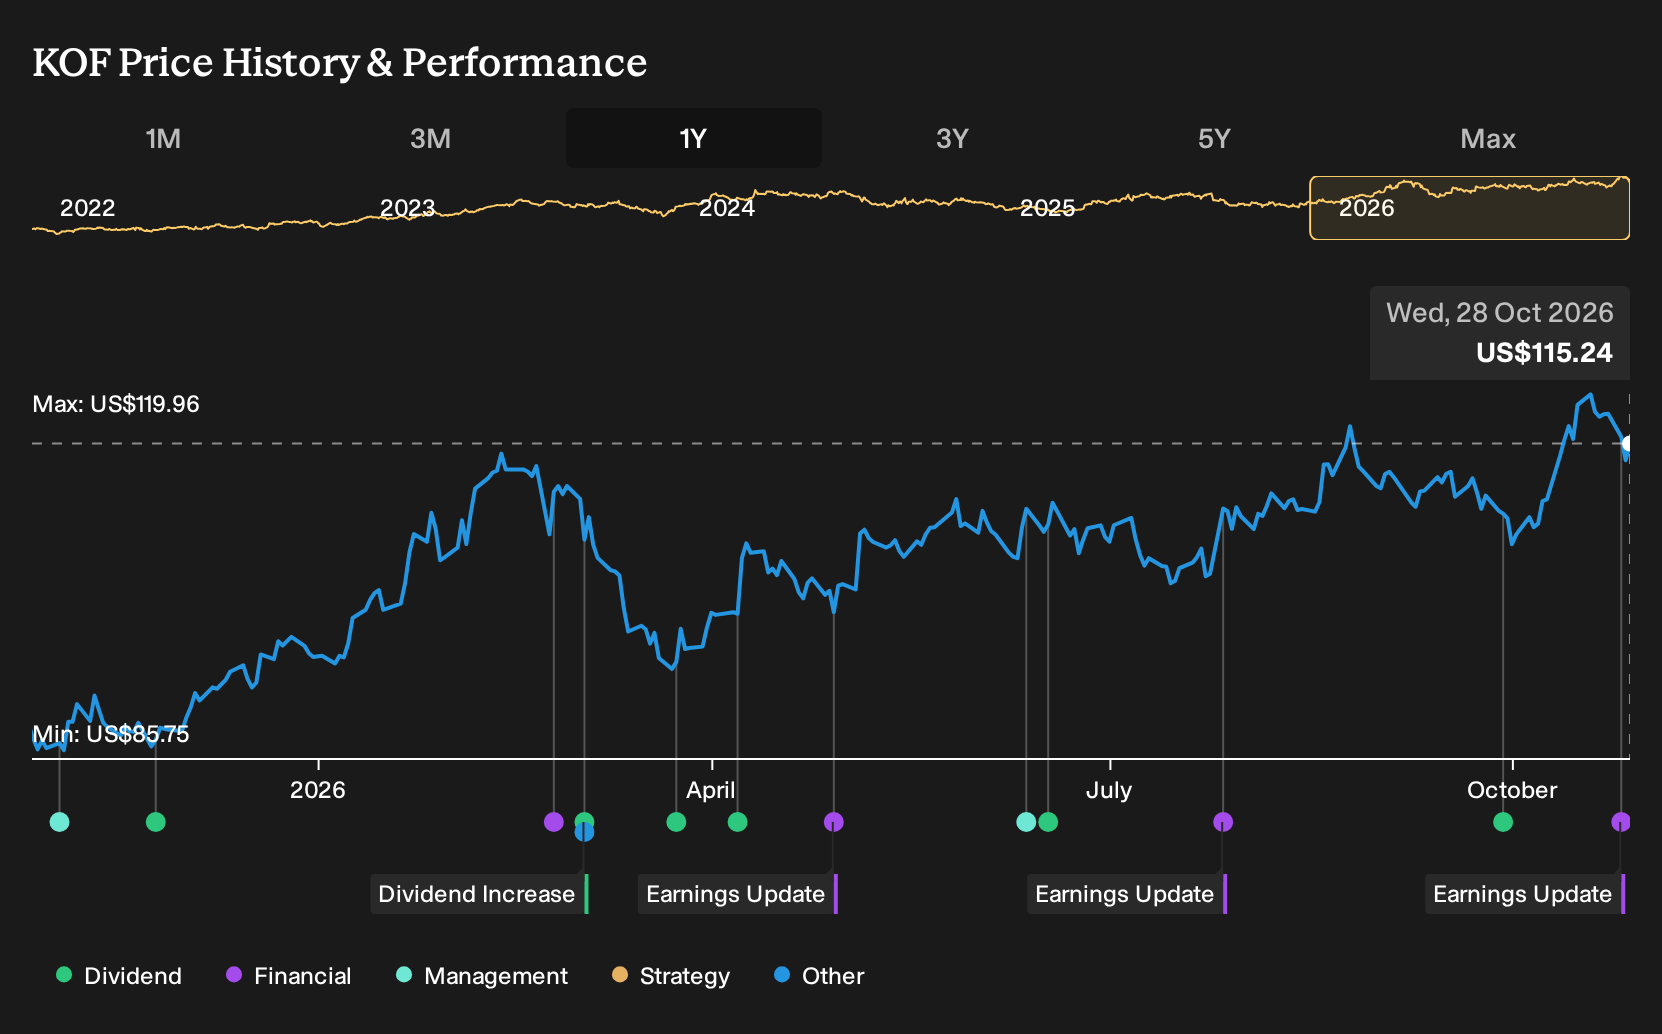
Uncover why Coca-Cola FEMSA. de's fair value indicates a 6% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternative angle focuses less on digital tools and more on South America turning into Coca-Cola FEMSA’s main earnings engine. The most optimistic analysts were penciling in revenue of about MX$370.6b and earnings near MX$34.3b by 2029 before this Q3 release. You can compare those upbeat assumptions with today’s margin questions and decide which story feels closer to your own view, knowing fresh results may nudge both narratives in new directions.
Explore 4 other Coca-Cola FEMSA. de fair value estimates, including one that suggests up to 46% potential upside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Coca-Cola FEMSA. de research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Coca-Cola FEMSA. de. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Coca-Cola FEMSA. de's overall financial health at a glance.
Looking for more investment ideas beyond Coca-Cola FEMSA?
Once you have formed a view on Coca-Cola FEMSA, it can help to widen the lens and compare it with other companies that fit different risk, income, or balance sheet profiles using the Simply Wall St Screener.
- For investors who want stability first, consider a 32 resilient stocks with low risk scores that have historically handled volatility with fewer swings in their risk scores.
- If income is your priority, scan a curated 6 dividend fortresses that target higher yields while still keeping an eye on fundamentals.
- When balance sheet strength matters most, filter for a list of solid balance sheet and fundamentals (24 results) to see which businesses pair solid finances with consistent operating profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com