
Will Mixed Earnings Change AAK's (OM:AAK) Narrative
- AAK AB (publ.) reported third quarter 2026 revenue of SEK 11,965 million and net income of SEK 837 million, alongside nine month revenue of SEK 34,713 million and net income of SEK 2,602 million, compared with the same periods in 2025.
- The quarter showed lower earnings per share despite higher net income over nine months, which gives a mixed signal on how AAK AB (publ.) is converting a broadly stable top line into shareholder returns.
- We will now look at how AAK AB (publ.)'s investment narrative lines up with softer quarterly earnings per share but steadier nine month profitability.
Compare how AAK AB (publ.) stacks up on earnings quality by scanning a hand picked 609 high quality undiscovered gems that may be flying under most investors' radar.
AAK AB (publ.) Investment Narrative Recap
To stay invested in AAK AB (publ.), you need to be comfortable with a story that leans on mix improvement in higher value fats, tight cost control and disciplined capital use rather than rapid top line expansion. The latest quarter fits that pattern. Revenue was broadly similar to last year while earnings per share for the quarter softened, so the near term focus stays on margins and execution.
The key short term catalyst remains delivery on programs like Fit to Win and Cash to Grow, which are aimed at offsetting pressure in Food Ingredients and currency headwinds. The main risk is that production issues in Karlshamn and competitive pricing in dairy and bakery continue for longer, which could keep segment profitability under strain. The third quarter numbers do not radically change that balance between risk and potential reward.
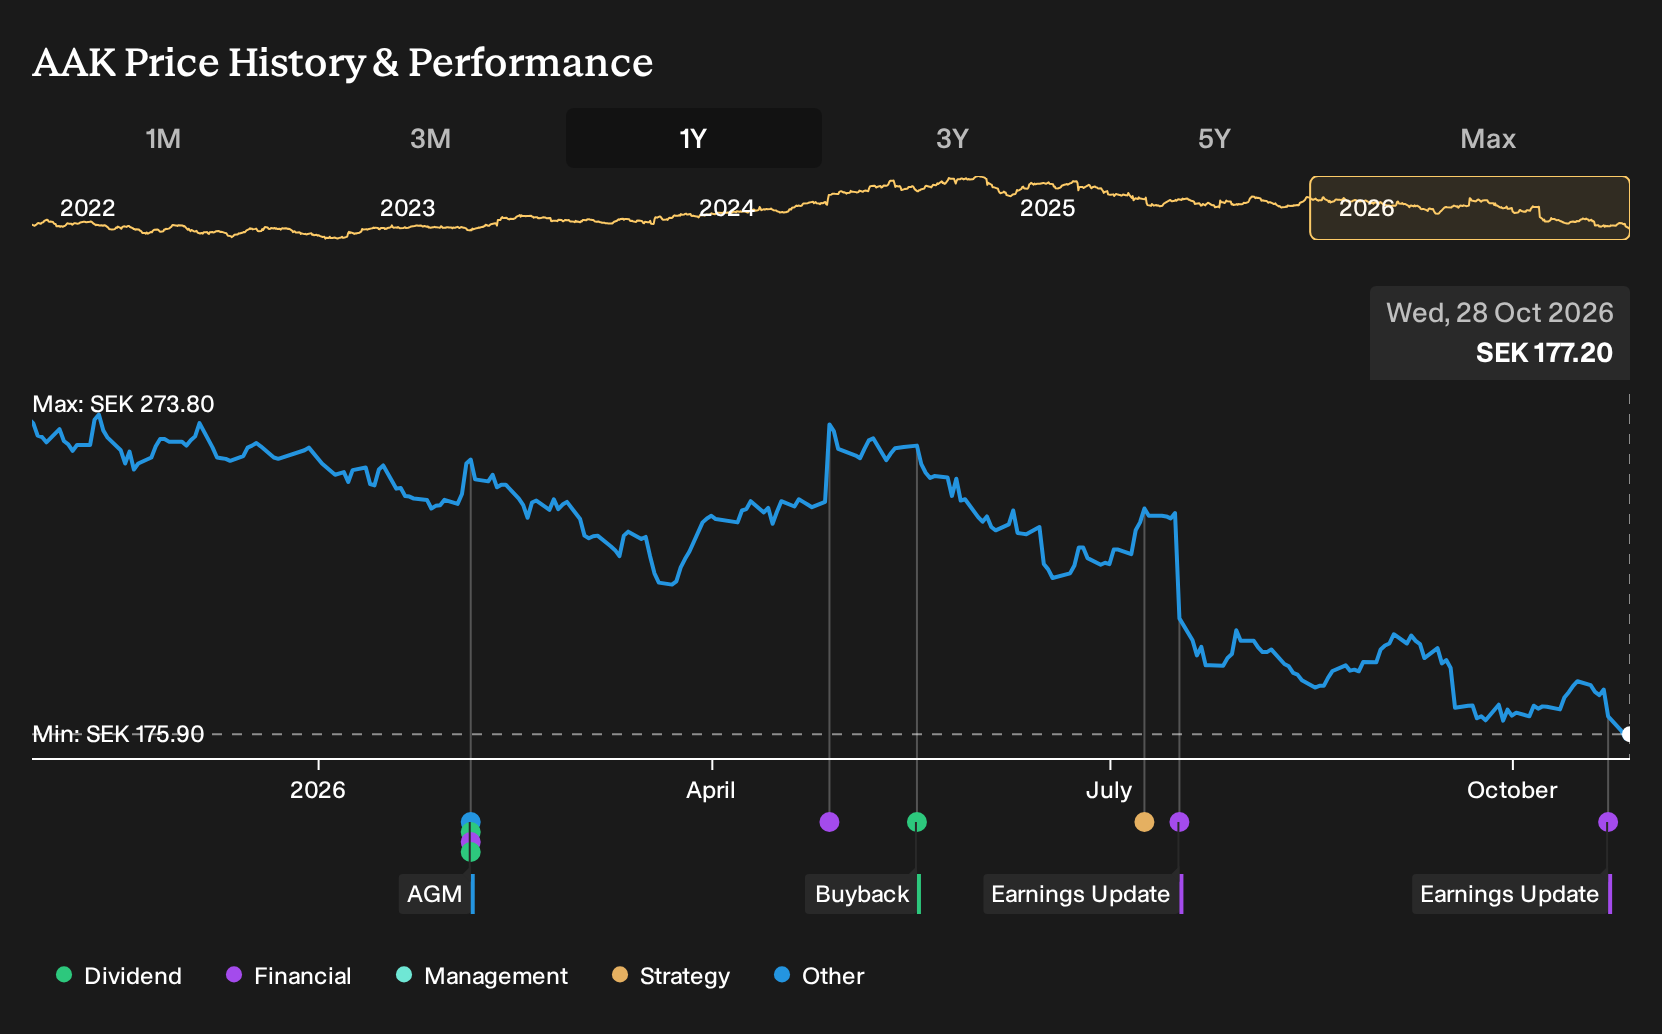
The most relevant fresh data point for that story is the third quarter 2026 report itself. AAK AB (publ.) posted quarterly net income of SEK 837 million compared with SEK 909 million a year earlier, while nine month net profit reached SEK 2,602 million versus SEK 2,483 million. Earnings per share dipped in the quarter but rose over nine months, which gives a mixed signal on earnings quality in the near term.
Set against the known catalysts, that pattern keeps the spotlight on how quickly management can stabilise Food Ingredients profitability and deliver the remaining Fit to Win savings. The figures also intersect with currency risk, since earlier periods showed a gap between constant currency profit trends and reported EBIT. For you as a shareholder, the operational question is whether cost programs and mix shifts can offset these headwinds while the business keeps serving demand across its core categories.
Analysts currently expect AAK AB (publ.) to reach SEK 51.6b in revenue and SEK 4.4b in earnings by 2029, which implies 4.2% yearly revenue growth and an earnings increase of about SEK 0.8b from SEK 3.6b today.
Uncover how AAK AB (publ.)'s fair value indicates a 36% potential upside to its current price before the market closes the gap.
Exploring Other Perspectives
Some of the most optimistic analysts focus on AAK AB (publ.)’s capex plans as a potential catalyst. Before this earnings release, they were assuming revenue of about SEK 59.5b and earnings near SEK 4.6b by 2029. That is a very different story compared with softer Q3 EPS. Use this gap to compare several viewpoints before deciding your own.
Explore 3 other AAK AB (publ.) fair value estimates, including one that suggests as much as 80% potential increase from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your AAK AB (publ.) research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for AAK AB (publ.). The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AAK AB (publ.)'s overall financial health at a glance.
Looking for more investment ideas beyond AAK AB (publ.)?
If the latest AAK AB (publ.) update has you reassessing your watchlist, it can help to set this stock alongside a broader set of opportunities that match your risk and income preferences. The Simply Wall St Screener lets you filter for exactly the type of businesses you want to research next.
- For investors hunting for companies that look mispriced based on fundamentals, start by scanning a focused list of 191 high quality undervalued stocks that might warrant a closer look.
- If capital preservation is near the top of your priorities, narrow your search to a 228 resilient stocks with low risk scores that could help you compare steadier profiles side by side.
- When you want balance sheet strength to back up the story, use the screener to review a curated list of solid balance sheet and fundamentals (203 results) and see how they measure up against your criteria.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com