
Is Broadstone Net Lease (BNL) A Bargain On Earnings And Its Build To Suit Pipeline?
Earnings trigger and what it means for Broadstone Net Lease
Broadstone Net Lease (BNL) just reported third quarter 2026 results, with sales of US$121.87 million and net income of US$27.12 million. Earnings per share remained at US$0.14 from continuing operations.
Recent news has been busy for Broadstone Net Lease, from third quarter 2026 earnings and a public equity raise to updated research views. Yet the share price has drifted, falling about 10.5% over the past month and 21.6% over 90 days. Against that weaker short term share price return, the 3 year total shareholder return of about 46.4% and broadly flat 1 year total shareholder return suggest longer term holders have still seen meaningful value creation even as near term sentiment cools around the US$16.86 level.
Capitalize on the reset in Broadstone Net Lease by scanning a hand-picked 26 high quality undervalued stocks that share similar quality traits but may be pricing in very different expectations.The share price reset leaves Broadstone Net Lease trading well below its recent levels, while analyst targets and long term returns tell a different story. Is this a reasonable entry now, or a setup to wait for cheaper terms?
Most Popular Narrative: 29% Undervalued
Broadstone Net Lease is framed by the leading narrative as trading well below an estimated fair value of $23.60, compared with the latest close at $16.86. This puts the focus squarely on whether the existing development pipeline justifies that gap.
The ongoing build-to-suit program, with about US$645 million of committed and in-process projects at a 7.9% initial cash yield, a 9.9% straight-line yield, a 13.7 year average lease term and 2.7% annual rent escalators, is set to add new rental streams that feed directly into revenue and AFFO growth.
See why 10 investors see Broadstone Net Lease as 29% undervalued.
Result: Fair Value of $23.60 (UNDERVALUED)
Still, the Broadstone Net Lease story depends on execution. A slower build-to-suit ramp up or lower than expected future P/E multiples could quickly pressure that undervalued thesis.
Find out about the key risks to this Broadstone Net Lease narrative.
Another View: What Broadstone Net Lease’s P/E Is Telling You
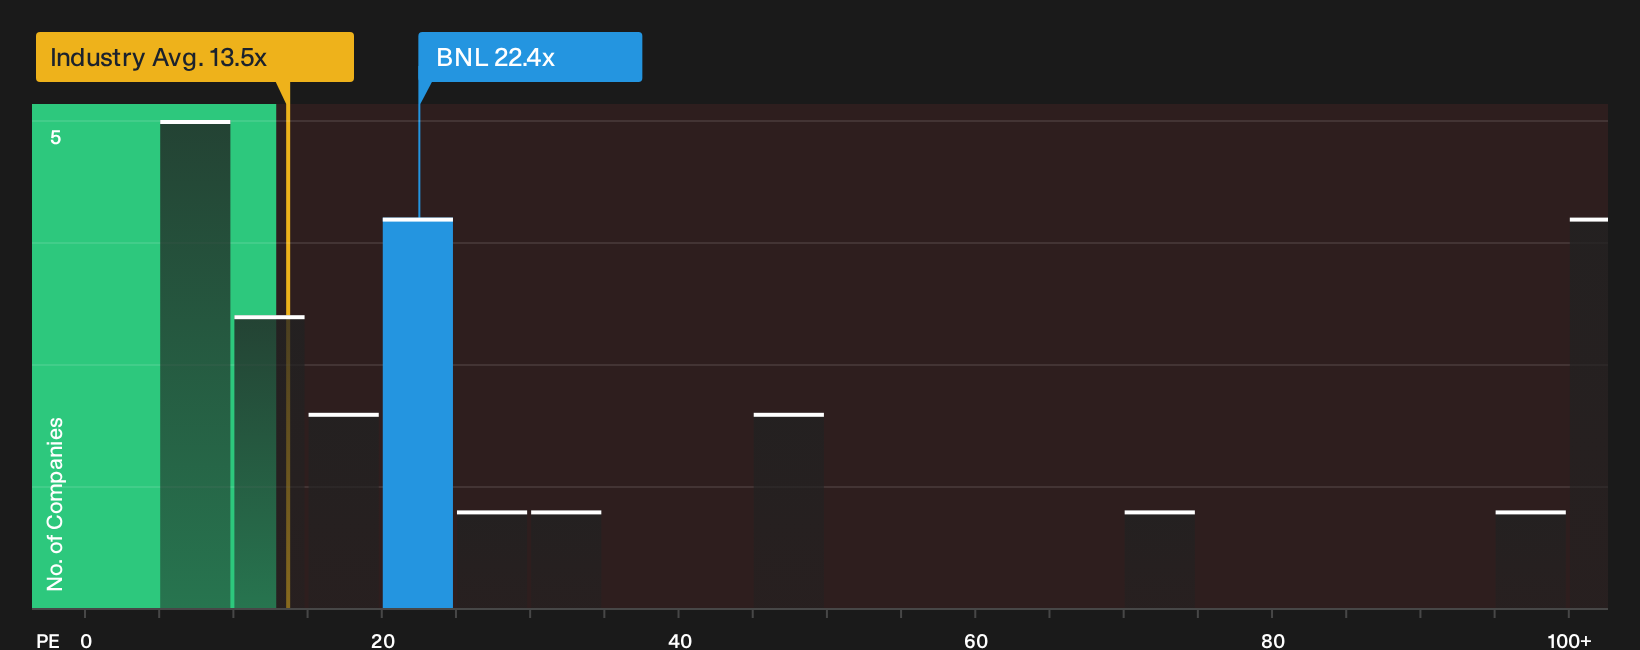
On a cash flow model, Broadstone Net Lease screens as undervalued. Its P/E of 22.4x is well above the global REITs average of 13.6x and below an estimated fair ratio of 34.2x. That mix of discount and premium creates a simple question: How much valuation risk are you really comfortable with at this price?
For a closer look at how the earnings multiple stacks up against peers and that fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the mixed tone around Broadstone Net Lease matches your own read of the facts, yet concerned that waiting too long could blur the signal? Take a fresh look at both sides of the story by weighing the 4 key rewards and 1 important warning sign.
Looking for more Broadstone Net Lease sized ideas?
Use this reset in Broadstone Net Lease as a moment to refresh your watchlist and line up your next round of well researched investment candidates.
- Target stronger upside potential by scanning a curated pool of 19 high quality undiscovered gems hiding in plain sight before the crowd catches on.
- Prioritise resilience first and hunt through a 32 resilient stocks with low risk scores that filters for sturdier balance sheets and steadier return profiles.
- Build a cash focused shortlist by reviewing a 6 dividend fortresses designed for investors who care about income strength as much as price moves.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com