
Enova International (ENVA) Posted Strong Q3 Results, Is The Stock Still Below Fair Value?
Enova International (ENVA) has drawn fresh attention after reporting third quarter 2026 results, with revenue of US$614.36 million and net income of US$107.3 million, alongside new guidance and continued share repurchases.
Recent earnings, higher fourth quarter guidance, and active buybacks have arrived after a sharp 90 day share price decline of about 29%, even as the 1 year total shareholder return of 48.15% and 3 year total shareholder return above 3x point to longer term momentum building again for Enova International.
Assess how Enova International fits into your portfolio by comparing it with a hand picked 26 high quality undervalued stocks that also combine solid cash flows with stronger balance sheets.Enova International just paired strong recent results and buybacks with a sharp 90 day pullback. Does that combination still tip the risk reward balance toward buyers, or has the easy upside already passed?
Most Popular Narrative: 25% Undervalued
At a last close of $179.82 versus a narrative fair value of $238.50, the current Enova International price sits well below what that widely followed thesis implies. This puts a lot of weight on how its funding model and AI driven underwriting hold up in practice.
The key thing that has to go right is that Enova International maintains stable credit performance and reliable capital markets funding while it leans further into non bank small business and non prime consumer lending and broader use of machine learning and generative AI.
The sharp share price drop of roughly 22% to 25% after the Grasshopper decision, together with multiple legal investigations and recent analyst price target cuts, signals that investor confidence can weaken quickly.
See why 11 investors see Enova International as 25% undervalued.
Result: Fair Value of $238.50 (UNDERVALUED)
Still, tighter consumer lending regulation or a tougher capital markets backdrop could quickly challenge Enova International’s funding access and place pressure on its non prime lending model.
Find out about the key risks to this Enova International narrative.
Another View: What Enova International’s P/E Is Really Saying
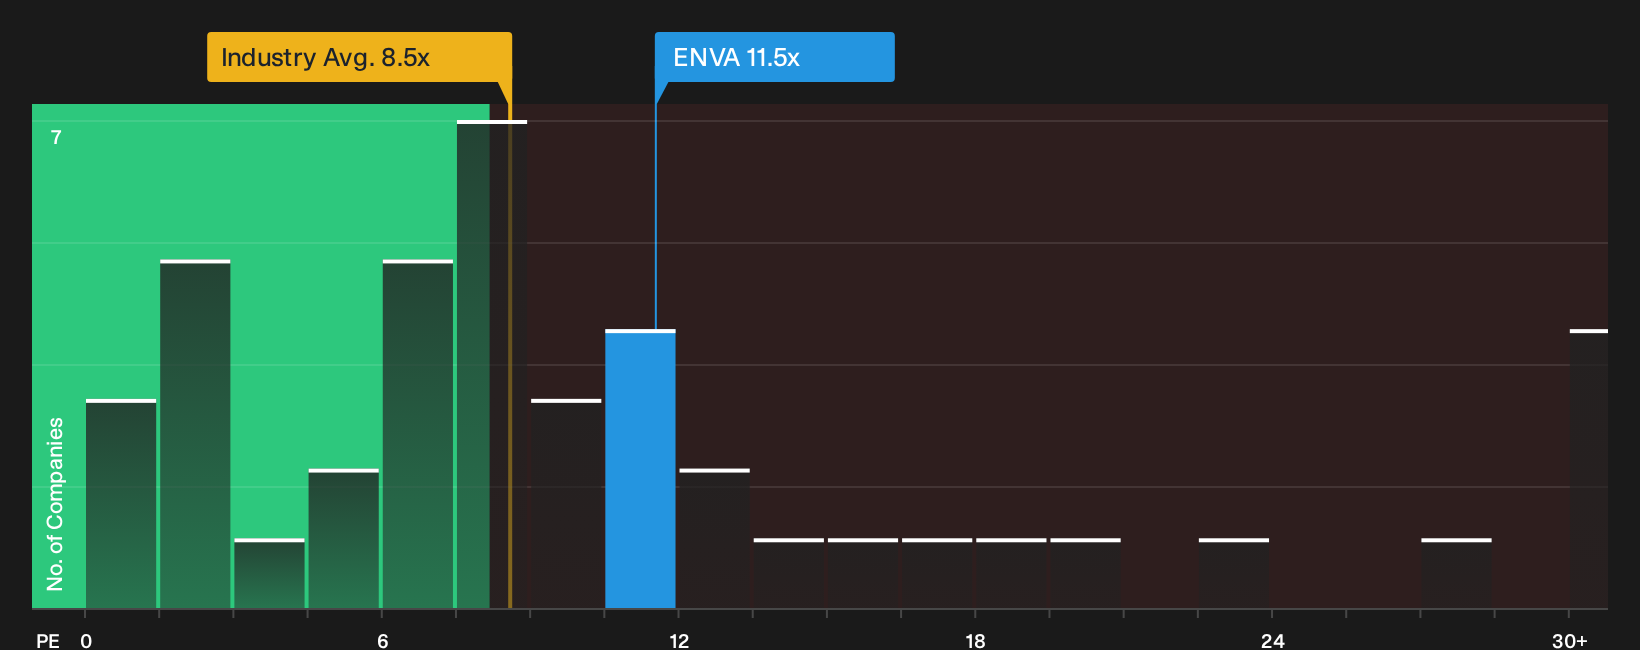
That fair value of $238.50 paints Enova International as undervalued, yet the current P/E of 11.5x tells a more cautious story. It sits above the US Consumer Finance industry on 8.5x, but below a fair ratio of 14.7x and the peer average of 12.5x. Is that middle ground a margin of safety or a warning that expectations already carry plenty of good news?
Before leaning too heavily on one narrative, it is worth stress testing these valuation signals and seeing how the current multiples line up with your own expectations for credit risk, funding costs, and growth capacity over the next few years. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals like these often split opinion on Enova International, so consider reviewing the data promptly and reaching your own conclusion using the 4 key rewards and 1 important warning sign.
Looking for more Enova International investment ideas?
If Enova International has your attention, do not stop there. Broaden your watchlist now and avoid missing opportunities that better match your risk and return preferences.
- Target quality at a discount and see which companies combine resilient fundamentals with appealing entry points through the 26 high quality undervalued stocks.
- Prioritize resilience and focus on businesses with stronger finances and cleaner balance sheets using the list of solid balance sheet and fundamentals (24 results).
- Hunt for underfollowed opportunities and track companies with stronger fundamentals that attract less attention via the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com