
What DuPont (DD) Q3 Earnings Setup Means For Shareholders
- DuPont de Nemours has launched AmberChrom SIL silica gel, a reverse phase silica media in C8 and C18 chemistries aimed at high purity peptide purification, including GLP 1 receptor agonists, to support both process development and manufacturing scale up in biopharma.
- The new AmberChrom SIL offering can be combined with existing AmberChrom XT, TQ1 and CG resins, giving peptide producers a single, integrated purification toolkit that targets yield, purity and workflow simplicity in a part of DuPont's portfolio tied to long term healthcare demand.
- We will now look at how DuPont de Nemours' investment narrative could be influenced by this new AmberChrom SIL peptide platform.
Scan beyond DuPont de Nemours and this peptide purification update by lining up peers exposed to similar long term healthcare demand using our curated 36 healthcare AI stocks.
DuPont de Nemours Investment Narrative Recap
To own DuPont de Nemours, you need to be comfortable with a focused industrial group that leans on healthcare, water and specialty materials, where execution on cost, productivity and product development matters more than rapid top line expansion. The AmberChrom SIL launch fits that story but looks incremental to the overall portfolio rather than a sweeping change in the near term.
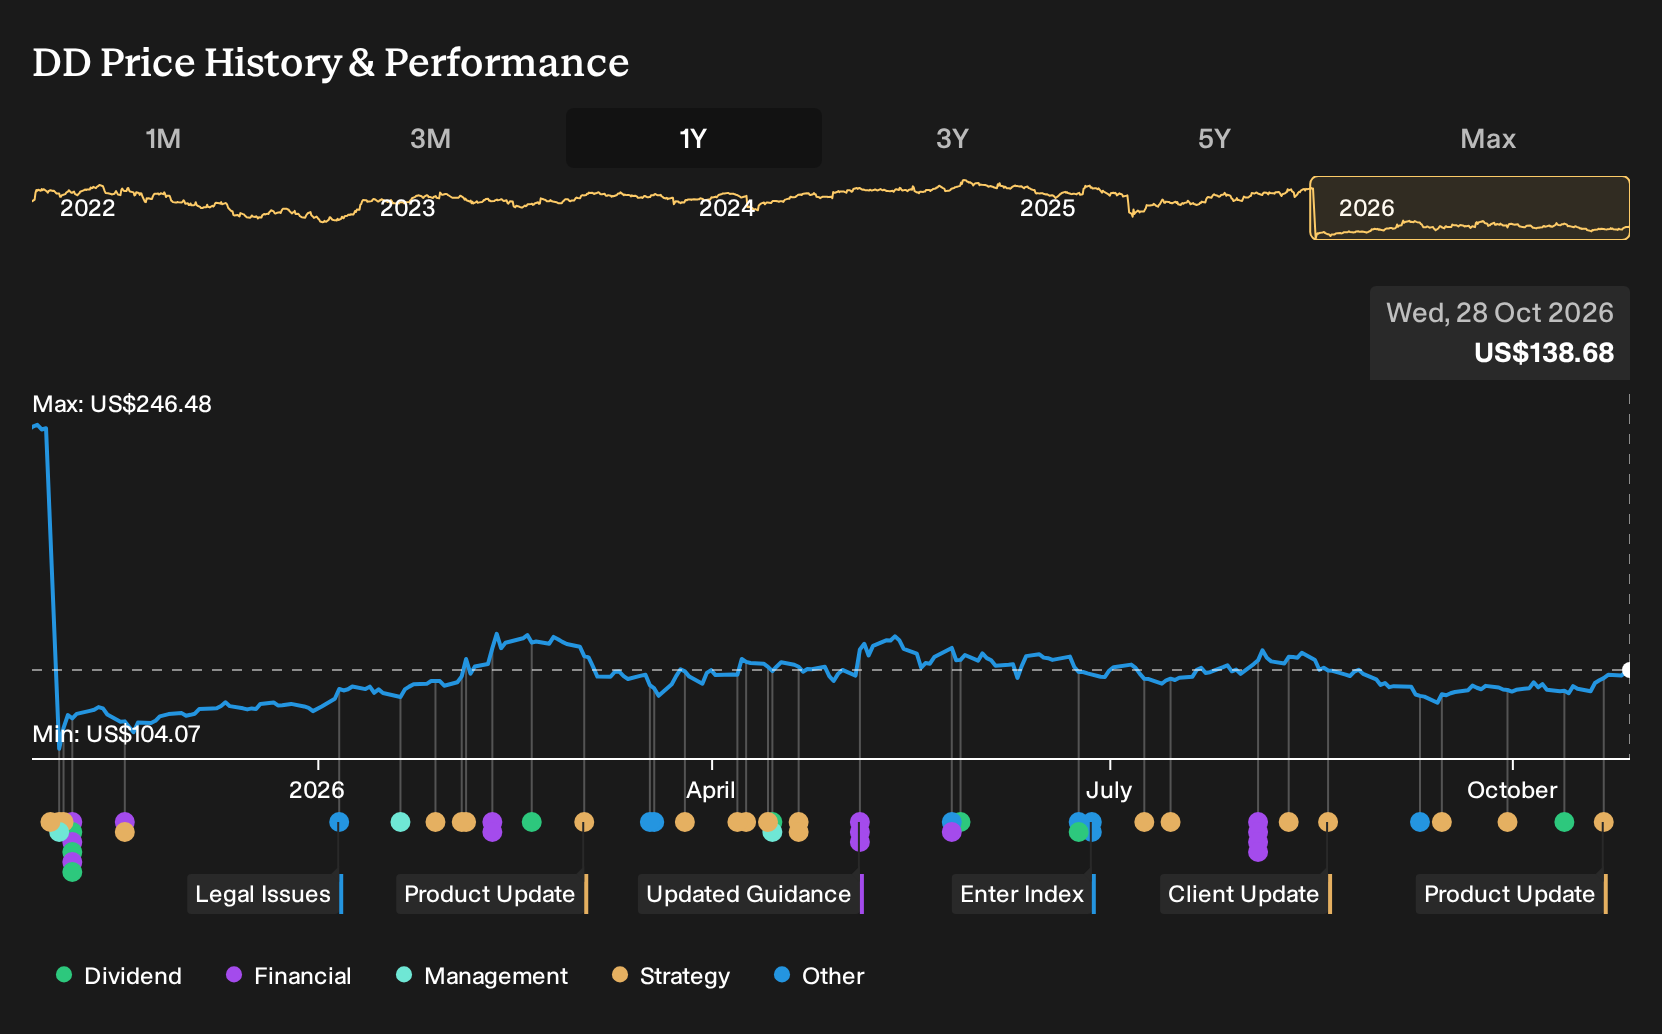
Right now, the key short term catalyst is how DuPont de Nemours converts its raised 2026 outlook into clean earnings, especially with Q3 results due on 3 November and consensus pointing to lower EPS for the quarter. The biggest risk remains environmental and legal exposure plus cost inflation and pricing friction, which could consume cash that might otherwise support growth and capital returns.
The most relevant recent datapoint alongside AmberChrom SIL is the upcoming Q3 FY2026 print, with analysts expecting EPS of US$1.86 and a year over year decline even after several past estimate beats. That setup means the market focus is likely to stay on earnings quality and how much of the headline number is affected by one off items.
Viewed together, the peptide purification launch and the pending results highlight the same question for DuPont de Nemours. Can the business keep turning targeted R&D spend in areas like biopharma into durable margins and free cash flow while carrying PFAS obligations, slower water project activity in parts of EMEA and input cost inflation that pressures pricing power and dividend coverage?
DuPont de Nemours’ current analyst storyline points to revenues of US$7.9b and earnings of US$974.5m by 2029, built on an assumed 4.4% yearly revenue growth rate and an earnings move of about US$668.5m, from US$306.0m today to that 2029 consensus figure.
Uncover why DuPont de Nemours' fair value indicates a 20% potential upside to its current price before that discount to DuPont de Nemours closes.
Exploring Other Perspectives
One alternate view focuses on environmental cash costs rather than products like AmberChrom SIL. The most bearish DuPont de Nemours analysts were working off roughly US$7.8b of 2029 revenue and about US$995.3m of earnings before this launch, which is actually slightly above consensus earnings. That more optimistic profit line, paired with a lower US$145.0 price target, illustrates how differently risk and reward can be weighed. You can treat this product news as a prompt to compare those assumptions and decide which story feels closer to your own expectations.
Explore 3 other DuPont de Nemours fair value estimates, including one that suggests it could be worth just $145.00.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your DuPont de Nemours research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for DuPont de Nemours. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DuPont de Nemours' overall financial health at a glance.
Looking for more DuPont de Nemours style ideas?
If DuPont de Nemours fits your preference for clear cash flow stories and real-world products, it can help to line it up against other potential opportunities that share some of those qualities. The Simply Wall St screener gives you a structured way to do that comparison instead of jumping between tickers without a plan.
- If capital preservation is near the top of your list, start with sturdier balance sheets and lower risk profiles via our 32 resilient stocks with low risk scores.
- For investors who care most about paying a fair price for solid fundamentals, line up potential ideas using the 26 high quality undervalued stocks.
- When you want resilient business models that can compound steadily in the background, broaden your watchlist with a list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com