
What KION GROUP Investors Missed Before The Fall
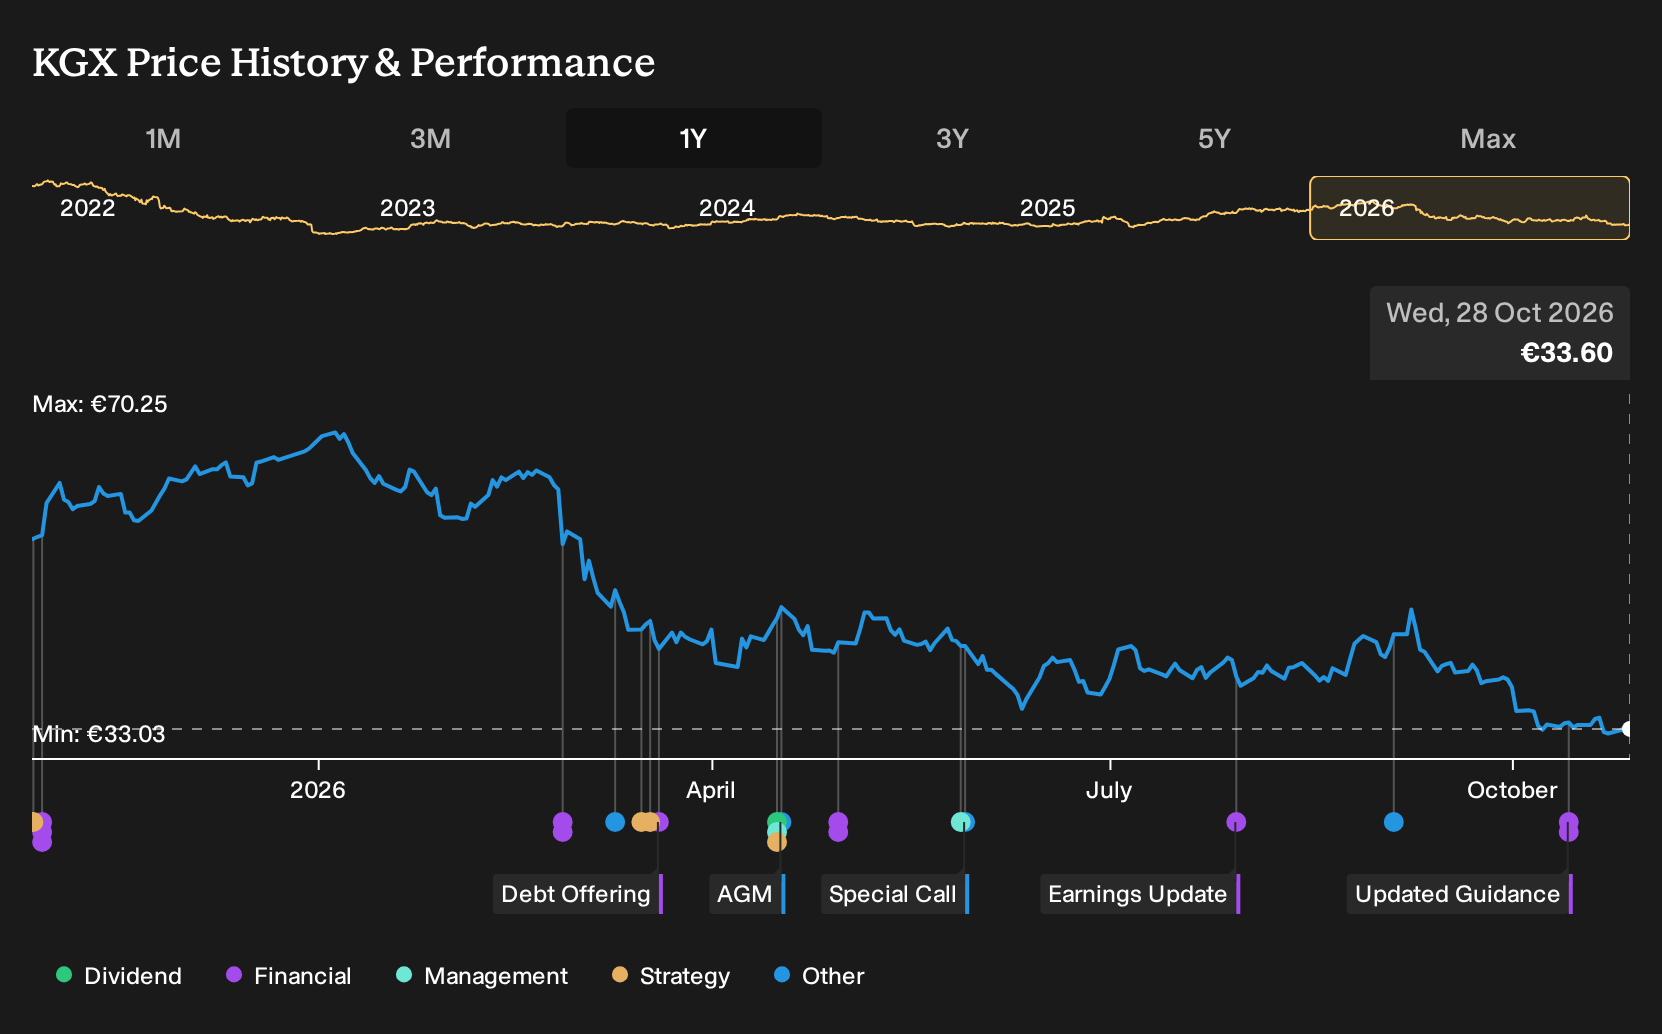
If you only glanced at the headlines on KION GROUP this year, the story looked upbeat. Order intake picked up, margins edged higher, and a new efficiency program targeted permanent cost savings. For KION GROUP shareholders, the loss over the past year was 40.6%, including dividends. If you had been weighing a fresh position in late October 2025, it might have been puzzling to see rising profitability coexist with such a heavy hit to your capital.
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
KION GROUP has already moved. Pinpoint other ways to investigate the theme among 96 robotics and automation stocks.
The Argument You Would Have Been Weighing Up On KION GROUP
The shares cost €57.1 at the start of the period, and KION GROUP sat between two very different stories about where the business could head next.
On the bullish side, the €67 Fair Value rested on Asia-Pacific expansion and NVIDIA-backed physical AI. Supporters leaned on assumptions that revenue could grow 6.5% a year with profit margins reaching 6.5% and earnings of €882.4 million by 2028.
The bearish camp pointed to a €36 Fair Value and worried more about deglobalization, European exposure, and tech rivals. That view still assumed revenue growth of 2.4% and margins lifting to 5.9%, yet flagged protectionism and rapid automation advances as key threats.
What The Evidence Did To The KION GROUP Argument
The clearest test came from Q2 2026, when KION GROUP reported revenue of €2,915.9m and net income of €112.2m, with net margin at 3.8%. That outcome sat closer to the optimistic case on profitability, although the later cut to the 2026 outlook and delayed margin targets supported the cautious scenario. Overall, the evidence cut both ways.
The lesson is simple. When a thesis leans on margin upgrades, track the reported net margin and any timing shifts in formal targets, rather than focusing only on headline growth or new AI partnerships.
What You Would Be Paying For In KION GROUP Today
At a share price of €33.6, KION GROUP is assessed in the selected Narrative as trading below its Fair Value, with that gap tied to expectations for automation recovery and cost efficiencies.
The crux is whether warehouse automation orders and the efficiency program really can offset softer industrial truck conditions and execution risk for a buyer today.
"The 2025–26 efficiency program, expected to deliver around €140–150 million of sustainable annual cost savings from 2026 onwards with lower one off expenses than first planned, offers a clear internal lever for higher adjusted EBIT margins and more resilient net margins."
One Narrative disagrees with today's price. → See where this Narrative says KION GROUP should trade
How Could You Get There Earlier?
Passing on this one could have spared you a loss. Where might you find the opposite surprise? Start looking for companies whose prices leave room for a better outcome than investors expect. These three trade below our estimated value.
- Company 1 - 36% below our estimate - serves a growing backlog of onshore wind projects that lock in long-term service contracts.
- Company 2 - 43% below our estimate - benefits as larger LED display orders and transportation projects feed into a swelling backlog.
- Company 3 - 23% below our estimate - supplies photonic solutions as semiconductor and biophotonics customers prepare fresh capacity ramps.
Those are three of them. See all 192 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com