
Does Strong Quarterly Earnings Change The Bull Case For Knight Swift Stock (KNX)?
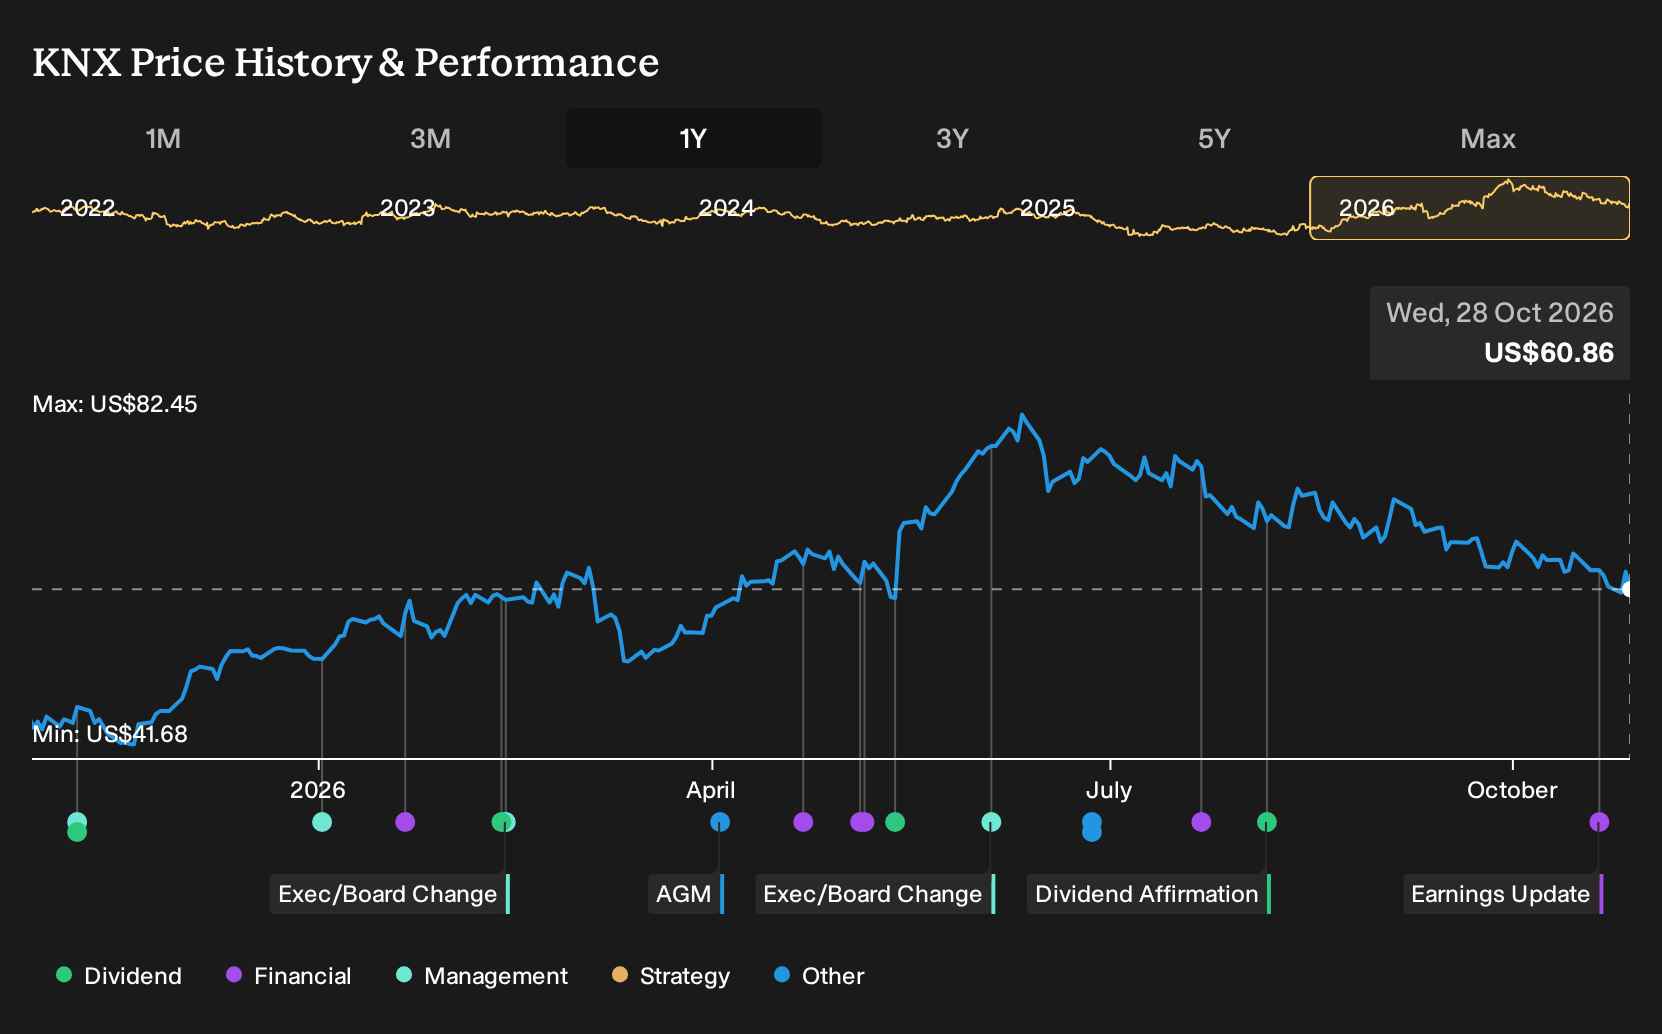
- Knight-Swift Transportation Holdings reported past third quarter 2026 revenue of US$2,200.93 million and net income of US$118.27 million, with basic EPS from continuing operations of US$0.73.
- The stronger year-to-date earnings, with nine month net income of US$160.14 million, highlight how profitability improved even on relatively modest sales growth.
- The key question for investors is how Knight-Swift Transportation Holdings' stronger net income and earnings profile fits into its existing investment narrative.
Scan how Knight-Swift Transportation Holdings' earnings story compares with other potential value ideas by checking the hand picked 26 high quality undervalued stocks in similar fundamental territory.
Knight-Swift Transportation Holdings Investment Narrative Recap
Owning Knight-Swift Transportation Holdings means believing the freight cycle and the mix shift into LTL, logistics and intermodal can make current earnings power more repeatable. The sharp step up in Q3 2026 net income and EPS shows what the business can earn when operations run cleaner. The near term swing factor remains how quickly the LTL network fills and integrates without eroding the operating ratio.
The biggest near term risk still sits in weak freight volumes and cost pressure from insurance and logistics carriers. The latest quarter does not fully remove that concern. Freight softness, higher third party capacity costs and any slowdown in cost savings or tech execution could again weigh on margins if demand stumbles.
The most relevant fresh data point is the Q3 2026 report itself. Knight-Swift Transportation Holdings booked US$2,200.93 million of quarterly revenue and US$118.27 million of net income, with basic EPS from continuing operations at US$0.73. For the first nine months of 2026, revenue reached US$6,146.86 million and net income came in at US$160.14 million, giving investors a clearer view of current earning capacity.
Those results plug directly into the existing catalysts. LTL expansion, intermodal growth and cost and routing technology all matter more when profitability is already visible in the numbers. On the flip side, the options market has recently priced in high implied volatility, which underlines that execution on integration, freight pricing and insurance costs remains central to how the next leg of the Knight-Swift story plays out.
Knight-Swift Transportation Holdings' current earnings of US$42.9 million are set against analyst forecasts that call for US$9.8b in revenue and US$746.2 million in earnings by 2029. This implies revenue growth of 8.1% per year and an earnings increase of about US$703 million from today.
Uncover why Knight-Swift Transportation Holdings' fair value indicates a 40% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
For Knight-Swift Transportation Holdings, the most optimistic analysts focus on the intermodal segment as a possible upside swing factor. They were already penciling in about US$10.6b of revenue and US$1.1b of earnings by 2029, well above the consensus US$9.8b and US$746.2 million. Those forecasts were set before this latest earnings release, so treat them as starting points and compare several viewpoints before forming your own view on what might change next.
Explore 3 other Knight-Swift Transportation Holdings fair value estimates, including one that suggests as much as 108% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research and forming independent views.
- A useful starting point for your Knight-Swift Transportation Holdings research is our analysis highlighting 4 key rewards that could inform your investment decision.
- See our latest analysis for Knight-Swift Transportation Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Knight-Swift Transportation Holdings' overall financial profile at a glance.
Looking For More Investment Ideas Beyond Knight-Swift Transportation Holdings?
If the Knight-Swift Transportation Holdings story has sharpened your thinking about earnings quality and risk, broaden that lens by scanning other opportunities that share similar fundamentals but with very different drivers.
- For investors hunting for strong balance sheets and resilient business models, start with the list of solid balance sheet and fundamentals (24 results) to see which companies combine financial strength with cleaner fundamentals.
- If income reliability is your priority, the 6 dividend fortresses can help you focus on companies offering higher yields with an emphasis on staying power rather than short term excitement.
- Those looking for mispriced potential can use the 19 high quality undiscovered gems to surface under-followed stocks where fundamentals and current expectations may be out of sync.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com