
Porch Group (PRCH) Could Be 22% Undervalued After Q3 Profit Turnaround
Porch Group (PRCH) just put fresh Q3 2026 numbers on the table, with higher sales, positive net income, and earnings per share figures that move out of last year’s loss territory.
The Q3 release has landed against a choppy backdrop for Porch Group’s stock, with the share price falling 7.7% over the last day and 12.3% across the week. Despite this, it still shows a 76.8% year-to-date share price gain and a very large 3-year total shareholder return, signalling momentum that has cooled in the short term but remains strong over a longer window.
Spot 19 high quality undiscovered gems that show improving profitability trends similar to Porch Group, after fresh earnings turn a prior net loss into positive income.After a one day pullback and a cooler week, Porch Group now faces a simple fork: Has most of the rerating already happened, or does the current price still leave meaningful upside on the table once you run the valuation math?
Most Popular Narrative: 22% Undervalued
At a last close of $16.30 against a narrative fair value of $20.79, Porch Group is framed as undervalued, with that gap hinging on how its insurance and software economics develop over time.
The formation of the Porch Insurance Reciprocal Exchange (PIRE) and the sale of Homeowners of America (HOA) Insurance Carrier into PIRE create a more predictable and higher-margin financial model, which could lead to improved earnings.
The company is investing in expanding its Vertical Software and data businesses, with initiatives such as new product launches and increased sales and product investments poised to drive faster revenue growth in 2026 and beyond.
See why 7 investors see Porch Group as 22% undervalued.
Result: Fair Value of $20.79 (UNDERVALUED)
Still, the narrative can break if Porch Group’s fee based insurance transition drags on execution, or if revenue volatility like the Q4 2024 decline reappears.
Find out about the key risks to this Porch Group narrative.
Another View: Porch Group On Simple Sales Metrics
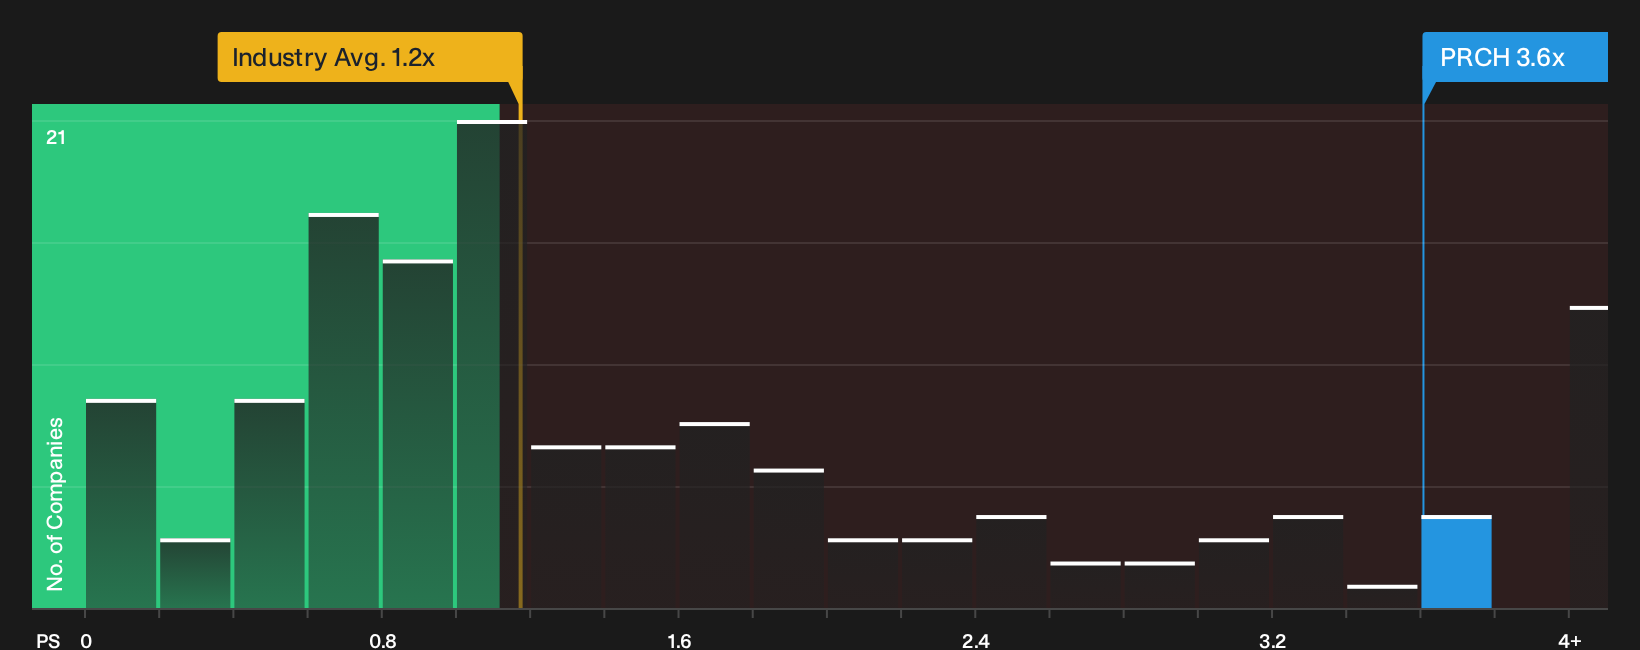
On a plain P/S lens, Porch Group looks expensive. The shares trade at about 3.6x sales, compared with 1.2x for the wider US Insurance group and 0.8x for direct peers. The fair ratio from regression work sits closer to 1.9x.
That gap points to meaningful valuation risk if sentiment cools or if revenue and margin progress disappoints. It also means any future upside already asks a lot of the business. The real question is whether you believe Porch Group can grow into that richer P/S multiple before the market leans back toward the fair ratio.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on Porch Group so far, with fresh profitability on one side and valuation questions on the other, mean you will want to look at the underlying data yourself and decide where you land. To weigh both the upside arguments and the caution flags in one place, start with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Porch Group?
Do not stop your research with Porch Group when a wider universe of potential opportunities is only a few clicks away on the Simply Wall St screener.
- Target resilience by focusing on companies that historically pair steadier fundamentals with fewer red flags using the 32 resilient stocks with low risk scores.
- Hunt for quality at a reasonable price and see which stocks screen as potential value candidates through the 26 high quality undervalued stocks.
- Build an income focused watchlist by lining up companies that offer meaningful yields using the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com