
Antero Resources (AR) Moves To Intervene In Key FERC Gas Transport Case
- Antero Resources (NYSE:AR) has moved to intervene in a Federal Energy Regulatory Commission proceeding on interstate gas transportation agreements.
- The filing seeks party status in a case involving Tennessee Gas Pipeline and Mex Gas Supply, tied to moving Antero's natural gas.
- The FERC proceeding centers on proposed amendments that could influence terms and costs for transporting Antero's production to downstream markets.
- Antero's decision to intervene in the FERC transportation amendments deserves weighing alongside the rest of the investment picture. We have also flagged 4 other big wins for Antero Resources.
This type of regulatory jostling over pipeline and transport access highlights a broader energy infrastructure theme that investors may want to explore through 43 power grid technology and infrastructure stocks.
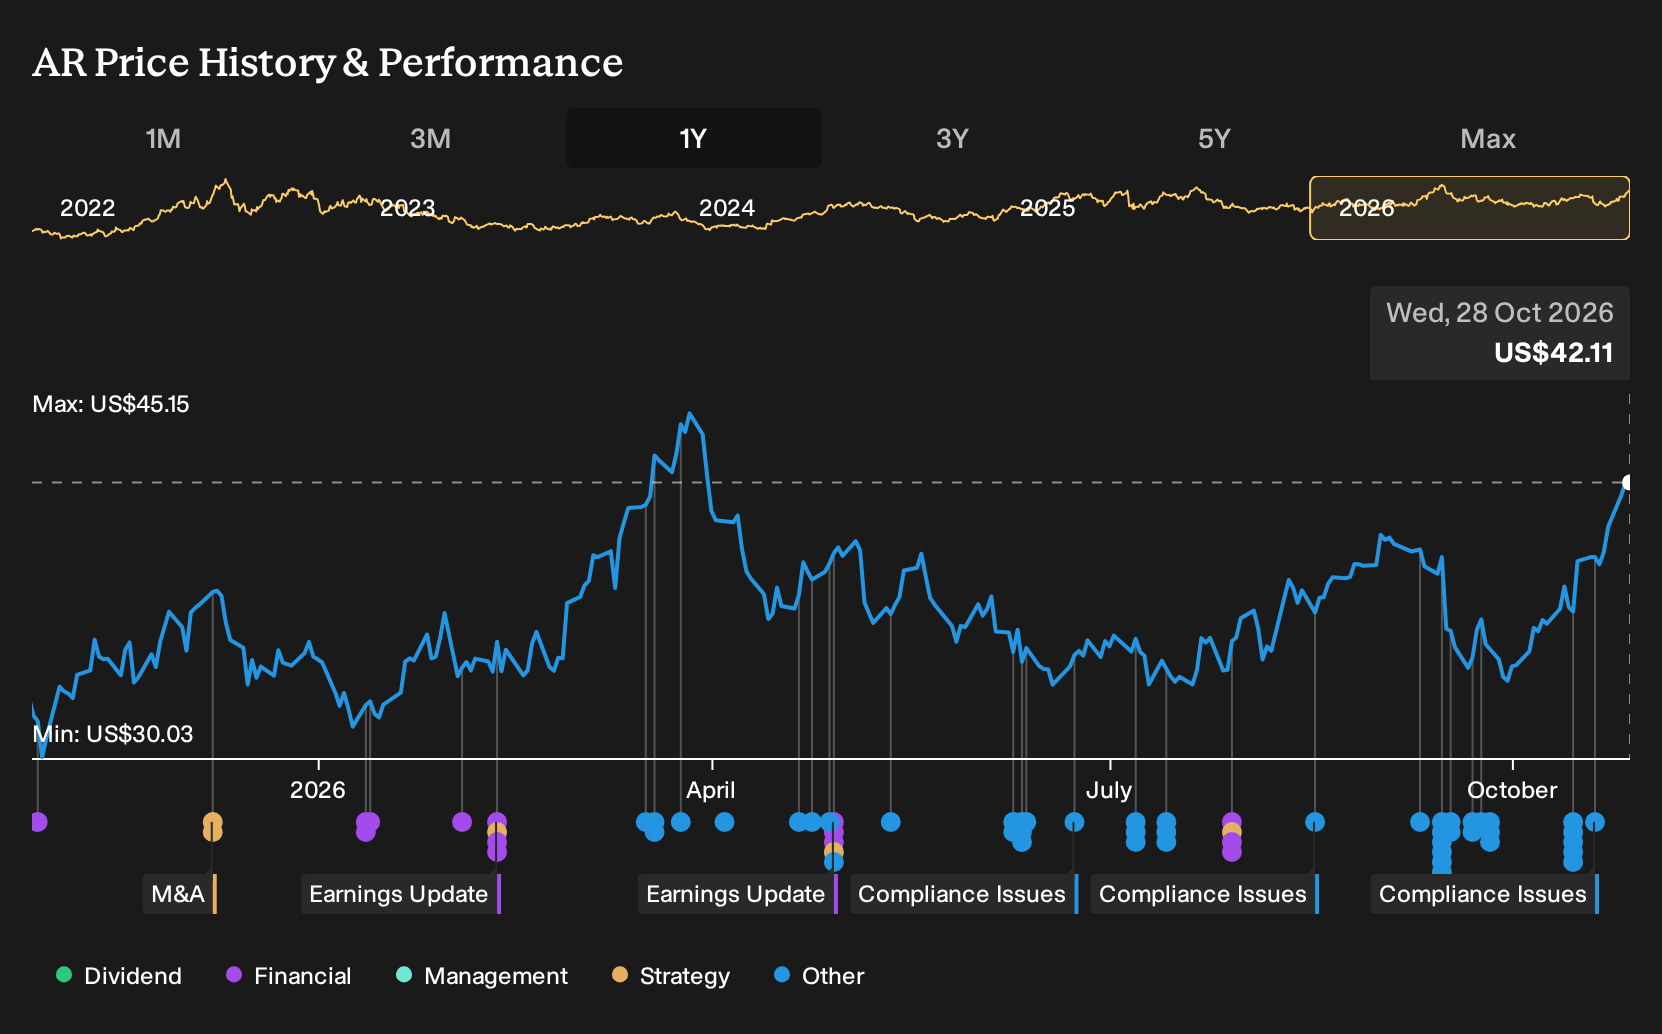
Antero Resources is a US based independent oil and gas producer focused on developing and acquiring natural gas, NGLs, and oil properties, so consistent pipeline access is central to how its output reaches end markets. For a business with a market cap of about $12.9b, the terms of interstate transport agreements can shape how reliably its production connects to buyers over time.
See how Antero Resources's balance sheet measures up.
Antero Resources’ FERC move through the lens of its export-and-cost Narrative
The central bet in the Antero Resources Narrative is that export linked pricing and lower cash costs will support margins and cash generation over time, and that firm transport is the bridge that connects those two levers.
"Antero Resources focus on liquids rich production combined with firm transport to premium Gulf Coast and export outlets is now complemented by a detailed plan to cut total cash costs by over 25% to about US$2.00 per Mcfe by year end 2028...
See how the full story points towards a $50.19 fair value for Antero Resources.
The motion to intervene at FERC goes straight to that firm-transport pillar. By trying to secure a direct voice in how an existing Tennessee Gas agreement is amended, Antero Resources is working to protect the pipeline access that underpins its export linked thesis while it runs with higher third quarter volumes and earnings. For a producer competing with peers such as EQT and Range Resources, keeping clarity on tariff terms and non standard provisions helps limit surprises in delivered costs.
This same filing also pressures the cost reduction catalyst in the Narrative. If the outcome raises transport charges or adds constraints around how Antero Resources can move gas toward premium Mexico or Gulf Coast outlets, the targeted cut in total cash costs to about US$2.00 per Mcfe becomes harder to achieve on schedule. Analysts have already flagged that past margin pressures are a risk, so any less favorable tariff outcome would lean toward the cautious side of that story.
The regulatory step can therefore be read in two ways: as a positive attempt to lock in the export-and-cost Narrative, or as a warning sign on transport risk, depending on which version of Antero Resources’ story investors focus on.
Add Antero Resources to your Watchlist and get alerts as these catalysts play out.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com