
Will Inconclusive Election Results Change Phoenix Financial Shares Narrative
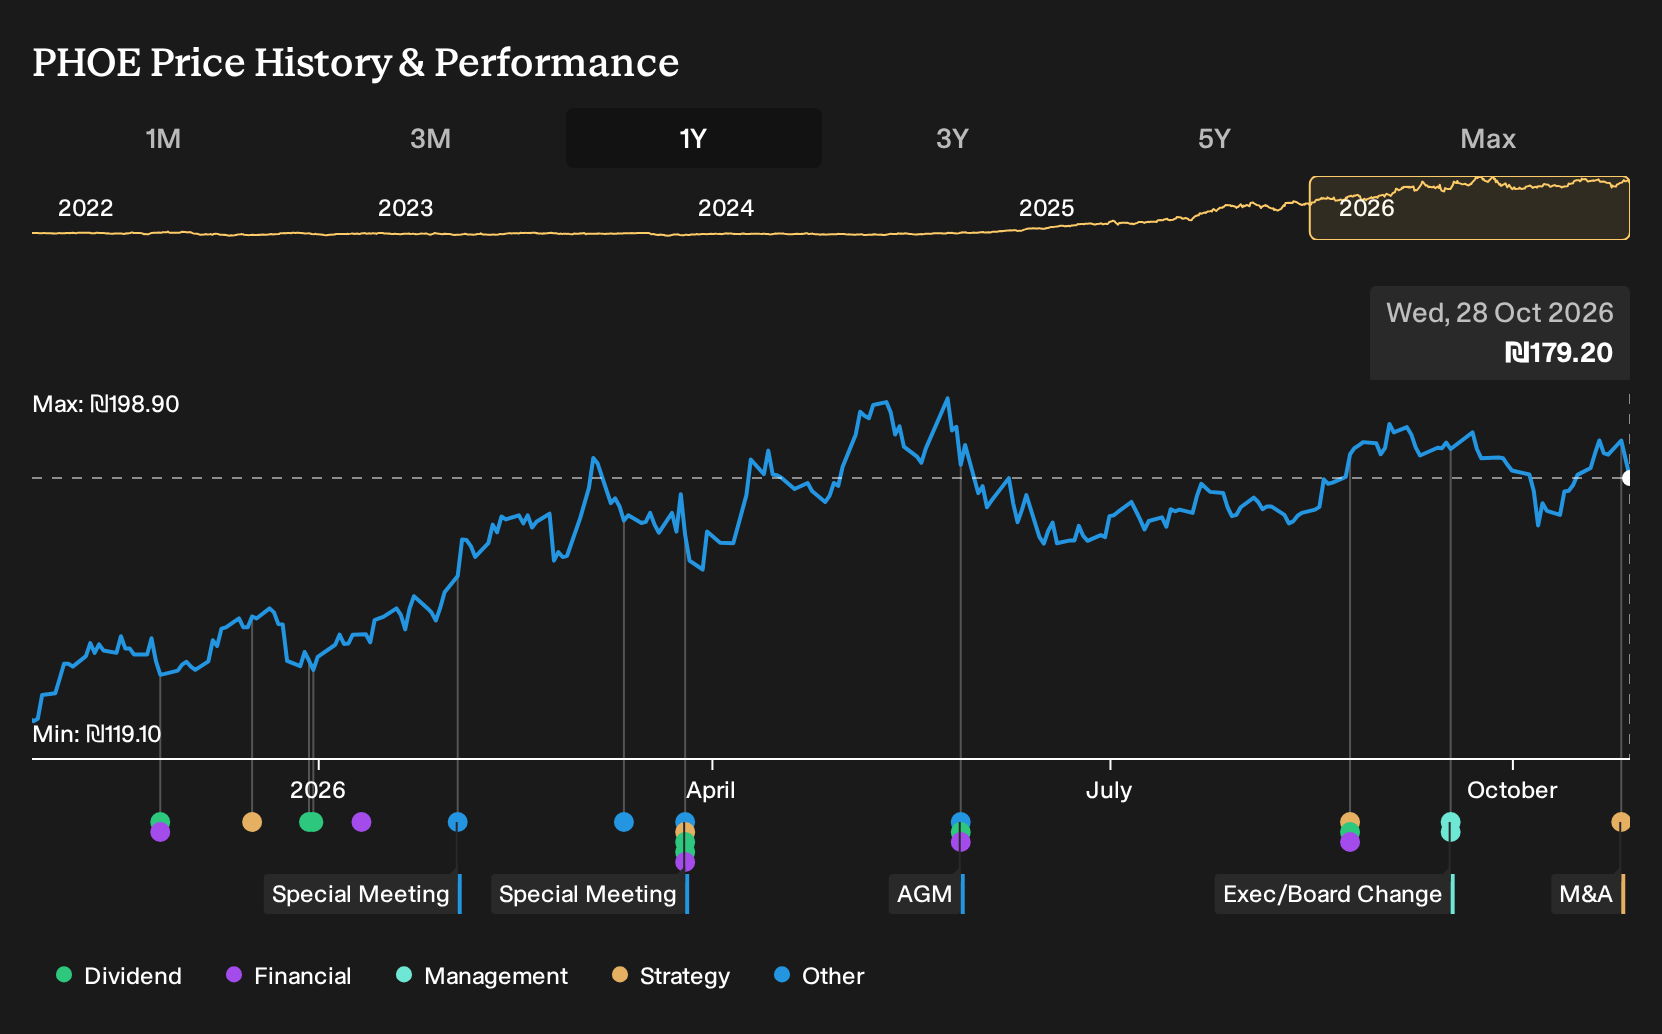
- Phoenix Financial shares moved lower after the recent inconclusive Knesset election, as the Tel Aviv Stock Exchange broadly weakened and selling pressure concentrated in banks and insurance peers.
- The reaction highlights how Phoenix Financial trades closely with Israel's wider financial sector, with political uncertainty weighing on sentiment toward balance sheet risk and capital-intensive business models.
- We will now look at how Phoenix Financial's investment narrative is affected by this sector-wide, election-driven sell-off in financials.
Stress test your exposure to Israel's financial sector by comparing Phoenix Financial with a curated 229 resilient stocks with low risk scores that have historically kept balance sheet risk in tighter focus than the broader market.
What Is Phoenix Financial's Investment Narrative?
To own Phoenix Financial, you need to believe in a diversified Israeli financial platform that earns its keep across insurance, pensions, asset management, payments, and credit rather than through a single profit engine. That is an operational story about underwriting discipline, fee income resilience, and capital management in a balance sheet heavy model. The inconclusive Knesset election and the nearly 5% drop in the shares are mostly about risk appetite for Israeli financials as a group, not about an abrupt change in Phoenix Financial's product demand or pricing power.
The real swing factors sit in execution. Earnings quality is flagged as high, yet profit growth has recently been slower than its own 5 year pace and margin sits at 16% compared with 17.5% a year earlier. Funding is entirely from higher risk sources and the P/E of 13.6x screens above some peer and industry averages, even if it remains below the wider IL market. Board refresh, a new corporate name and an unstable dividend pattern add moving parts to oversight and capital returns. The post election sector sell off simply shines a brighter light on those existing pressure points rather than creating new ones.
Even so, anyone looking closely at Phoenix Financial still has to weigh one awkward complication that rarely shows up in headline numbers...
There's only one way to know the right time to buy, sell or hold Phoenix Financial. Head to Simply Wall St's company report for the latest analysis of Phoenix Financial's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community sit between ₪163.15 and ₪215, which already shows how far opinions on Phoenix Financial can stretch. These views were formed before the post election sell off in Israeli financials, so you are effectively layering fresh political risk on top of pre existing valuation debates.
Explore another Phoenix Financial fair value estimate, including one that suggests potential upside of as much as 20% from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Phoenix Financial research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Phoenix Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Phoenix Financial's overall financial health at a glance.
Looking For More Investment Ideas Beyond Phoenix Financial?
If the Phoenix Financial story has you reassessing your exposure, it can help to set it against a wider watchlist built around clear, data backed filters rather than headlines alone.
- For investors who care most about resilient balance sheets and steady fundamentals, a list of solid balance sheet and fundamentals (202 results) can help you focus on businesses that prioritize financial strength.
- If you are hunting for quality at a reasonable entry point, use a 190 high quality undervalued stocks to surface companies where fundamentals and pricing may be out of sync.
- Income focused readers who want cash returns as part of their thesis can scan a 225 dividend fortresses to spot higher yielding options that might complement Phoenix Financial in a portfolio.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com