
Teradyne (TER) Posted Record Q3 Results, Is The Stock Still Undervalued?
Teradyne (TER) just posted record third quarter results, with revenue of about US$1.31b and GAAP net income of US$342.4m, while issuing strong fourth quarter guidance that leans heavily on AI driven demand.
Despite the strong Q3 and upbeat Q4 outlook, Teradyne's share price has slipped about 22% over the past month and 15% over 90 days, even as its year to date share price return is roughly 51% and 1 year total shareholder return is about 77%. This points to cooling short term momentum after a powerful multi year run.
Scan other AI infrastructure plays showing similar momentum swings with our hand picked list of 54 AI infrastructure stocks while you assess where Teradyne fits in your portfolio.
Bulls see Teradyne as an AI test and robotics leader trading at a discount after a sharp pullback. Bears see a momentum story cooling quickly. Which case does the current valuation appear to support.
Most Popular Narrative: 30% Undervalued
Teradyne's most followed valuation storyline places fair value near $446, compared with the last close around $313. This frames the recent pullback as a discount rather than a reset in fundamentals.
The main thing that has to go right is Teradyne successfully expanding its role as a dual-vendor tester at large compute and hyperscaler customers, while scaling memory and robotics demand tied to AI workloads.
The current valuation implies the market is not fully pricing in this narrative. This view is that Teradyne is undervalued and that AI-driven test and robotics demand could support a higher share price over time.
See why 118 investors see Teradyne as 30% undervalued.
Result: Fair Value of $446 (UNDERVALUED)
Still, the Teradyne story can break if AI related capital spending slows, or if higher R&D and go to market costs crush the expected operating leverage.
Find out about the key risks to this Teradyne narrative.
Another View: Teradyne Through The P/E Lens
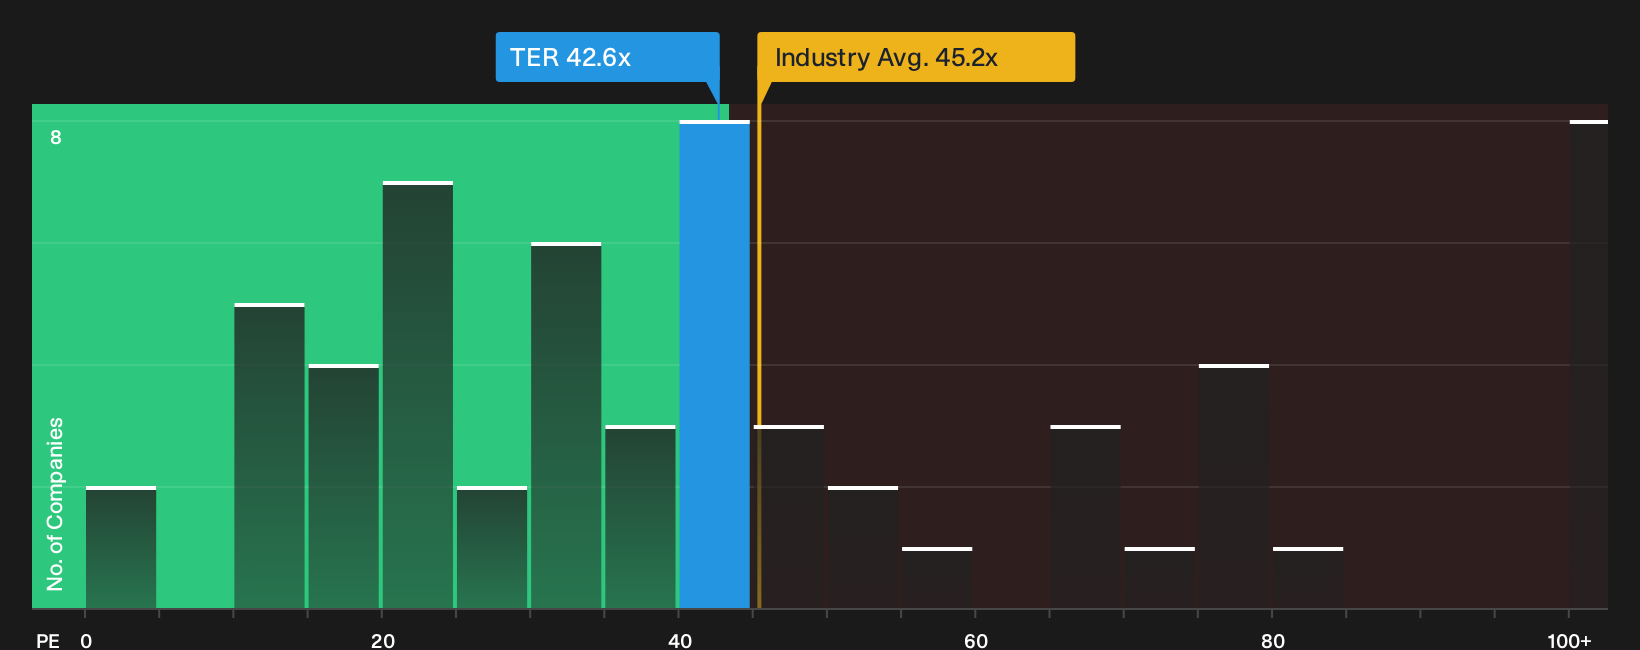
A second check on Teradyne comes from its P/E ratio. The stock trades at 42.6x earnings, which is lower than the US Semiconductor industry at 45.2x and below peer levels around 50x, yet slightly above a fair ratio estimate of 39.6x.
That mix of cheaper than sector and peers, but richer than the fair ratio, suggests a market that already prices in strong expectations while still leaving some room for upside if things go right. The question is whether you see that gap as valuation risk or a potential entry point.
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Teradyne for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 26 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the tug of war between bullish AI enthusiasm and cooling momentum feels unresolved, move quickly and test the story against the underlying numbers yourself. To weigh both the upside case and the potential weak spots in Teradyne, start by reviewing the 4 key rewards and 1 important warning sign.
Ready For More Ideas Beyond Teradyne?
Once you have an opinion on Teradyne, do not stop there. Broaden your watchlist with fresh ideas that could reshape how you allocate capital.
- Target resilient compounding potential by scanning a 6 dividend fortresses that focuses on income strength many investors overlook.
- Hunt for potential mispricing by reviewing a 19 high quality undiscovered gems that highlights quality businesses flying under most radars.
- Protect the downside first by filtering for a 32 resilient stocks with low risk scores that screens for resilient balance sheets and lower risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com