
Benchmark Electronics (BHE) Stock Looks Fully Priced After A 223% Run
Benchmark Electronics has delivered a powerful run in recent years, which puts a spotlight on whether the current share price lines up with what the business earns. With the stock now under closer scrutiny, the question is how much of that performance can be explained by its earnings profile rather than sentiment alone.
- Over the past 5 years the stock has gained 222.7%, which raises the question of whether earnings have kept pace with that kind of share price improvement.
- The business hinges on converting electronics manufacturing and engineering work into consistent profits, so the sustainability of its margins and cash generation may be central to how much earnings can support the current valuation.
- There is a second opinion on Benchmark Electronics worth weighing. See what analysts think Benchmark Electronics's shares could be worth.
The issue now is whether Benchmark Electronics' earnings justify where the share price sits after this strong multi year performance.
If you are weighing whether Benchmark Electronics' 5 year run lines up with its earnings, it can help to compare that question across 26 high quality undervalued stocks.
Has Benchmark Electronics Run Too Far on Earnings?
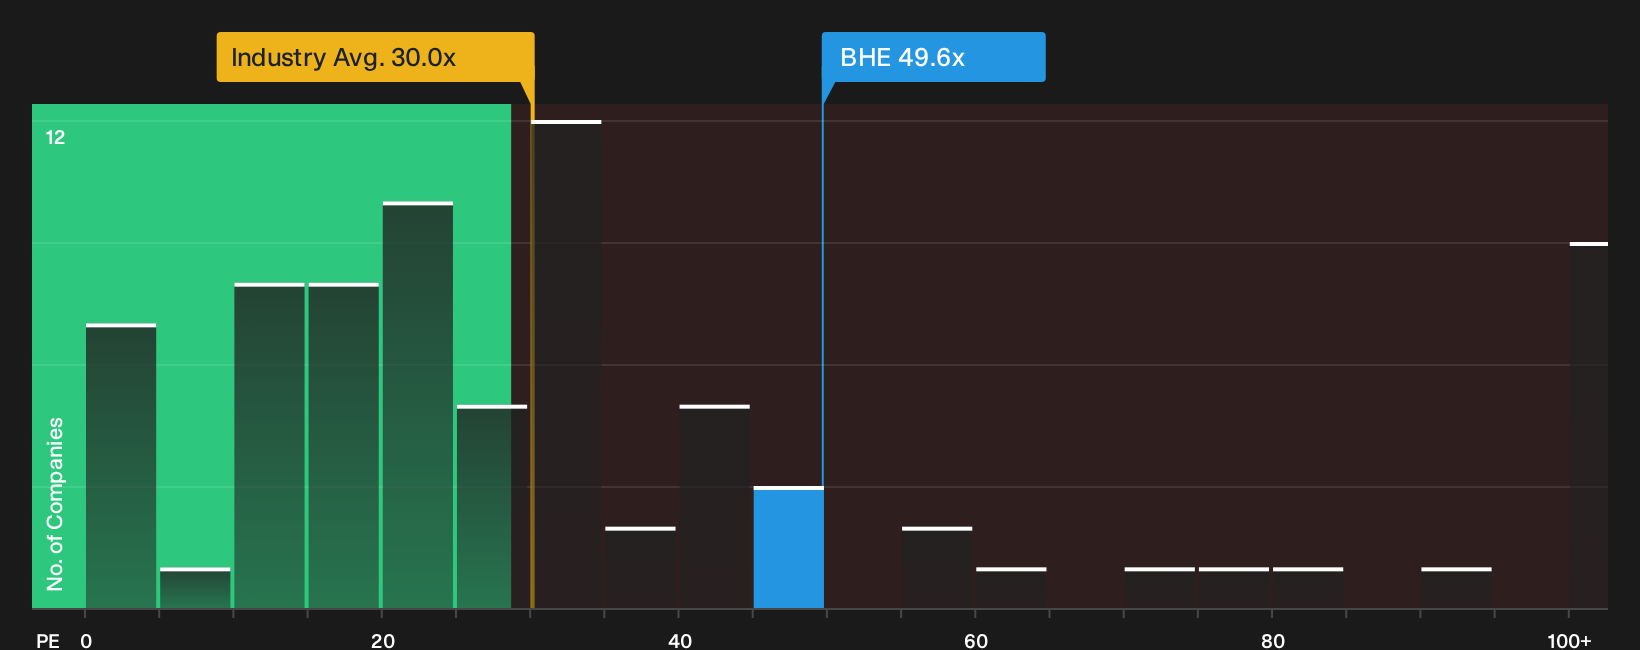
The P/E ratio is a useful lens for Benchmark Electronics because earnings still play a central role in how investors assess a contract manufacturer that can adjust with customer demand. The stock trades on about 49.6x trailing earnings, which is very close to the peer group near 49.9x and well above the wider electronic industry average around 30.0x. Taken together, these figures indicate that investors are valuing each dollar of Benchmark Electronics' profit more in line with faster growing or higher quality peers than with the broader sector.
Using a tailored view of what might typically be paid for a business with this scale, industry exposure, cash generation profile and risk mix, the current P/E appears above the level suggested by that framework, so the shares screen as overvalued on earnings alone. For anyone tracking whether the past 5 year share price run has left a margin of safety, the gap between the present multiple and this more customised reference point is an important number to examine next. Explore the numbers behind Benchmark Electronics's P/E valuation.
The Benchmark Electronics Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Benchmark Electronics pick up where the valuation puzzle leaves off and explain which expectations for future growth, profitability and earnings would need to hold for the stock to be worth meaningfully more or less than today’s price, all housed on the Community page. Rather than relying on a single P/E or model line, each narrative sets out the underlying assumptions so you can compare them with the actual results as they are reported.
One of the top community narratives on Benchmark Electronics: 15% undervalued
"The main factor that has to go right is that Benchmark Electronics converts current AI, Semi Cap and medical program ramps and capacity expansions into sustained orders..."
Discover why this Narrative puts Benchmark Electronics at 15% undervalued.
One more Benchmark Electronics check that belongs beside the price tag
All the valuation work still sits alongside a separate set of risk checks on Benchmark Electronics that point to issues worth weighing for yourself before going any further. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com