
Can Constellation Energy (CEG) Keep Earnings Valuation Reasonable After $5b Nuclear Loan?
Constellation Energy has seen its share price fall sharply this year after a strong multi year climb. That swing now puts a spotlight on whether today's valuation is still supported by its earnings power. With fresh nuclear expansion plans and long term power deals in the mix, the key issue for investors is how much of that story is already reflected in the current earnings multiple.
- Over the past 3 years the stock has gained about 129%, which raises the question of how much future earnings strength the current price is already assuming.
- A conditional US$5b loan from the Department of Energy to upgrade nuclear plants and pre sold output to large tech customers can affect Constellation Energy's earnings profile through the timing of capital spending, financing costs and contracted revenue visibility.
- Your read on Constellation Energy is one view; the desks covering it have another. See what analysts think Constellation Energy's shares could be worth.
The stock's next move may depend on whether Constellation Energy's current price is adequately backed by the earnings it is generating today.
If you want to test the same earnings question you are asking of Constellation Energy across a wider nuclear and grid build out theme, start with 15 nuclear energy infrastructure stocks.
Is Constellation Energy a Bargain on Earnings?
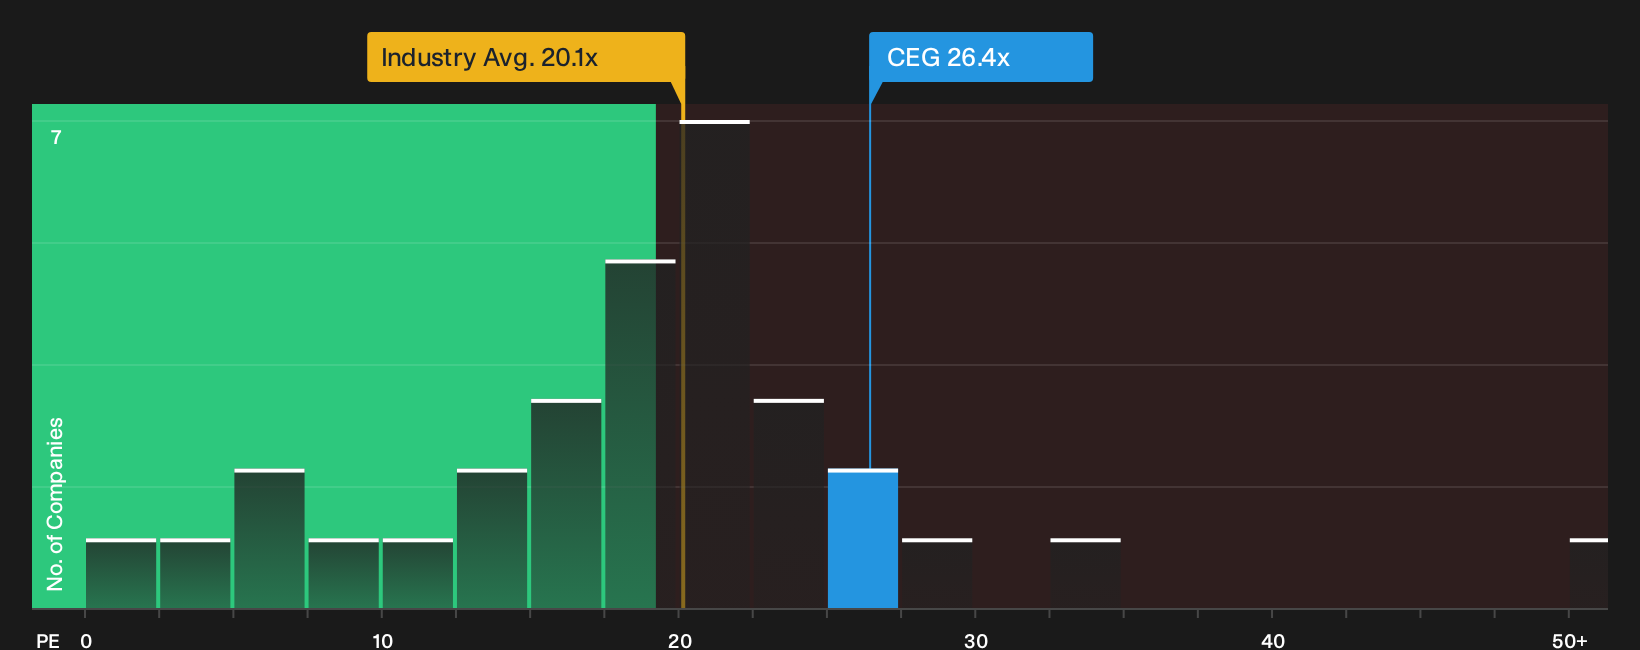
The P/E ratio suits Constellation Energy because earnings are the core way investors are weighing its nuclear and grid exposure. On this yardstick, the stock trades on about 26.4x earnings, which is higher than the Electric Utilities sector on roughly 20.1x and also above the wider peer group around 22.7x.
Because of the US$5b Department of Energy loan and long term contracts with large tech buyers, the market is paying a richer P/E than the model implied fair level. This points to Constellation Energy looking undervalued relative to what its earnings profile would typically justify on this framework. Despite that supportive backdrop, the multiple still prices the stock at a premium to the sector and peers. As a result, you are relying on the nuclear and contracted power story to keep underpinning that earnings tag. Explore the numbers behind Constellation Energy's P/E valuation.
The Constellation Energy Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle for Constellation Energy leaves off by explaining what growth, margin and earnings path would need to hold for the stock to be worth materially more or less than it is today. Each narrative links a specific fair value estimate to a clear storyline about Constellation Energy's potential catalysts and main risks, so you can later compare those expectations with how the business actually develops on the Community page.
One of the top community narratives on Constellation Energy: 24% undervalued
"Growing demand for carbon free, reliable power from large scale customers such as data centers and large corporates is now translating into roughly 920 MW of long duration nuclear power contracts..."
Discover why this Narrative puts Constellation Energy at 24% undervalued.
One more angle on Constellation Energy that could change the story
Constellation Energy's future is also shaped by who is calling the shots in the boardroom and how their pay packages line up with your interests as a shareholder. See who runs Constellation Energy and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com