
Does Earnings Growth Outlook Change The Bull Case For Eaton (ETN)?
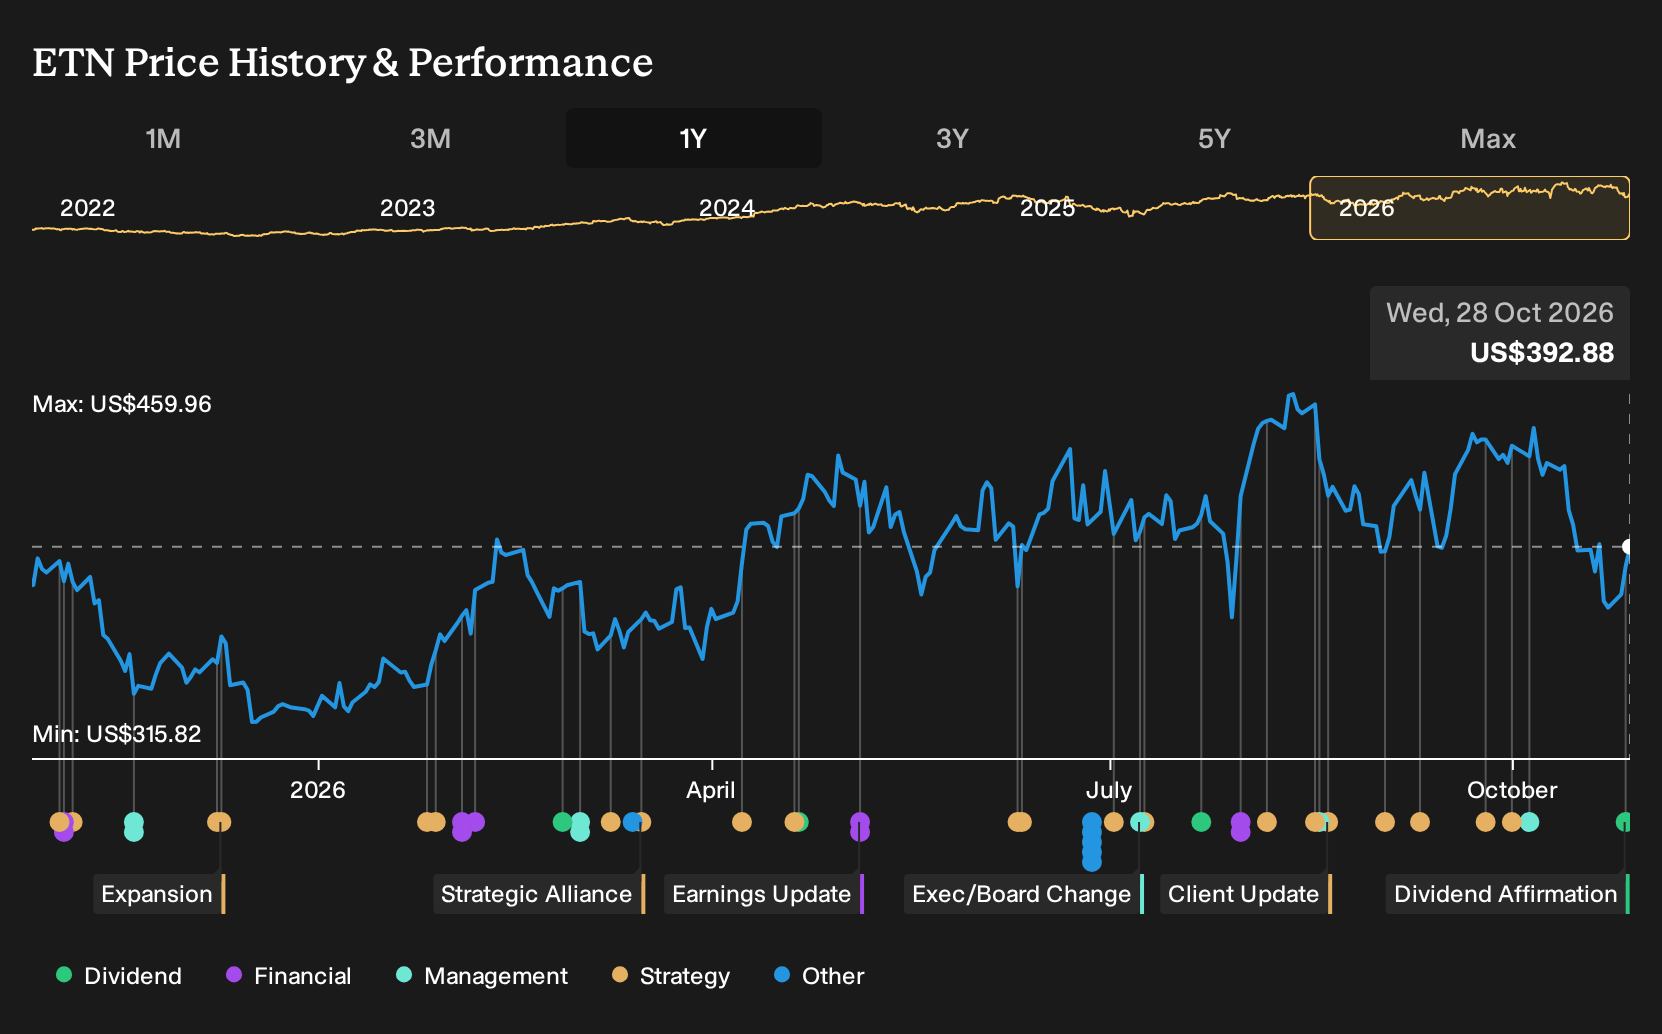
- Eaton's board declared a quarterly dividend of $1.10 per ordinary share, payable on November 27, 2026 to shareholders of record on November 10, 2026, continuing its dividend stream that has run annually since 1923.
- The dividend call lands as Eaton invests over $1b in Electrical Americas capacity and manages thinner margins and higher debt alongside acquisitions such as Boyd and Fibrebond.
- This article examines how Eaton's investment narrative is shaped by this dividend decision, earnings expectations, and recent analyst revisions.
Scan how Eaton’s latest dividend decision compares with peers by reviewing 6 dividend fortresses that balance income potential with robust underlying businesses.
Eaton Investment Narrative Recap
Eaton appeals most if you think the heavy build out in Electrical Americas, data centers and aerospace can keep supporting earnings, even as traditional vehicle and weaker geographic markets drag on results. The dividend affirmation does not change that core bet. It simply signals that management is choosing to keep returning cash while juggling thinner margins and higher debt.
The near term swing factor still sits in how cleanly Eaton ramps more than US$1b of new capacity and integrates recent deals like Boyd and Fibrebond without further pressure on profitability. The biggest risk remains a mix of elevated leverage, softer margins and investor sensitivity to any stumble in revenue or earnings delivery.
The most relevant recent piece of context for this dividend is Eaton’s capacity expansion program in Electrical Americas, where over US$1b of projects and a planned US$242m Arkansas enclosure facility are aimed at easing constraints. That build out underpins the ability to keep funding dividends from operating cash generation rather than leaning even harder on the balance sheet.
Those same projects are tightly linked to Eaton’s data center and grid to chip positioning, including liquid cooled architectures supported by Boyd and Fibrebond assets. Execution on those ramps is a key catalyst for earnings power, while any delay, cost overrun or slower than expected order conversion would magnify the existing concerns around debt levels and share price volatility during earnings disappointments.
Eaton dividend decision against analyst assumptions
Eaton's narrative projects US$43.4b revenue and US$7.5b earnings by 2029. This rests on analysts assuming 13.0% yearly revenue growth and an earnings increase of US$3.7b from US$3.8b today.
Uncover how Eaton's fair value indicates a 22% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
One alternate view on Eaton leans heavily on the data center catalyst. The most optimistic analysts were penciling in about US$46.3b of revenue and US$8.1b of earnings by 2029, versus roughly US$43.4b and US$7.5b for the baseline. Those forecasts came before this dividend move, so you may see those storylines shift.
Explore 6 other Eaton fair value estimates, including one that suggests as much as 36% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Eaton research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Eaton. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Eaton's overall financial health at a glance.
Looking for more Eaton investment ideas?
If Eaton is on your radar, it can help to line it up against other opportunities with different income, quality, and risk profiles using the Simply Wall St Screener.
- For investors who want income without ignoring balance sheet strength, scan a curated 6 dividend fortresses that aim to pair yield with business resilience.
- If you prefer to focus on quality at a reasonable price, filter for companies on our 26 high quality undervalued stocks that combine solid fundamentals with more modest valuations.
- For a more cautious starting point, narrow your watchlist to a 32 resilient stocks with low risk scores that may offer smoother returns and fewer financial red flags.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com