
Discovering Hidden Gems in Global Markets October 2026
In October 2026, global markets are experiencing a shift in dynamics as small-cap and value-oriented stocks outperform amidst concerns over AI-related spending and rising oil prices. The Russell 2000 Index's recent advance highlights the resilience of smaller companies in this volatile environment, prompting investors to consider the potential of lesser-known stocks that may thrive under current economic conditions. Identifying a good stock often involves looking for companies with strong fundamentals and growth potential, particularly those that can navigate today's challenges such as fluctuating energy costs and evolving technology investments.
Top 10 Undiscovered Gems With Strong Fundamentals Globally
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Shengda ResourcesLtd | 44.63% | 9.29% | 15.82% | ★★★★★☆ |
| Shandong Head GroupLtd | 48.27% | 6.77% | -13.52% | ★★★★★☆ |
| Xiamen King Long Motor Group | 93.39% | 11.34% | 66.65% | ★★★★★☆ |
| Fourth Milling | NA | 12.93% | 16.76% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Skue Sparebank | 122.31% | 16.16% | 27.93% | ★★★★☆☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Primo Global Holdings | 64.63% | 9.93% | 28.27% | ★★★☆☆☆ |
| HANA Micron | 137.37% | 21.15% | 26.62% | ★★★☆☆☆ |
We'll examine a selection from our screener results.
Electrolux Professional (OM:EPRO B)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Electrolux Professional AB (publ) offers food service, beverage, and laundry products and solutions to various service facilities such as restaurants, hotels, healthcare, and educational institutions with a market cap of SEK15.06 billion.
Operations: Electrolux Professional generates revenue primarily from its food service, beverage, and laundry product solutions targeted at service facilities. The company's financial performance highlights a net profit margin trend worth noting, reflecting its operational efficiency in managing costs relative to revenue generation.
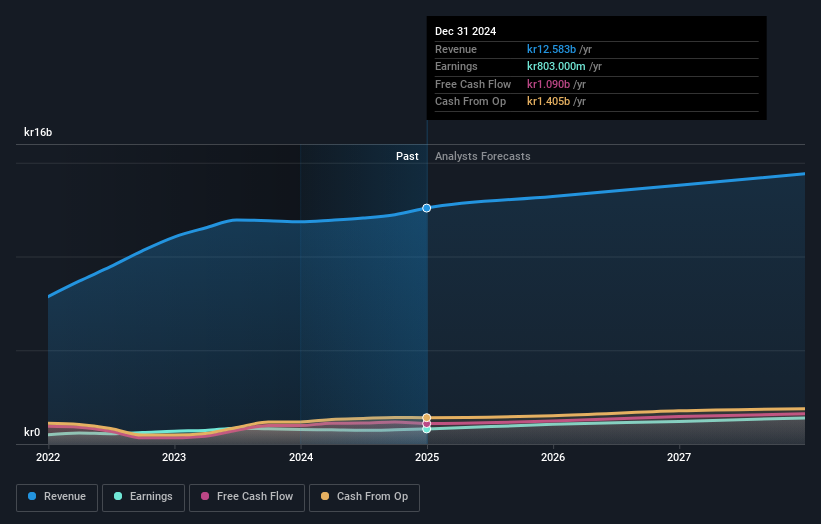
Electrolux Professional, a promising player in the machinery sector, has been making waves with its innovative strategies and solid financial performance. Recent earnings for Q3 2026 showed sales of SEK 2.95 billion, up from SEK 2.82 billion last year, while net income jumped to SEK 212 million from SEK 40 million. The company is trading at an attractive value, estimated to be about 56% below fair value. With a net debt to equity ratio of 24%, the financial health appears satisfactory. Their Generation 7000 platform highlights a commitment to sustainability and efficiency that could drive future growth despite potential currency pressures and challenges in the U.S. market.
Eastern Province Cement (SASE:3080)
Simply Wall St Value Rating: ★★★★★☆
Overview: Eastern Province Cement Company engages in the production and sale of clinker and cement products within Saudi Arabia and internationally, with a market capitalization of SAR20.23 billion.
Operations: Eastern Province Cement generates revenue through the production and sale of clinker and cement products, catering to both domestic and international markets. The company's financial performance is highlighted by a market capitalization of SAR20.23 billion.
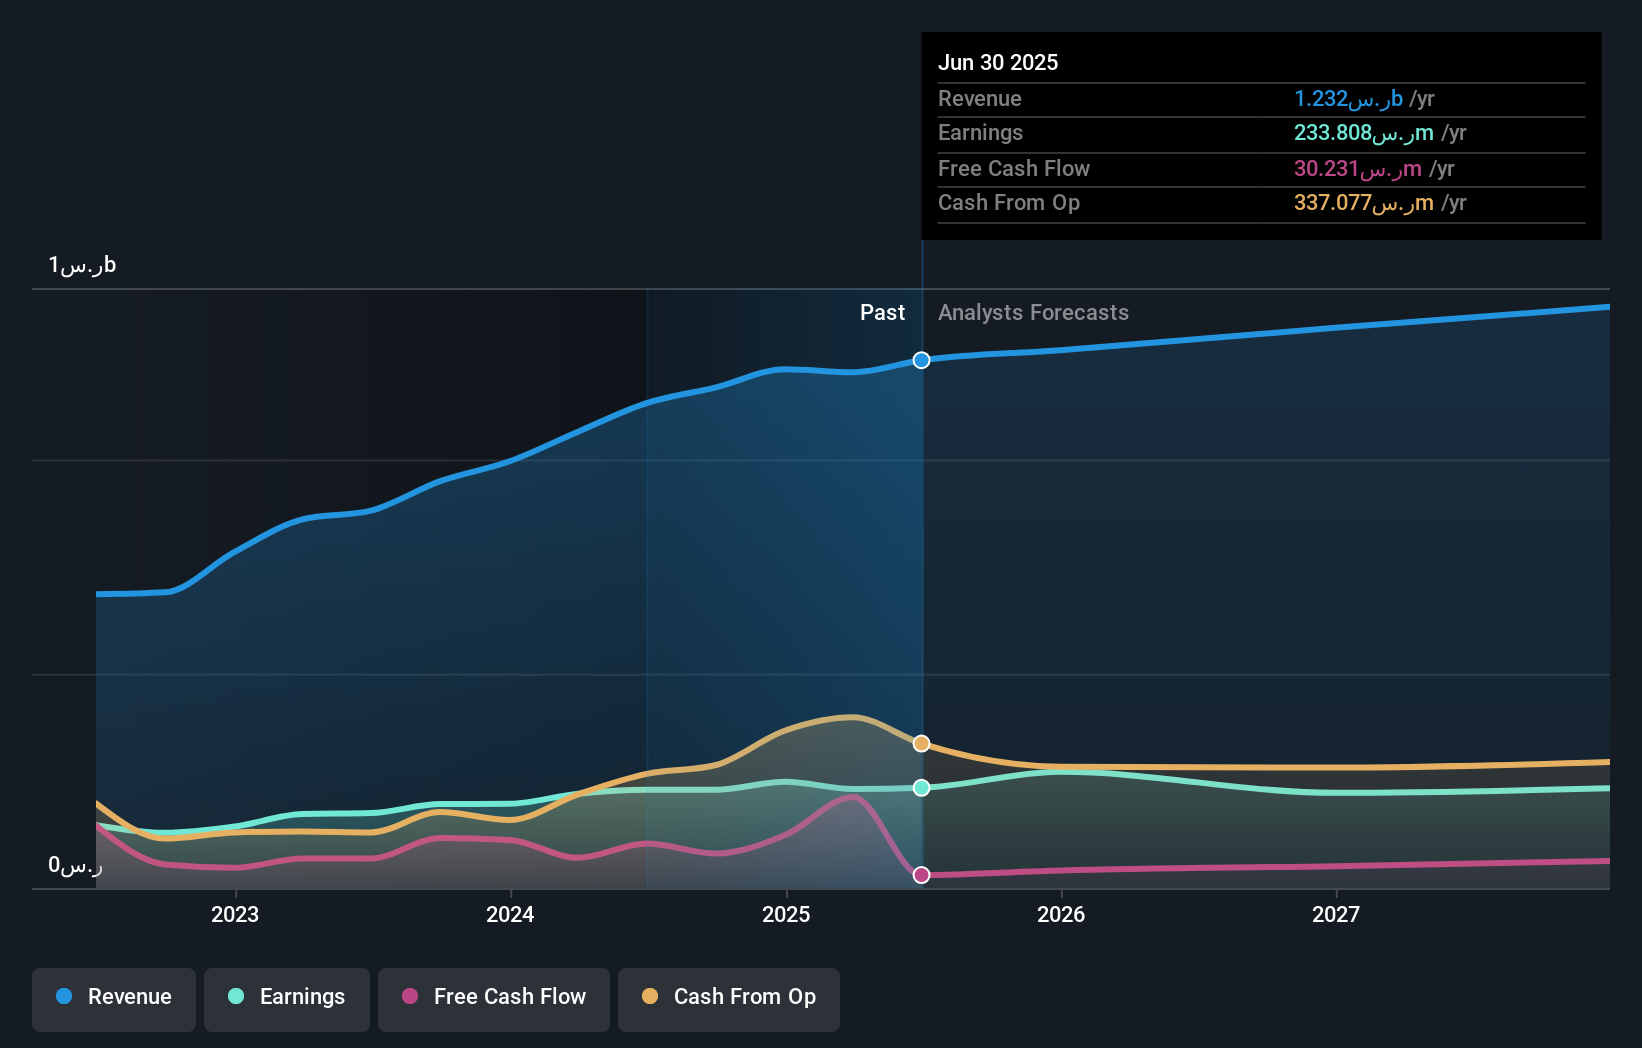
Eastern Province Cement, a relatively small player in the cement industry, has shown promising signs with its recent earnings announcement. The company reported third-quarter sales of SAR 310.26 million, up from SAR 298.64 million last year, while net income rose to SAR 50.38 million from SAR 35.66 million in the same period. Basic earnings per share increased to SAR 0.59 from SAR 0.41 a year ago, reflecting strong performance against industry trends where growth was negative at -14.8%. With a debt-to-equity ratio now at 21% over five years and trading at nearly 24% below estimated fair value, it seems well-positioned for potential growth despite not being free cash flow positive currently.
- Click here to discover the nuances of Eastern Province Cement with our detailed analytical health report.
Understand Eastern Province Cement's track record by examining our Past report.
Tokuyama (TSE:4043)
Simply Wall St Value Rating: ★★★★★☆
Overview: Tokuyama Corporation is a diversified chemical company engaged in the production and sale of various chemical products across Japan, Asia, and international markets with a market capitalization of ¥282.98 billion.
Operations: Tokuyama Corporation generates revenue primarily from its Chemical Products and Electronic & Advanced Materials segments, contributing ¥103.44 billion and ¥92.74 billion respectively. The Cement segment also plays a significant role with revenue of ¥66.85 billion, while the Life Science segment adds ¥54.98 billion to the overall sales figures.
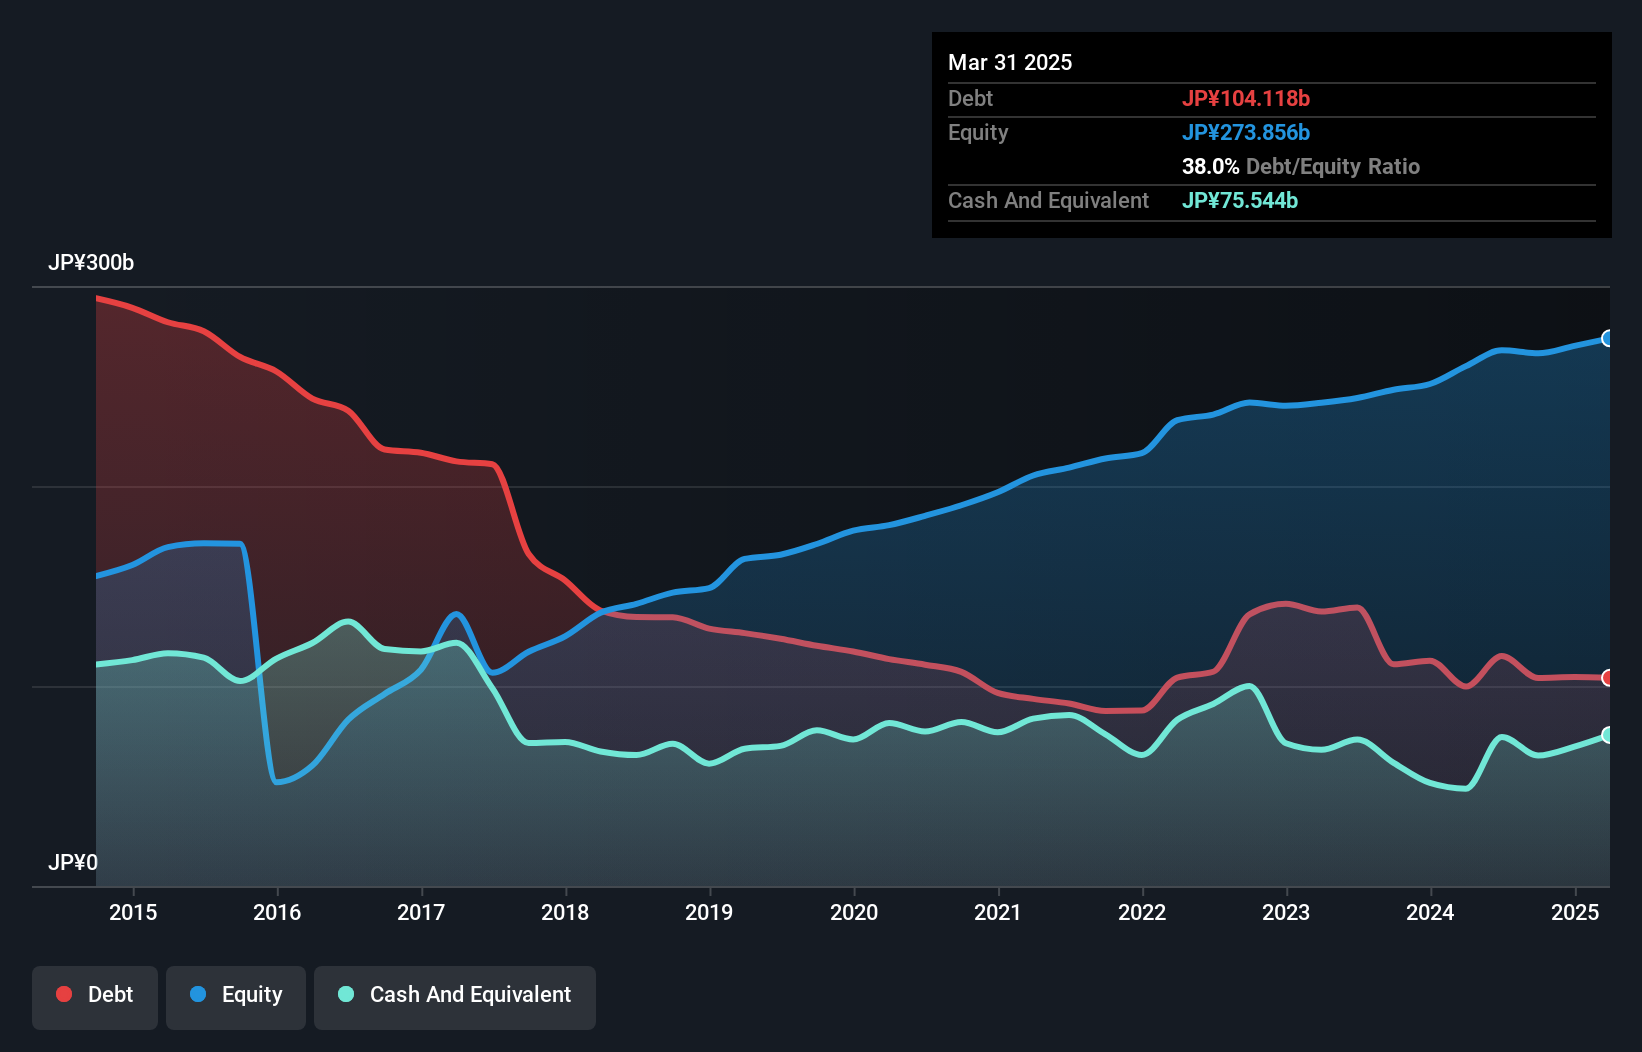
Tokuyama, a player in the chemicals sector, is trading at a significant discount of 64.1% below its estimated fair value, suggesting potential upside. Despite earnings growth of 7.7% over the past year not matching the industry's 24.4%, Tokuyama's debt management appears solid with a net debt to equity ratio of 36%, which is satisfactory by industry standards. The company's interest payments are well covered by EBIT at a coverage ratio of 68x, indicating strong financial health. Recent board discussions about mergers could signal strategic moves for future growth and expansion within its niche market space.
- Navigate through the intricacies of Tokuyama with our comprehensive health report here.
Review our historical performance report to gain insights into Tokuyama's's past performance.
Seize The Opportunity
- Investigate our full lineup of 184 Global Undiscovered Gems With Strong Fundamentals right here.
- Got skin in the game with these stocks? Elevate how you manage them by using Simply Wall St's portfolio, where intuitive tools await to help optimize your investment outcomes.
- Maximize your investment potential with Simply Wall St, the comprehensive app that offers global market insights for free.
Curious About Other Options?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com