
3 Global Growth Companies With High Insider Ownership And 35% Revenue Growth
In recent weeks, global markets have experienced volatility driven by concerns over AI investment and rising oil prices, with small-cap and value-oriented stocks outperforming their larger counterparts. Amid this backdrop of fluctuating indices and shifting market leadership, growth companies with high insider ownership can offer unique insights into potential resilience and alignment of interests between management and shareholders.
Top 10 Growth Companies With High Insider Ownership Globally
| Name | Insider Ownership | Earnings Growth |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.4% | 75.1% |
| Pharma Mar (BME:PHM) | 12.1% | 39.9% |
| KebNi (OM:KEBNI B) | 13.1% | 110.7% |
| KCTech (KOSE:A281820) | 20.6% | 31.6% |
| Guangdong Shenling Environmental Systems (SZSE:301018) | 36.7% | 65.4% |
| Gpixel Changchun Microelectronics (SEHK:3277) | 18.2% | 32% |
| Gold Road International (OB:GOLDR) | 36.7% | 89.8% |
| Fulin Precision (SZSE:300432) | 11.7% | 67.4% |
| Biocytogen Pharmaceuticals (Beijing) (SEHK:2315) | 14.1% | 39.2% |
| Beijing Luzhu Biotechnology (SEHK:2480) | 39.7% | 84.3% |
Let's uncover some gems from our specialized screener.
TES (KOSDAQ:A095610)
Simply Wall St Growth Rating: ★★★★★★
Overview: TES Co., Ltd. is engaged in the manufacturing and sale of semiconductors, displays, and compound semiconductor equipment, with a market cap of ₩2.19 trillion.
Operations: The company's revenue primarily comes from its semiconductor manufacturing equipment segment, which generated ₩405.47 billion.
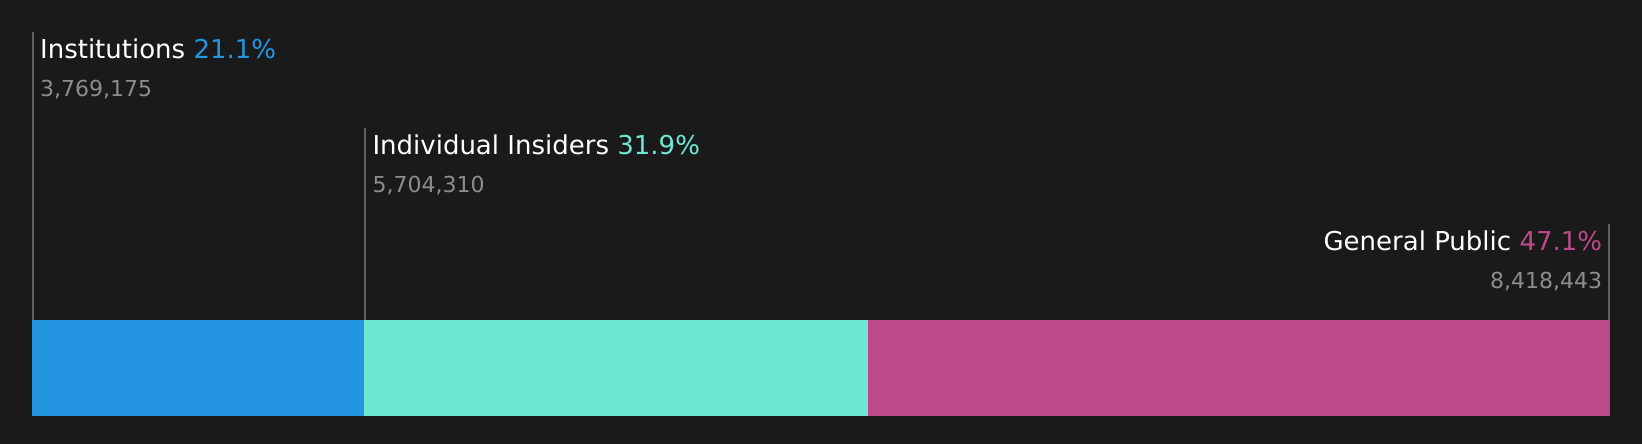
Insider Ownership: 31%
Revenue Growth Forecast: 22.9% p.a.
TES Co., Ltd demonstrates strong growth potential with earnings forecasted to increase by 31.1% annually, outpacing the Korean market's 28.8%. Despite recent volatility in its share price, TES is trading at 15.9% below its estimated fair value, suggesting potential for appreciation. The company reported substantial net income growth in recent earnings despite negligible sales figures, highlighting profitability improvements. Revenue is also expected to grow significantly faster than the market average at 22.9% annually.
- Unlock comprehensive insights into our analysis of TES stock in this growth report.
- The valuation report we've compiled suggests that TES' current price could be quite moderate.
HANMI Semiconductor (KOSE:A042700)
Simply Wall St Growth Rating: ★★★★★★
Overview: HANMI Semiconductor Co., Ltd. manufactures and sells semiconductor equipment both in South Korea and internationally, with a market cap of approximately ₩19.30 trillion.
Operations: The company generates revenue of approximately ₩551.31 billion from its semiconductor equipment segment.
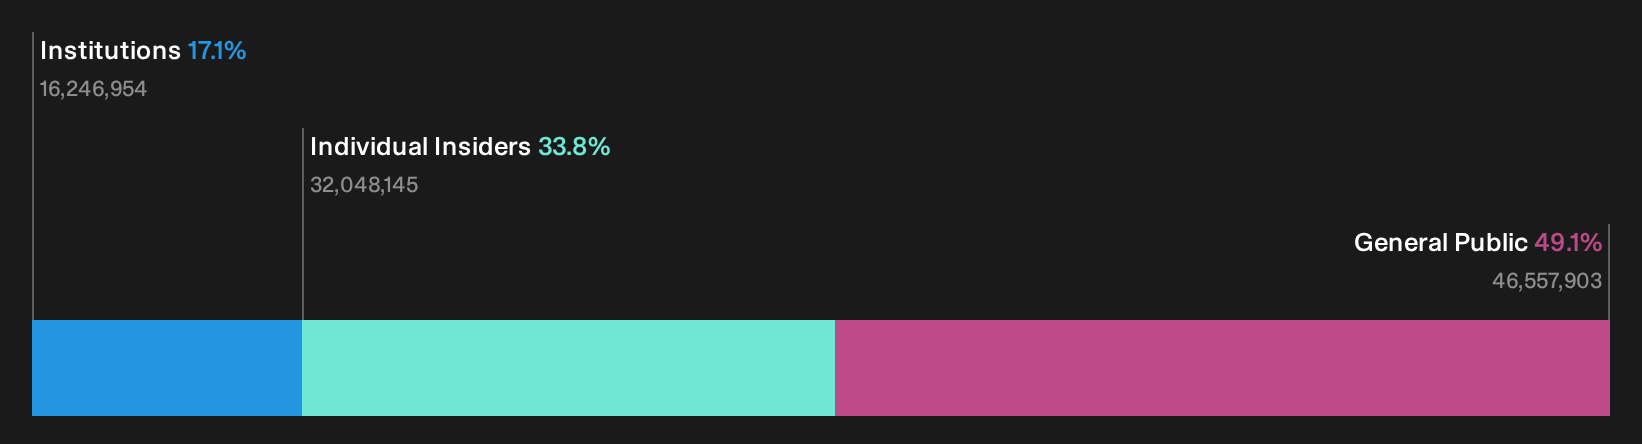
Insider Ownership: 33.8%
Revenue Growth Forecast: 35.3% p.a.
HANMI Semiconductor is experiencing substantial growth, with earnings projected to rise 35.7% annually, outpacing the Korean market's 28.8%. Revenue is expected to grow at a robust 35.3% per year, driven by increased demand in AI system semiconductors and expansion into the U.S. market via HANMI USA. Despite recent share price volatility, the company reported significant net income growth in Q2 2026, underscoring its profitability amid strategic market expansions and high insider ownership stability.
- Click to explore a detailed breakdown of our findings in HANMI Semiconductor's earnings growth report.
- The valuation report we've compiled suggests that HANMI Semiconductor's current price could be inflated.
Micronics Japan (TSE:6871)
Simply Wall St Growth Rating: ★★★★★★
Overview: Micronics Japan Co., Ltd. develops, manufactures, and sells body measuring equipment as well as semiconductor and liquid crystal display inspection equipment globally, with a market cap of ¥479.60 billion.
Operations: The company's revenue is derived from two main segments: TE Business, contributing ¥1.39 billion, and Probe Card Business, generating ¥84.87 billion.
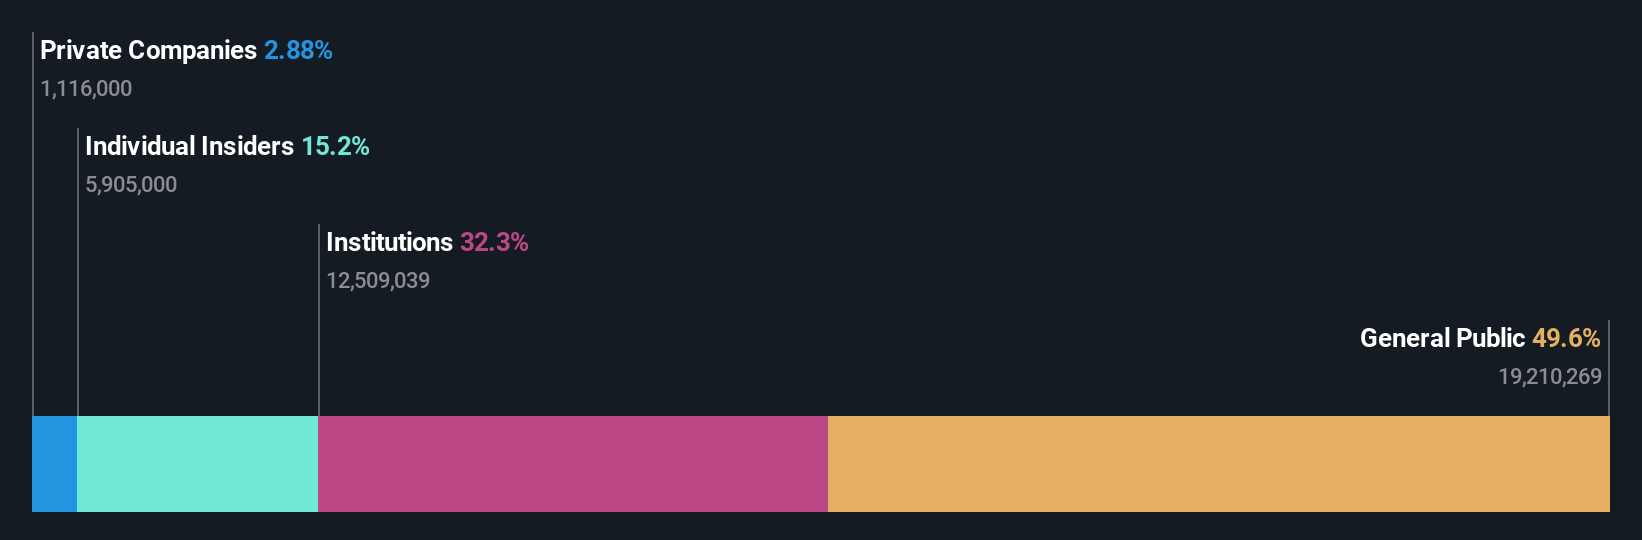
Insider Ownership: 15.3%
Revenue Growth Forecast: 23% p.a.
Micronics Japan is set for substantial growth, with earnings forecast to increase 24.9% annually, surpassing the JP market's 9.6%. Revenue is expected to grow at 23% per year, driven by rising demand for memory semiconductor probe cards. Recent additions to the FTSE All-World Index and revised earnings guidance highlight its strong performance trajectory. Despite recent share price volatility, insider ownership remains stable, reflecting confidence in its strategic expansion amid a booming generative AI market.
- Delve into the full analysis future growth report here for a deeper understanding of Micronics Japan.
- Our valuation report here indicates Micronics Japan may be overvalued.
Summing It All Up
- Click this link to deep-dive into the 729 companies within our Fast Growing Global Companies With High Insider Ownership screener.
- Searching for a Fresh Perspective? This technology could replace computers: discover the 25 stocks are working to make quantum computing a reality.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com