
Stellantis Stock In Focus After Loss Narrows And Guidance Holds
- Stellantis reported third quarter 2026 sales of €37.6b and a net loss of €470m, with nine month sales of €119.2b and net income of €186m, while reaffirming full year 2026 revenue guidance for a mid single digit percentage increase.
- The sharp reduction in quarterly loss compared with the prior year, together with progress on cost savings and efficiency measures, highlights how Stellantis is working to reshape its cost base while continuing product investment.
- We will now look at how Stellantis's investment narrative could be influenced by the sharp year on year narrowing of quarterly losses.
Scan how Stellantis' cost reset and product push compares with other automakers by reviewing our hand picked list of solid balance sheet and fundamentals (204 results) that is shaping the next phase of the sector.
Stellantis Investment Narrative Recap
To own Stellantis, you need to believe the effort to reset its cost base and refocus product spending can turn modest revenue growth into cleaner, more reliable earnings. The latest quarter points in that direction, with a sharply smaller loss and positive nine month profit. The key near term swing factor remains execution on efficiency measures while holding pricing discipline.
The biggest risk still sits in margin pressure from electrification, restructuring charges and any renewed weakness in core European light commercial vehicles. This earnings update does not remove those issues. It shows progress on cost savings, but it does not yet resolve exposure to tariffs, competitive pressure or cash outflows.
The reaffirmed 2026 revenue guidance for a mid single digit percentage increase is the announcement that matters most here. Management is effectively saying that, even with ongoing losses in the quarter and restructuring noise, the top line plan for the year remains intact. For you, that keeps the focus squarely on profitability rather than demand.
That guidance also ties directly into the main catalyst investors are watching. Stellantis has pointed to future positive industrial free cash flow and further cost savings, and the confirmation of current year revenue expectations gives a clearer backdrop for those targets. The risk is that tariffs, BEV mix pressure or LCV softness eat into that path if execution slips.
Stellantis' current earnings are a loss of €19.5b, while analysts expect earnings to reach €4.8b by 2029. This implies an earnings improvement of about €24.3b, based on assumed annual revenue growth of 2.8% and projected 2029 revenues of €175.0b.
Uncover why Stellantis' fair value indicates a 28% potential upside to its current price, which could close sooner than many investors expect.
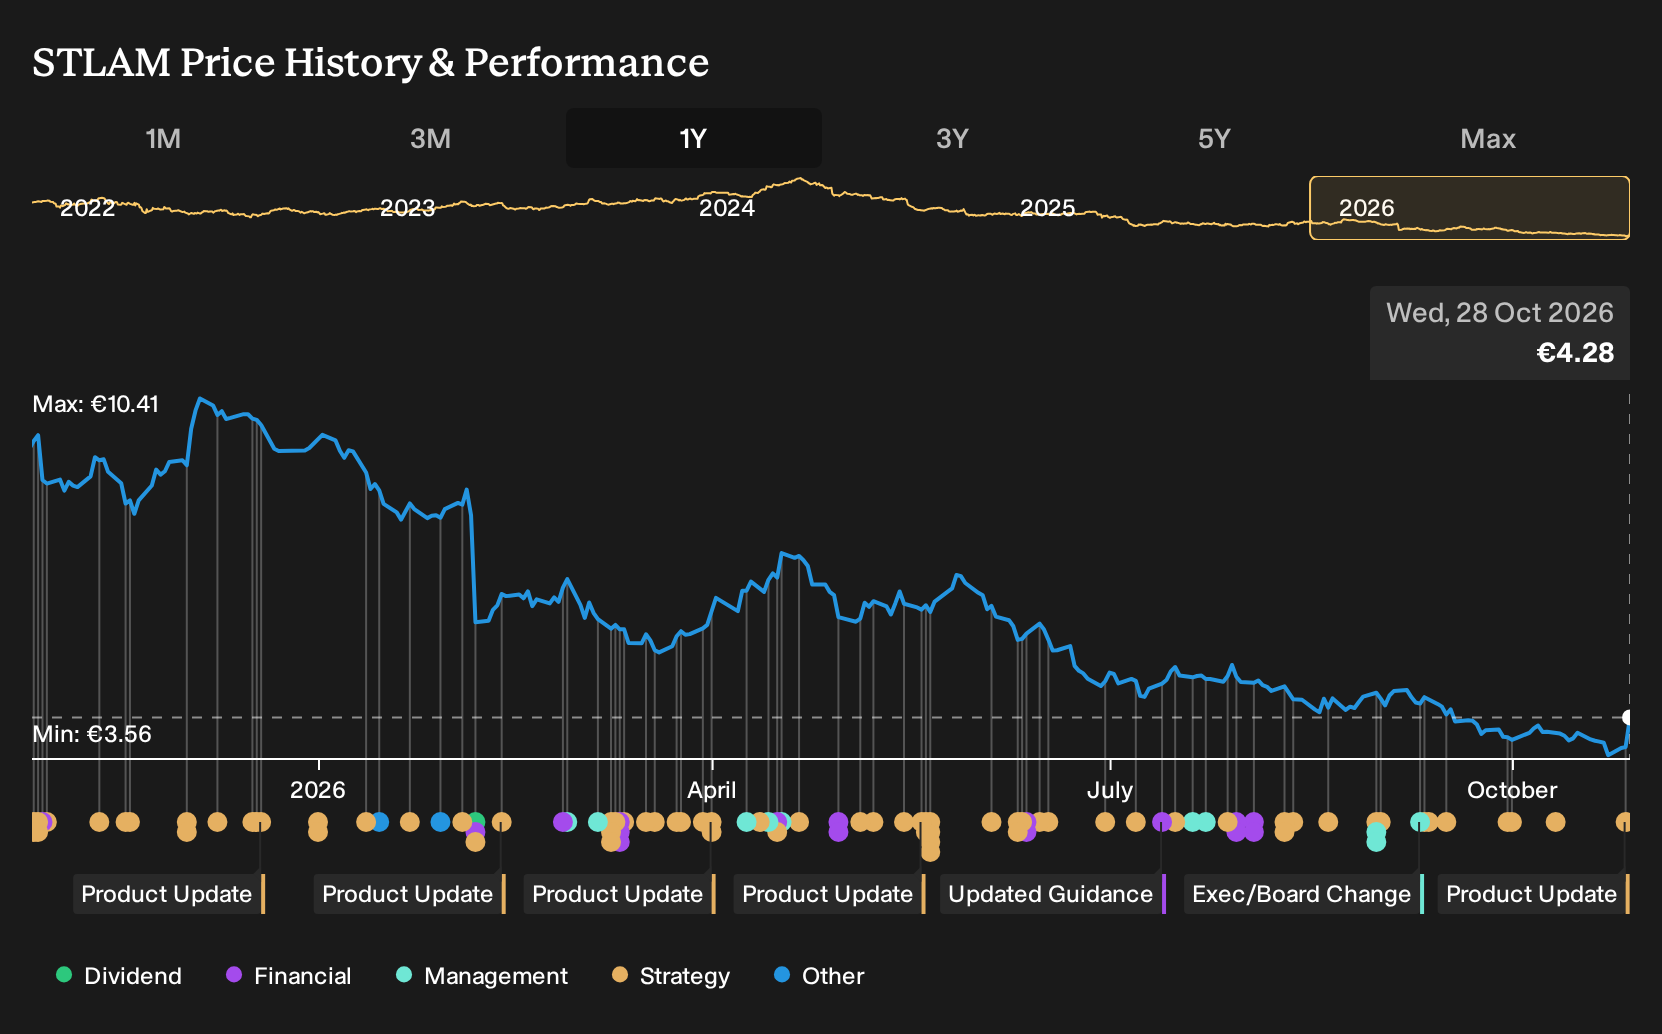
Exploring Other Perspectives
The bearish narrative on Stellantis leans hard on tariff and raw material cost risk. Before this earnings release, the lowest analysts were pencilling in roughly flat revenue to about €165.0b by 2029 and earnings of €3.9b, well below the €4.8b consensus. You can use this quarter’s figures to judge whether that cautious view still fits.
Explore 9 other Stellantis fair value estimates, including one that suggests as much as 23% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Stellantis research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Stellantis. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Stellantis' overall financial health at a glance.
Looking for more investment ideas beyond Stellantis?
If the Stellantis story has you thinking about portfolio upgrades, you can use this earnings update as a springboard to scan other opportunities with the Simply Wall St Screener.
- For investors who focus on cash flow resilience and low leverage, a good starting point is a list of solid balance sheet and fundamentals (204 results) that can handle tougher conditions without constant refinancing risk.
- If value is your priority, consider widening your watchlist with a 189 high quality undervalued stocks where quality fundamentals and pricing gaps might align with your objectives.
- Income focused readers may wish to explore potential cash return opportunities through a curated 224 dividend fortresses that screens for payout strength and yield support.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com