
Is AXT (AXTI) Stock Too Expensive For Its Sales Story?
AXT has seen its share price move sharply in recent years, and the scale of that move raises a straightforward question for you as an investor. Is the current US$64.38 price tag adequately supported by the sales that the business is generating today and those the market is implicitly banking on?
- Over the past 3 years the stock has delivered a very large return of about 32x. This makes it important to test how much of that move can be linked back to its underlying sales power.
- Fresh financing plans for Tongmei and a long term indium phosphide supply deal with Lumentum may support expectations for higher capacity, revenue visibility and capital needs that all feed into how investors treat AXT's sales base.
- The analysts covering AXT have run their own numbers. See what analysts think AXT's shares could be worth.
The issue now is whether AXT's current market value is justified by its sales when set against the Fair Ratio benchmark.
If you are weighing whether AXT's sharp 3 year move is justified by its sales, it can help to compare it with other 26 high quality undervalued stocks
Has AXT Run Too Far on Sales?
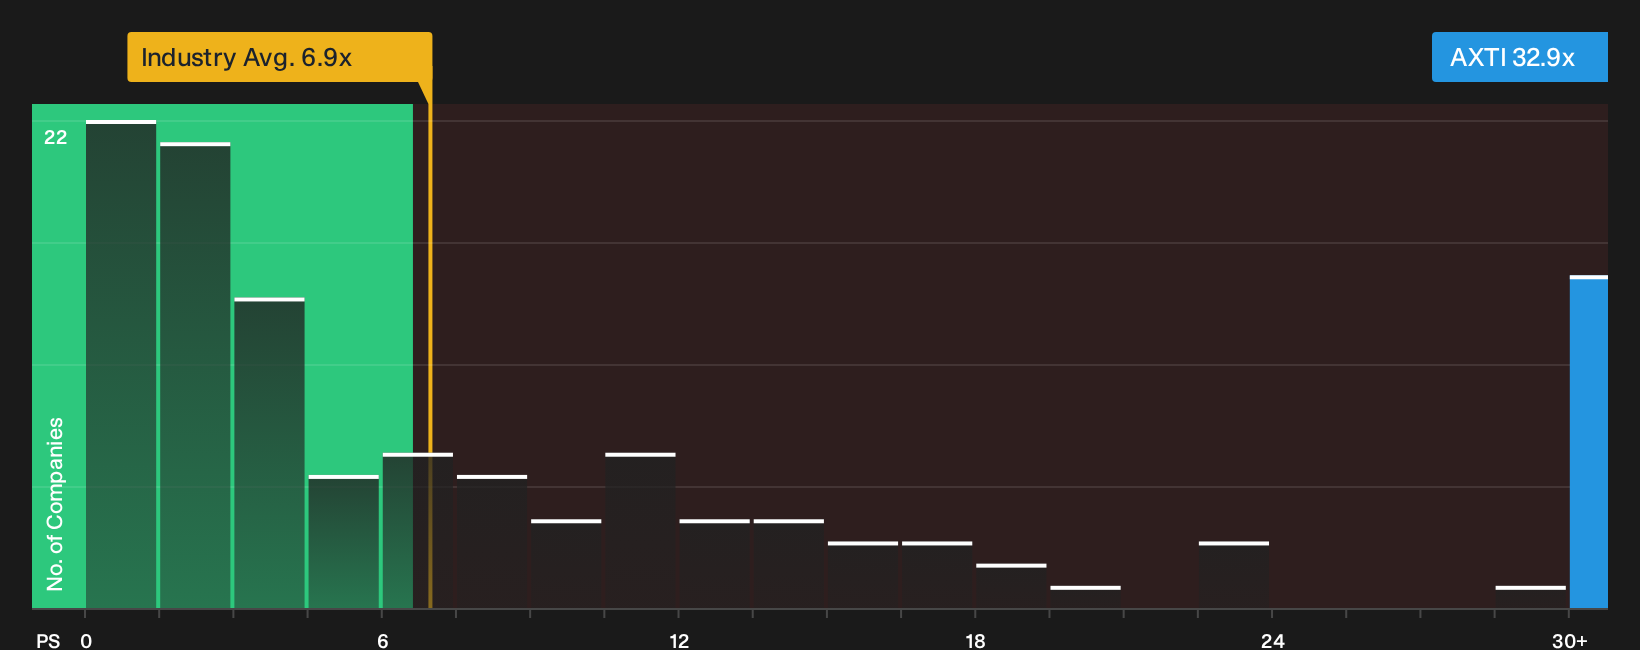
Axt is best judged on its P/S ratio because the market focus is on sales rather than current free cash flow. On this measure, the stock trades on a P/S of 32.9x, compared with about 6.9x for the wider semiconductor industry and roughly 3.2x for its peer group. That is a steep premium for each dollar of revenue.
Fresh Tongmei financing plans and the long term indium phosphide deal with Lumentum sit behind some of that optimism. However, the Fair Ratio model, which adjusts for growth prospects, margins, size and risk, points to the current P/S sitting above what those fundamentals would typically support. Because the news flow has been strong, with capacity expansion and long dated supply visibility improving confidence, the gap suggests the market is already paying up heavily for that story. Explore the numbers behind AXT's P/S valuation.
The AXT Narrative: What Would Justify Today's Price?
AXT's valuation puzzle only really comes into focus once the underlying story is pinned down, which is where Simply Wall St Narratives come in on the Community page. Each scenario spells out what would need to happen to future growth, margins and earnings for the shares to be worth materially more or less than today. Rather than relying on a single multiple or model output, the scenarios set out the assumptions behind each fair value so you can weigh them against actual results as they emerge.
AXT splits opinion, with one camp seeing big upside tied to AI materials demand and the other arguing rich expectations already do most of the work.
Bull case: 30% undervalued
"Accelerating global demand for high-speed data center connectivity and AI infrastructure is driving increased adoption of indium phosphide substrates, where AXT is a top supplier with 40% share..."
Discover why this Narrative puts AXT at 30% undervalued.
Bear case: 17% overvalued
"Despite record indium phosphide revenue and a backlog well over US$100m that supports the AI driven optical networking build out, the current forward P/E near 190 to 210x versus a 5 year median of 18.6x leaves AXT exposed to a scenario where any slowdown in order growth or pricing for data center substrates leads to sharp multiple compression..."
Explore why this Narrative puts AXT at 17% overvalued.
Before acting on AXT’s valuation, there is one more piece to check
Price and sales only tell part of the story, because the people steering AXT and the way their pay is structured can shape every decision that follows. See who runs AXT and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com