
Why Arcutis Biotherapeutics (ARQT) Is Back In The Spotlight
Arcutis Biotherapeutics (ARQT) drew fresh attention after appointing veteran drug developer Rob Scott, MD, to its board, highlighting governance and clinical execution as key angles for investors tracking the dermatology focused biotech.
Against that backdrop, Arcutis Biotherapeutics has seen the share price climb, with a 30 day share price return of 15.07% and a 90 day share price return of 12.36%, while the 1 year total shareholder return of 24.36% sits alongside a very large 3 year total shareholder return that suggests momentum is still building rather than fading.
Scan how Arcutis Biotherapeutics compares with other dermatology focused and healthcare peers by reviewing our hand picked list of solid balance sheet and fundamentals (24 results) alongside this latest board appointment news.
After a sharp move and a heavyweight board addition, Arcutis Biotherapeutics now forces a choice. Does it make more sense to step in at today’s price, or wait for a cleaner entry on the numbers?
Most Popular Narrative: 18% Undervalued
Analysts following Arcutis Biotherapeutics see a gap between the last close at $31.45 and their fair value estimate of $38.38, and they are tying that difference firmly to the potential of the ZORYVE franchise and the broader dermatology pipeline.
Arcutis is poised to sustain and accelerate top-line revenue growth through continued expansion of ZORYVE indications, targeting large, underserved populations such as pediatric atopic dermatitis and scalp psoriasis, while leveraging broadening insurance coverage and the ongoing shift away from steroid use in chronic dermatologic conditions.
The aging population and rising prevalence of chronic skin diseases, coupled with increased societal focus on wellness and early intervention, are driving long-term demand and patient growth for non-steroidal treatments, which is well aligned with ZORYVE's differentiated safety profile and underpins expectations for sustained revenue expansion.
See why 35 investors see Arcutis Biotherapeutics as 18% undervalued.
Result: Fair Value of $38.38 (UNDERVALUED)
Still, the story around Arcutis Biotherapeutics can change quickly if ZORYVE prescription trends undershoot analyst expectations, or if payer coverage tightens and squeezes margins.
Find out about the key risks to this Arcutis Biotherapeutics narrative.
Another View On Arcutis Biotherapeutics: Rich Multiple, Very Different Message
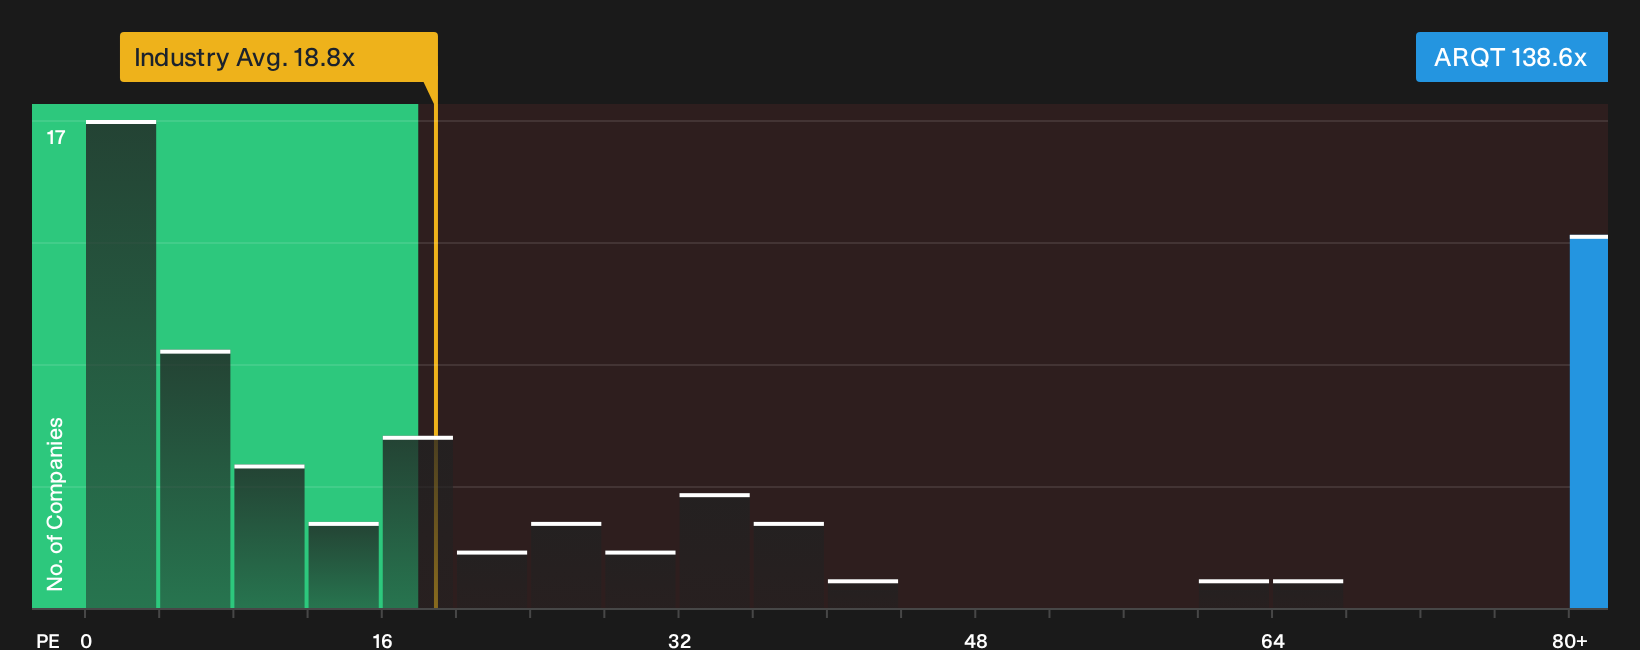
On simple ratios, Arcutis Biotherapeutics tells a very different story. The stock trades on a P/E of 138.6x, versus 18.8x for the wider US biotechs group and a 33x fair ratio that the market could eventually drift toward. That gap points to meaningful valuation risk if growth or sentiment cools.
For investors weighing that contrast, it is worth looking through a detailed breakdown of what the numbers imply for today’s price versus future expectations, and how much room is left if the P/E slides closer to peers or the fair ratio, before deciding how much risk feels acceptable in a dermatology focused biotech like this. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or an early inflection point for Arcutis Biotherapeutics. If you want to move quickly and rely on your own judgment, start by weighing 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Arcutis Biotherapeutics?
If Arcutis Biotherapeutics has your attention, widen the lens and let a data driven screener surface other opportunities that match your risk and return preferences.
- Target potential mispricings by scanning a curated set of companies that screen as attractively valued on both quality and price using the 26 high quality undervalued stocks.
- Prioritize resilience by reviewing a 32 resilient stocks with low risk scores focused on businesses with steadier risk profiles that could help balance more volatile positions in your portfolio.
- Hunt for overlooked potential by filtering through a 19 high quality undiscovered gems that highlights underfollowed stocks with solid underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com