
Earnings Expectations Rise For Zscaler Stock Ahead Of Results
- Zscaler is drawing attention after analysts recently raised earnings per share estimates and projected higher revenue for the upcoming results compared with last year.
- The focus is shifting to how effectively Zscaler can convert its existing customer base and newer AI security offerings into higher long term recurring spend.
- This article now examines how Zscaler's anticipated earnings performance, supported by recent estimate revisions, could influence the broader investment narrative.
Scan Zscaler alongside hand-picked peers that could be setting up for the next leg of AI security spending with the 54 AI infrastructure stocks.
Zscaler Investment Narrative Recap
To own Zscaler, you need to believe the security cloud can keep deepening its role inside large customers, especially through Zero Trust and AI focused services, and that subscription cash flows can scale faster than costs. The upcoming results are a check in on that thesis. Stronger EPS and revenue would signal execution is holding up as the firm pursues that long term ARR framework.
The biggest near term swing factor is how effectively Zscaler converts early AI security demand and metered offerings into larger recurring commitments while managing slower fiscal 2027 growth guidance. The key risk is that Red Canary related churn, smaller AI deal sizes and any sales execution hiccups make that reacceleration story harder to support.
The most relevant update is the recent bump in earnings per share estimates, alongside expectations for higher revenue than last year. That revision ties directly to how investors see Zscaler balancing growth investments with operating discipline, after non GAAP operating and free cash flow margins both reached about 23%.
If the coming print lines up with those refreshed EPS expectations, attention likely shifts back to operational markers. Investors will be watching AI security bookings, traction in Zero Trust Branch and Zero Trust Cloud, and any new color on churn tied to the Red Canary MDR acquisition, since those datapoints speak most directly to future ARR durability and the company’s long run earnings power.
Zscaler Earnings Assumptions In Focus
Zscaler's long term story in the analyst models rests on a few simple levers. Revenue is assumed to compound, margins are expected to turn positive, and earnings are projected to move from losses into material profit over the next few years. For anyone tracking the stock today, those building blocks matter more than any single quarter because they shape how much risk you are really taking on future profit delivery.
Analysts are currently factoring in annual top line growth of 16.7% over the next three years while modeling a shift from a 1.9% loss margin today to a 3.3% profit margin by around 2029. That shift underpins a move in earnings from a loss of US$63.2 million today to projected earnings of US$178.3 million and US$1.34 in earnings per share by about October 2029. The spread between the most optimistic earnings forecast at US$327.5 million and the most cautious at US$16.2 million shows how wide the range of possible outcomes still is.
Zscaler's narrative projects revenues of US$5.3b and earnings of US$178.3 million by 2029. Analysts are assuming yearly revenue growth of 16.7% and an earnings increase of about US$241.5 million from a loss of US$63.2 million today.
On these consensus numbers, the stock would need to trade on a P/E of 293.1x those 2029 earnings, compared with a current P/E of 590.1x based on today's loss making status. That implied future multiple also sits well above the current 30.6x P/E cited for the broader US software peer group. For readers, the key question is not whether those exact figures are right, but whether the move from current conditions to that level of profitability and valuation feels realistic.
The modeling also bakes in share count growth of 2.25% a year for the next three years and uses an 8.7% discount rate from the Simply Wall St framework. Rising share count means each slice of future earnings is spread across more stock, so the jump in earnings per share to US$1.34 assumes both better profitability and enough revenue growth to offset that dilution. This is why the margin path, not just the revenue trajectory, deserves close attention around each earnings update.
Valuation Expectations Around Zscaler
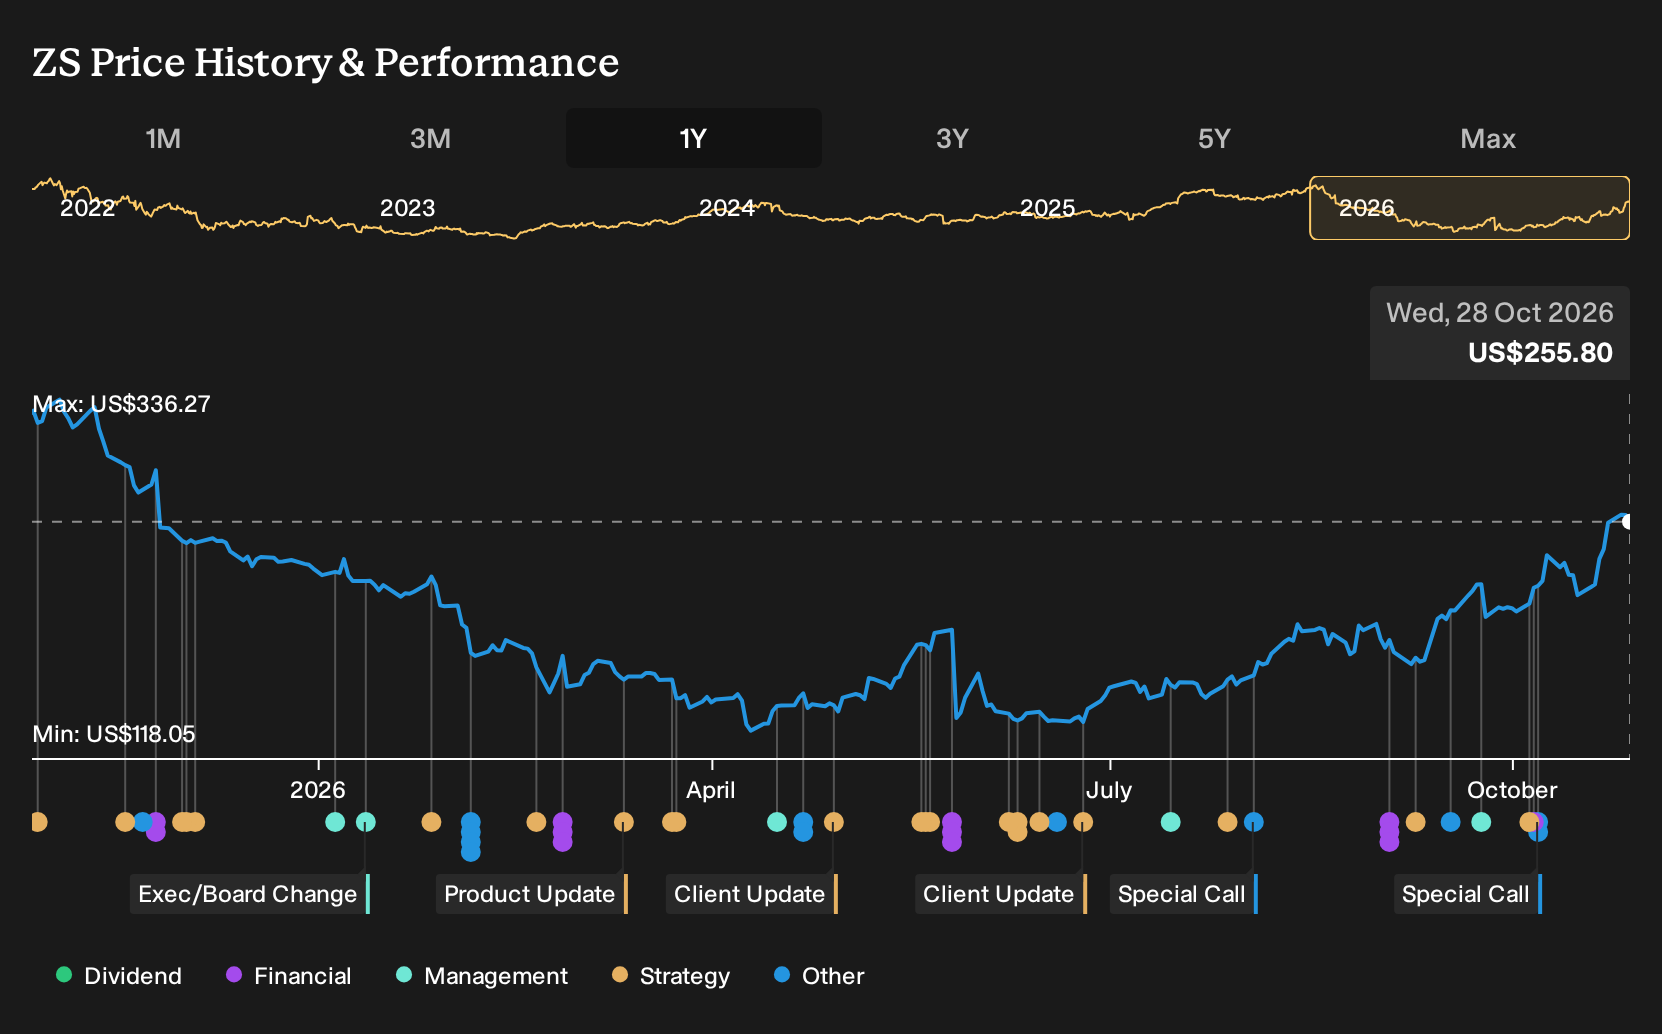
On the valuation side, analysts are clustering around a consensus target of US$233.38 for Zscaler against a recent share price of US$228.66 as at late October 2026. That gap of about 2% suggests the average view is that the stock is roughly aligned with the central earnings path being modeled. In other words, the typical forecast does not assume a large re rating from here.
There is still a spread in price targets, from US$164.75 at the low end to US$298.00 at the high end. That range reflects different views on how quickly Zscaler can convert AI security demand, Zero Trust Branch and Zero Trust Cloud adoption, and Z Flex commitments into lasting recurring revenue and profit. If you are comparing this to other cybersecurity stocks, it can help to ask where your own expectations would land inside that band and why.
To line up with the consensus valuation, you would need to accept a path where Zscaler reaches about US$5.3b in revenue and US$178.3 million in earnings by 2029 while still trading on a P/E multiple near 293.1x. That combination of size, profitability and valuation is already embedded in the current models. Any meaningful shift in the revenue growth rate, AI security monetization, or margin trajectory in upcoming earnings updates could influence how closely the stock tracks that script.
Uncover why Zscaler's fair value indicates a 9% potential downside to its current price, a premium that may not hold.
Exploring Other Perspectives
One alternate angle on Zscaler focuses on capital spending as a potential catalyst rather than a risk. Before this earnings news, some analysts were estimating revenue of about US$5.7b and earnings of roughly US$328.8 million by 2029, which reflects a more optimistic view. Use this report to evaluate which storyline you find more convincing.
Explore 4 other Zscaler fair value estimates, including one that suggests as much as 16% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Zscaler research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Zscaler. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Zscaler's overall financial health at a glance.
Looking for more Zscaler sized investment ideas?
If the Zscaler story has sharpened your view on risk, reward and valuation, use that same lens to scan a wider watchlist with the Simply Wall St Screener. It is one of the fastest ways to spot other stocks that might better match your preferred mix of growth potential, balance sheet strength and income.
- If capital preservation comes first for you, start with resilient businesses by checking out 32 resilient stocks with low risk scores that may offer a steadier ride through different market conditions.
- If balance sheet strength matters most, filter for companies with cleaner finances through the list of solid balance sheet and fundamentals (24 results) to see which ones align with a more quality focused approach.
- If you want ideas that the market may be overlooking, look across the 19 high quality undiscovered gems that pair solid fundamentals with relatively low attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com