
How Investors Are Reacting To American Assets Trust Stock After Earnings Beat
- American Assets Trust reported third quarter 2026 revenue of US$114.28 million and net income of US$7.73 million, with basic and diluted EPS from continuing operations at US$0.13, and affirmed a fourth quarter cash dividend of US$0.34 per share payable on December 17, 2026.
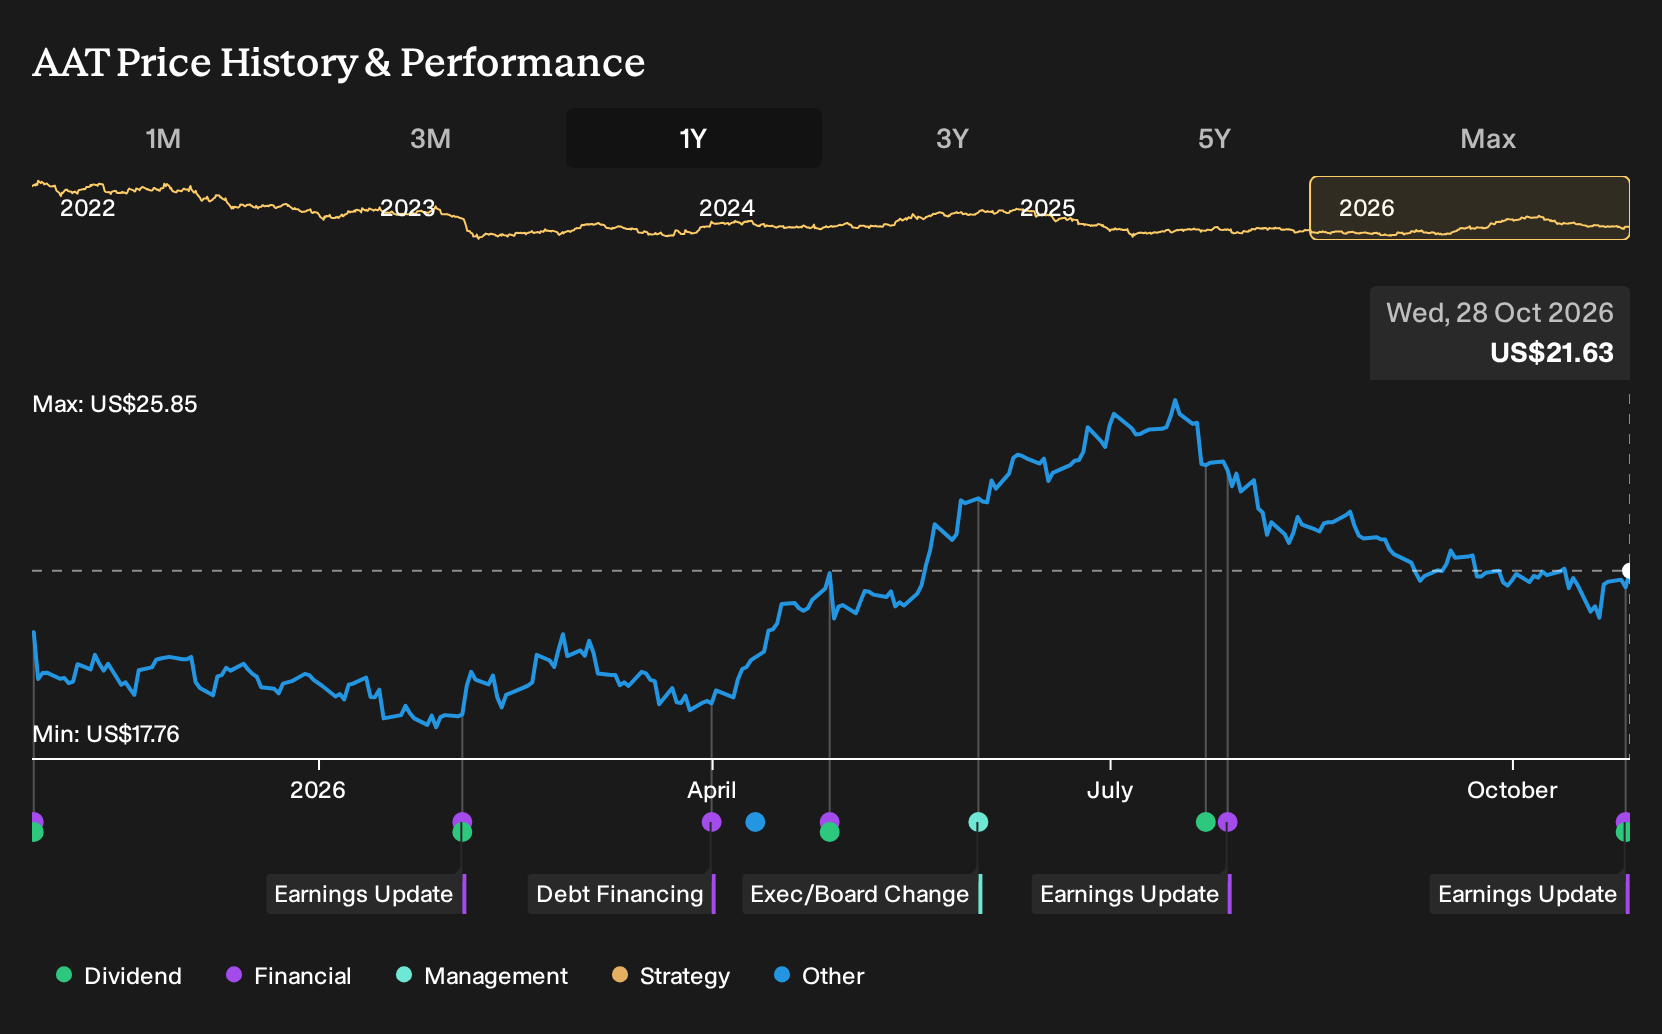
- Investors now see a contrasting picture at American Assets Trust, where quarterly earnings and rental income improved year over year, while net income and EPS for the first nine months of 2026 trailed the prior period, even as management raised full year FFO guidance and maintained the common dividend.
- This article will now explore how American Assets Trust's stronger third quarter earnings and raised FFO guidance could reshape its broader investment narrative.
Compare how American Assets Trust stacks up on income resilience by scanning our hand-picked 6 dividend fortresses with consistent payouts and robust fundamentals.
American Assets Trust Investment Narrative Recap
To own American Assets Trust, you need to believe its coastal office leasing opportunity and high occupancy in retail and multifamily can convert into steadier Funds From Operations and healthier dividend coverage over time. The third quarter showed that the operating engine can produce higher revenue and EPS, even while credit markets and demand for space stay mixed.
The short term swing factor is execution on lease up at projects like La Jolla Commons Tower 3 and Bellevue, which management now reflects in higher full year FFO guidance. The main risk is still balance sheet strain. Net debt is elevated, interest coverage is tight and nine month net income and EPS are weaker, which leaves little cushion if leasing slips.
The most relevant update for that thesis is the new 2026 FFO guidance range of US$2.04 to US$2.10 per diluted share. Raising the outlook after a quarter where revenue reached US$114.28 million and rental income outpaced expectations indicates that the core properties are doing the heavy lifting management discussed previously.
However, the nine month net income line at US$18.04 million, far below the prior period, shows why investors still focus on risk around leverage and interest costs. The affirmed US$0.34 quarterly dividend supports the income story in the near term, but with free cash flow coverage already flagged as tight, execution on lease commencements into 2027 remains crucial to the American Assets Trust narrative.
What The Analyst Forecasts Assume For American Assets Trust
Forecasts around American Assets Trust hinge on a relatively modest outlook for expansion rather than a rapid reset. Analysts are penciling in revenue growth of 2.4% each year over the next three years, paired with profit margins rising from 4.1% today to 8.0% by around 2029. That shift in profitability underpins expectations that earnings could reach US$37.6 million, or US$0.42 per share, compared with about US$18.0 million in earnings today. The consensus view implies that American Assets Trust would be earning just over 2x its current profit level by 2029, although some forecasts stretch as high as US$43.3 million.
On those numbers, the equity story leans on the idea that leasing at La Jolla Commons, Bellevue and other office assets ramps steadily, while retail and multifamily keep occupancy firm. Analysts also assume that share count creeps up by roughly 0.41% per year over the next three years, which slightly dilutes each share’s claim on those projected earnings. To translate these assumptions into today’s price targets, the research uses a discount rate near 8.0% and presents October 2029 as the key reference year for both revenue and earnings.
American Assets Trust's narrative projects US$467.3 million revenue and US$37.6 million earnings by 2029. This aligns with 2.4% yearly revenue growth and roughly a doubling in earnings from about US$18.0 million today.
Uncover why American Assets Trust's fair value indicates a 9% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view leans hard on office risk. If lease up at La Jolla Commons Tower III or One Beach Street drags, American Assets Trust could see slower cash NOI than consensus assumes. The most cautious analysts were only looking for about US$459.5 million revenue and US$27.9 million earnings by 2029 before this report, so their narrative is far more restrained. Use that gap as a prompt to compare several viewpoints and decide which assumptions feel realistic to you now that fresh results and the dividend affirmation are on the table.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your American Assets Trust research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for American Assets Trust. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate American Assets Trust's overall financial health at a glance.
Looking For More Investment Ideas Beyond American Assets Trust?
Once you have a view on American Assets Trust, it can help to widen the lens and compare it with other businesses that have different income profiles, balance sheet strength, and risk levels. The Simply Wall St Screener gives you a structured way to do that by filtering companies based on the traits that matter most to you.
- If you care most about capital preservation and steadier return potential, start with a basket of 32 resilient stocks with low risk scores that aim to keep drawdowns in check while still offering room for upside.
- For investors hunting for strong fundamentals at prices that look reasonable on the numbers, scan our 19 high quality undiscovered gems that combine quality metrics with relatively low market attention.
- If balance sheet strength is your first filter, narrow your watchlist to a list of solid balance sheet and fundamentals (24 results) so you can focus on companies with cleaner debt profiles and healthier financial cushions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com