
Tsugami (TSE:6101) Lifts Guidance And Dividend, Is The Stock Still Cheap?
Tsugami (TSE:6101) has put fresh numbers on the table, lifting its earnings outlook for the six months to September 30, 2026 and outlining a higher interim dividend.
Tsugami’s guidance lift lands after a mixed stretch in the market, with the share price down about 25% over the past 3 months and roughly 13% over the past month, yet still showing a 57% year to date share price return and a 1 year total shareholder return of about 70%. This suggests earlier optimism has cooled recently, even as longer term holders have seen strong gains.
Scan the market for other industrials where guidance and shareholder returns are starting to move in the same direction using our curated list of list of solid balance sheet and fundamentals (23 results)
The guidance upgrade sits against a share price that has retreated sharply in recent months. Are investors reassessing Tsugami’s earnings power? Or has sentiment simply swung faster than the business fundamentals justify, setting up the valuation debate next?
Preferred P/E of 11x for Tsugami: Is it justified?
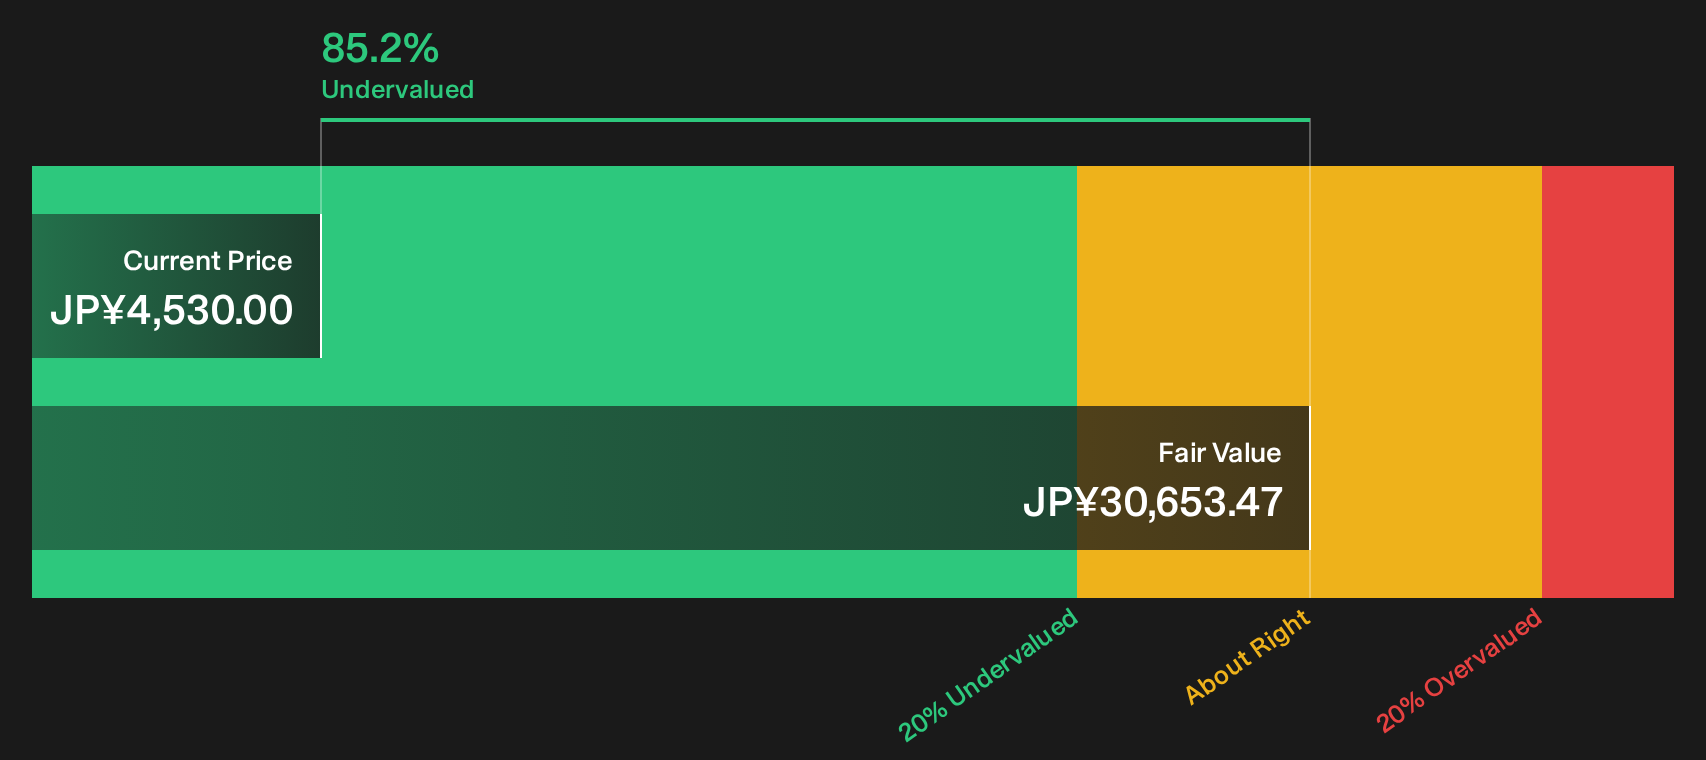
Valuation signals for Tsugami are blunt. At a last close of ¥4,530, the shares trade on a P/E of 11x while our model-based fair value work suggests the stock is at an 85.2% discount to estimated future cash flows.
The P/E ratio compares the current share price with earnings per share. For a precision machine tools manufacturer like Tsugami, where profitability and capital intensity matter, P/E gives a direct read on how much investors are willing to pay for current profits.
On this measure, Tsugami screens as inexpensive compared with both peers and its own earnings profile. Earnings grew 53.6% over the past year and have compounded at 16% per year over five years, while the P/E of 11x sits below the peer average of 16.4x and below the wider JP Machinery industry average of 12.5x. The SWS DCF model adds another layer, with the current price of ¥4,530 far below its estimated future cash flow value of ¥30,653.47. This implies the market is pricing those cash flows very conservatively.
Compared with the Machinery group, the discount looks clear. A P/E of 11x against 16.4x for similar stocks and 12.5x for the broader industry points to the market assigning Tsugami a lower earnings multiple despite high return on equity of 23.2% and improved net profit margins of 13.6% from 10.9% last year.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 11x (UNDERVALUED)
Still, the heavy reliance on China for more than half of Tsugami’s revenue, along with recent share price volatility, could quickly challenge any simple undervaluation story.
Find out about the key risks to this Tsugami narrative.
Another view on Tsugami’s value
The P/E story suggests Tsugami looks inexpensive, and the SWS DCF model goes much further. That framework values the shares at an estimated future cash flow value of ¥30,653.47 versus the current ¥4,530, which indicates very heavy undervaluation on cash flow assumptions.
DCF models rely on long term forecasts and discount rates that can shift quickly when conditions change, so any gap of this size raises a practical question for investors. Is the model too optimistic about future cash generation, or is the market overly cautious about Tsugami’s earnings durability?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Tsugami for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Plenty in this Tsugami story can sound persuasive on both sides. Move quickly from headline impressions to the underlying facts and weigh them yourself using our breakdown of 3 key rewards and 1 important warning sign
Looking for more Tsugami-style investment ideas?
If Tsugami has sharpened your focus on valuation and quality, do not stop here. Broaden your watchlist and keep fresh opportunities on your radar.
- Target potential mispricings by scanning companies that screen as attractively valued and financially sound through our 15 high quality undervalued stocks.
- Build a steadier income stream by reviewing businesses with strong payouts on our curated 29 dividend fortresses.
- Strengthen your downside protection by focusing on companies with robust finances using the 25 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com