
Earnings Beat Could Change The Case For Hayward Holdings Stock
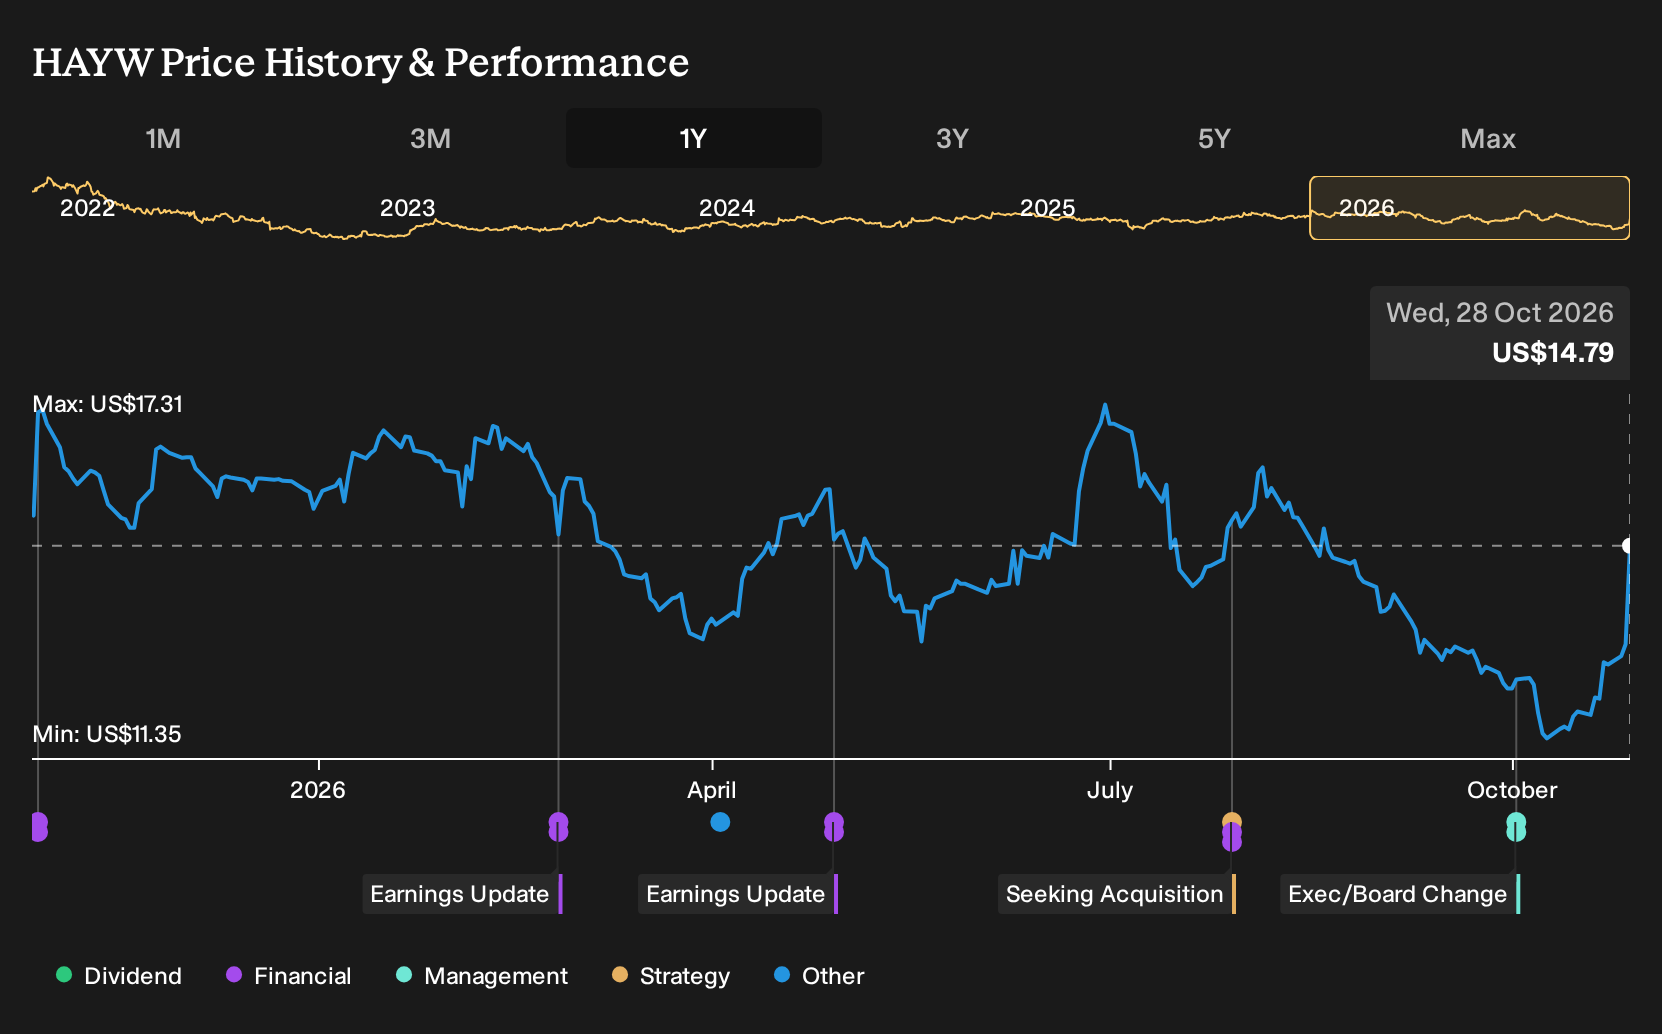
- Hayward Holdings reported third quarter 2026 basic and diluted earnings per share from continuing operations of US$0.15, up from US$0.11 a year earlier, and lifted full year guidance to net sales growth of about 5% to 6% versus fiscal 2025.
- Management linked the stronger earnings profile and higher outlook to solid execution, pricing and volume support, and firm demand in North America, even as new pool construction and some international markets faced pressure.
- We will now look at how Hayward Holdings’ raised sales outlook and earnings beat could reshape the existing investment narrative.
See how Hayward Holdings' execution-led beat compares with other companies showing resilient fundamentals and disciplined growth in our carefully curated 19 high quality undiscovered gems list.
Hayward Holdings Investment Narrative Recap
To own Hayward Holdings, you need to believe the aftermarket driven pool equipment model, especially OmniX automation, can keep pulling more spend from the existing installed base even when new pool construction stays soft. The latest quarter, with higher earnings per share and a raised sales outlook, supports that operating thesis rather than changing it.
The near term swing factor is whether North American demand and early buy orders keep absorbing any softness in Europe and other regions. The biggest risk remains credibility and execution, given the past disclosure settlement and mixed long run growth record, so consistent cash generation and clear communication will matter more than one strong quarter.
The raised full year 2026 guidance, with Hayward Holdings now expecting net sales to increase about 5% to 6% versus fiscal 2025, is the key update for this catalyst story. That outlook rests on pricing, volume support and technology adoption, and it aligns directly with the idea that OmniX enabled systems can lift content per pool.
For you as a shareholder, this matters because the thesis focuses on steady aftermarket demand and margin quality rather than aggressive volume from new builds. Any signs that higher guidance is difficult to meet, that operating cash flow pressure persists or that international weakness spreads would quickly shift attention back to the long term growth doubts highlighted in past data.
Hayward Holdings' current analyst narrative points to revenue of about US$1.4b and earnings of roughly US$222.3 million by 2029, based on a forecast revenue growth rate of 5.7% a year and consensus earnings rising from US$161.4 million today, which implies an earnings increase of about US$60.9 million by the forecast year.
Uncover why Hayward Holdings' fair value indicates a 12% potential upside to its current price before this valuation gap closes.
Exploring Other Perspectives
One alternate view leans hard into OmniX and higher value upgrades as the real catalyst for Hayward Holdings. Those bullish analysts were already modeling about US$1.4b of revenue and earnings of roughly US$231.8 million by 2029 before this quarter. You can now ask whether the latest beat and raised guidance nudges those forecasts even higher or simply narrows the gap between cautious and optimistic scenarios.
Explore another Hayward Holdings fair value estimate, including one that suggests as much as 27% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Hayward Holdings research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Hayward Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hayward Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Hayward Holdings?
Once you understand where Hayward Holdings fits in your watchlist, it can help to scan for other opportunities that match different risk and income profiles. The Simply Wall St Screener lets you quickly filter for stocks with attributes that line up with your own approach, whether that means stability, value, or income.
- If capital preservation sits high on your list, start with companies that score well on resilience by checking out 32 resilient stocks with low risk scores.
- For investors hunting for quality at a reasonable price, broaden your opportunity set with a curated pool of 26 high quality undervalued stocks.
- If income matters just as much as price, build a shortlist of yield focused ideas drawn from our universe of 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com