
Waystar Holding (WAY) Flags Payer Recoupment Strain, Is The Discount Enough?
Waystar Holding (WAY) is back in focus after releasing new research with Modern Healthcare on payer recoupments, highlighting how post payment clawbacks are affecting hospital cash flow, risk management, and administrative workloads.
Waystar Holding’s recent 3.21% 1 day share price return and 38.11% 90 day share price return contrast with a year to date share price decline of 7.81% and a 1 year total shareholder return that is down 27.01%. This suggests momentum has picked up recently even as longer term holders have faced weaker results.
Scan how other healthcare payment and revenue cycle stocks are positioned for similar pressures by reviewing the hand picked 36 healthcare AI stocks that could benefit from rising payer complexity.
Waystar Holding has rallied hard off the lows, yet still trades below both analyst targets and some intrinsic value estimates. Does that gap reflect opportunity, or a fair discount on the recent risks and recoupment realities now in view?
Most Popular Narrative: 14.5% Undervalued
At a last close of $28.92 against a widely followed fair value estimate of about $33.83, the current pricing of Waystar Holding sits at a clear discount that investors are weighing against its leverage, AI ambitions, and recoupment exposure.
The acquisition of Iodine Software, a leading provider of AI-powered clinical intelligence, will expand Waystar's total addressable market by over 15%, accelerate its product roadmap, and immediately boost gross margins and adjusted EBITDA margins, setting up compounding, long-term revenue and earnings growth.
See why 4 investors see Waystar Holding as 15% undervalued.
Analysts behind this narrative use a 9.02% discount rate and reach a fair value of roughly $33.83 per share, which sits about 14.5% above that $28.92 close and well below Simply Wall St's separate future cash flow estimate of $53.88. The gap between those two valuation anchors underlines how sensitive modeled worth can be to revenue paths, profit margins, and terminal assumptions in a software driven healthcare business.
For readers trying to square that narrative with the recoupment study, the key tension is simple. Cash flow modeling leans on current annual revenue of about $1.21b, earnings of $134.8m, and modeled earnings growth of 21.4% per year, while the new research highlights payer behaviors that can disrupt timing and collection of those same dollars.
Result: Fair Value of $33.83 (UNDERVALUED)
Still, the Waystar Holding story can break if the US$1.25b Iodine deal fails to deliver expected synergies or if larger health systems push harder on pricing.
Find out about the key risks to this Waystar Holding narrative.
Another View: Waystar Holding Through Market Ratios
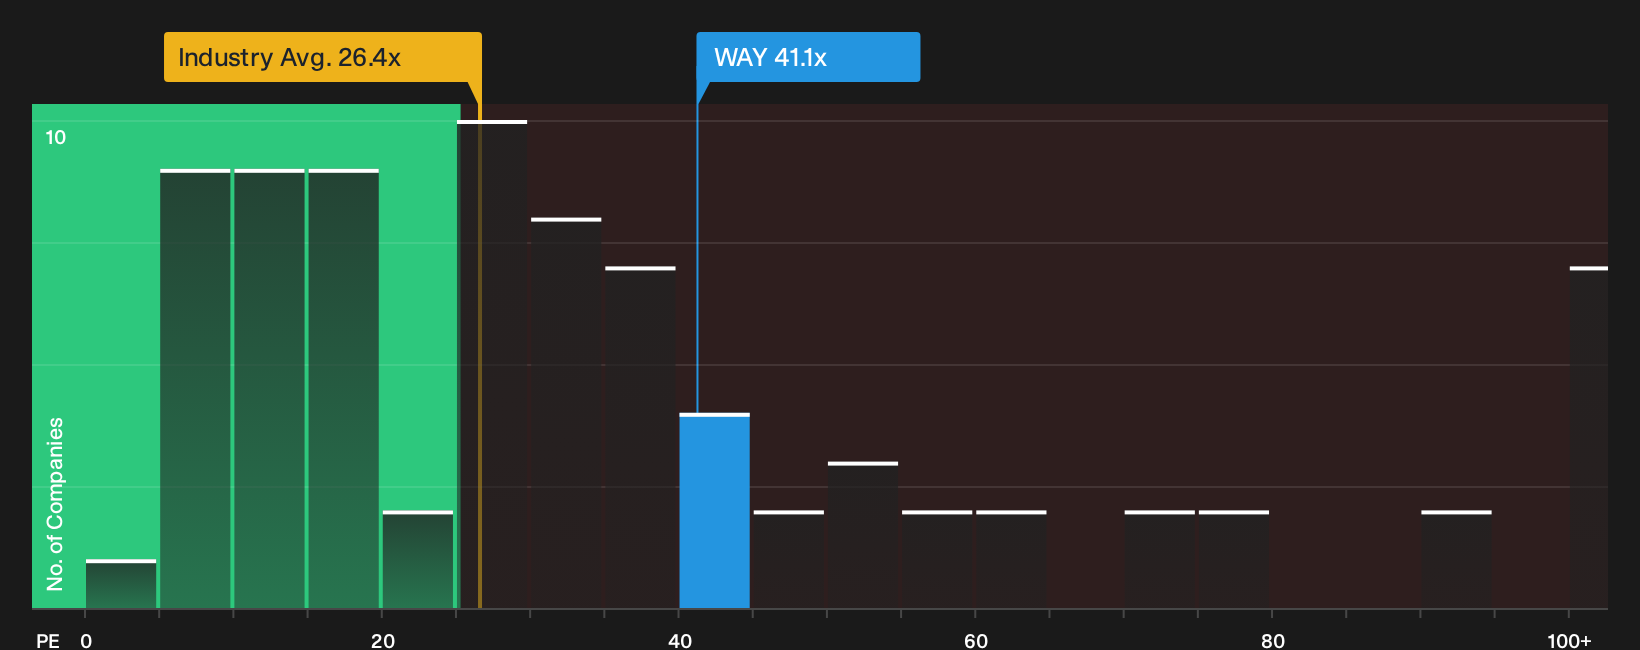
The story flips when you leave discounted cash flows aside and look at Waystar Holding through its P/E. At 41.1x earnings against a fair ratio of 32.4x, and compared with 26x for the wider Healthcare Services group and 57.9x for peers, the stock screens as expensive. Is that premium a red flag or a price for quality growth?
To see how that richer multiple stacks up in more detail, and where the market could shift if sentiment turns, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on Waystar Holding so far. If you want to move quickly and ground your own stance in the underlying metrics, take a closer look at the 3 key rewards
Looking for more investment ideas beyond Waystar Holding?
If you want a fuller watchlist and not just a single thesis around Waystar Holding, use the Simply Wall St screener to pressure test fresh opportunities fast.
- Target reliable balance sheets and steadier fundamentals with a curated list of solid balance sheet and fundamentals (24 results) that prioritises financial strength over headline excitement.
- Hunt for quality businesses at prices that look appealing by running through the 26 high quality undervalued stocks before momentum leaves them behind.
- Zero in on underfollowed opportunities that still show solid numbers using the focused 19 high quality undiscovered gems so you are not late to the story.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com