
Plug Power (PLUG) Stock Still Looks Above Fair Value Despite 96% Fall
Plug Power has seen its stock punished over the long haul, and the recent share price slide keeps the focus squarely on whether the current valuation can be squared with its sales base. With the business still generating headlines around hydrogen projects and manufacturing plans, the core question for you is how much revenue this story currently supports in the market price.
- Over the past 5 years, Plug Power’s share price has fallen 96.5%, which puts the spotlight on whether the remaining equity value is still being anchored to its sales potential.
- Recent updates on revenue ambitions, electrolyzer agreements and efforts to improve manufacturing efficiency may support a particular view on how much investors are paying for Plug Power’s sales today.
- Your read on Plug Power is one view; the desks covering it have another. See what analysts think Plug Power's shares could be worth.
The stock's next move may depend on whether investors judge Plug Power's current market price to be justified by its sales when compared with the Fair Ratio benchmark.
If you are weighing whether Plug Power’s US$1.42 share price lines up with its sales, it can help to compare that question across 26 high quality undervalued stocks.
Does Plug Power Look Pricey on Sales?
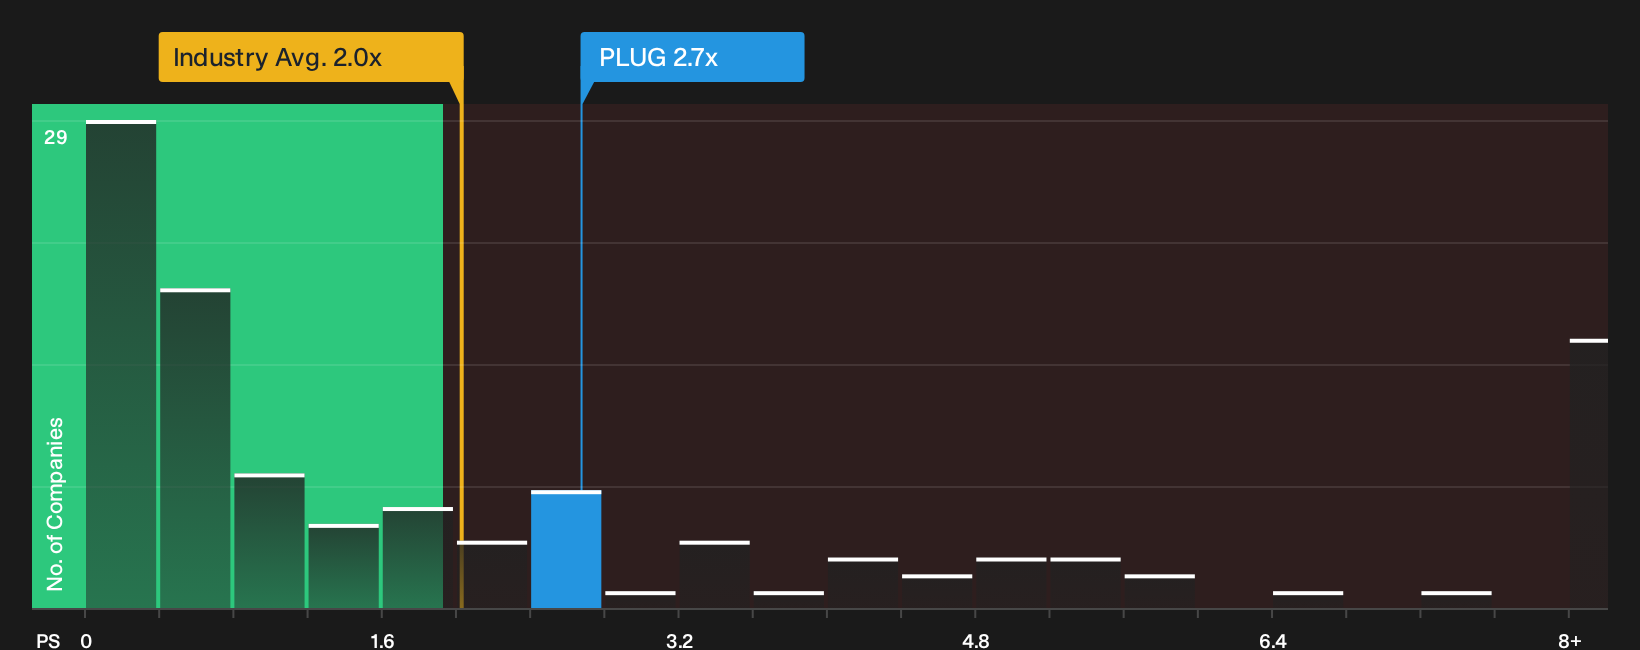
The P/S ratio suits Plug Power because investors often look at revenue multiples when a business is still working toward consistent profitability. Plug Power trades on a P/S of about 2.7x, which is higher than the Electrical industry average of roughly 2.0x and also above the peer group near 2.0x. That means you are paying more for each dollar of Plug Power’s sales than for many sector alternatives.
The Fair Ratio model, which incorporates Plug Power’s revenue profile, margins, market size and risk, places the stock well above the level it flags as comfortable. The gap is wide enough that the framework is effectively treating the shares as screening very expensively on this metric rather than pointing to a precise target. Despite recent news about revenue guidance, electrolyzer agreements and manufacturing progress, the current P/S still prices Plug Power at a premium that assumes a lot from its sales base. Explore the numbers behind Plug Power's P/S valuation.
The Plug Power Narrative: What Would Justify Today's Price?
Narratives on Plug Power pick up where the P/S puzzle leaves off by explaining which potential paths for future revenue, profitability, and earnings would need to occur for the share price to sit meaningfully above or below today's level.
Each scenario links Plug Power's potential catalysts and key risks to a single implied value, allowing you to track over time which storyline most closely aligns with what actually happens in the business.
Bullish and bearish Plug Power holders are looking at the same hydrogen story and drawing sharply different conclusions about what the stock is worth.
Bull case: 60% undervalued
"Operational improvements such as gross margin enhancements from Project Quantum Leap, restructuring, facility consolidation, and favorable hydrogen supply agreements are already yielding sharply better margins..."
Discover why this Narrative puts Plug Power at 60% undervalued.
Bear case: 89% overvalued
"The cancellation of the 100 MW green hydrogen plant at the Port of Antwerp after the loss of a US$1.66b loan guarantee, together with the related €13.6 million write off, shows that large European projects can still fail at a late stage..."
Explore why this Narrative puts Plug Power at 89% overvalued.
Before you act on Plug Power's valuation, there is one more angle to check
Numbers on revenue and multiples only tell part of the story, because the people steering Plug Power and the way their pay is structured can strongly shape what happens next. See who runs Plug Power and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com