
Garrett Motion’s (NASDAQ:GTX) Q3 2026 earnings results: revenue in line with expectations
Turbocharger technology company Garrett Motion (NYSE:GTX) met Wall Street’s revenue expectations in Q3 2026, with revenue rising 3.1% year on year to $930 million. The company’s outlook for the full year was close to analysts’ consensus estimates with revenue guided to $3.8 billion at the midpoint. Its GAAP profit of $0.51 per share was 21.3% above analysts’ consensus estimates.
For more on Garrett Motion, read our full research report, available free.
Garrett Motion (GTX) Q3 2026 highlights:
- Revenue $930 million vs S&P analysts’ consensus estimates of $930.4 million (3.1% year-on-year growth, in line)
- EPS (GAAP) $0.51 vs analysts’ consensus estimates of $0.42 (21.3% beat)
- Adjusted EBITDA $183 million vs analysts’ consensus estimates of $169.3 million (19.7% margin, 8.1% beat)
- Revenue guidance The company reconfirmed its revenue guidance for the full year of $3.8 billion at the midpoint
- EBITDA guidance $706 million at the midpoint for the full year, above analysts’ consensus estimates of $692.9 million
- Operating margin 15.6%, up from 14.2% in the same quarter last year
- Free cash flow margin 12.9%, up from 11.9% in the same quarter last year
- Market capitalization $4.16 billion
“Our third quarter results reflect the strength of Garrett’s differentiated portfolio, disciplined execution and ability to grow ahead of the industry. We continued to secure new business in turbo, support growing demand for industrial applications and advance our zero emission technologies, while delivering strong profitability and cash flow. With this continued momentum we reaffirm our 2026 mid-point outlook, offsetting unfavorable foreign exchange, and remain focused on delivering long-term value for our shareholders,” said Olivier Rabiller, President and CEO of Garrett.
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Any business can experience short-term success, but top-performing ones sustain growth for years. Garrett Motion struggled to consistently increase demand as its $3.78 billion in revenue for the trailing 12 months was close to its revenue five years ago. That was an underwhelming result.
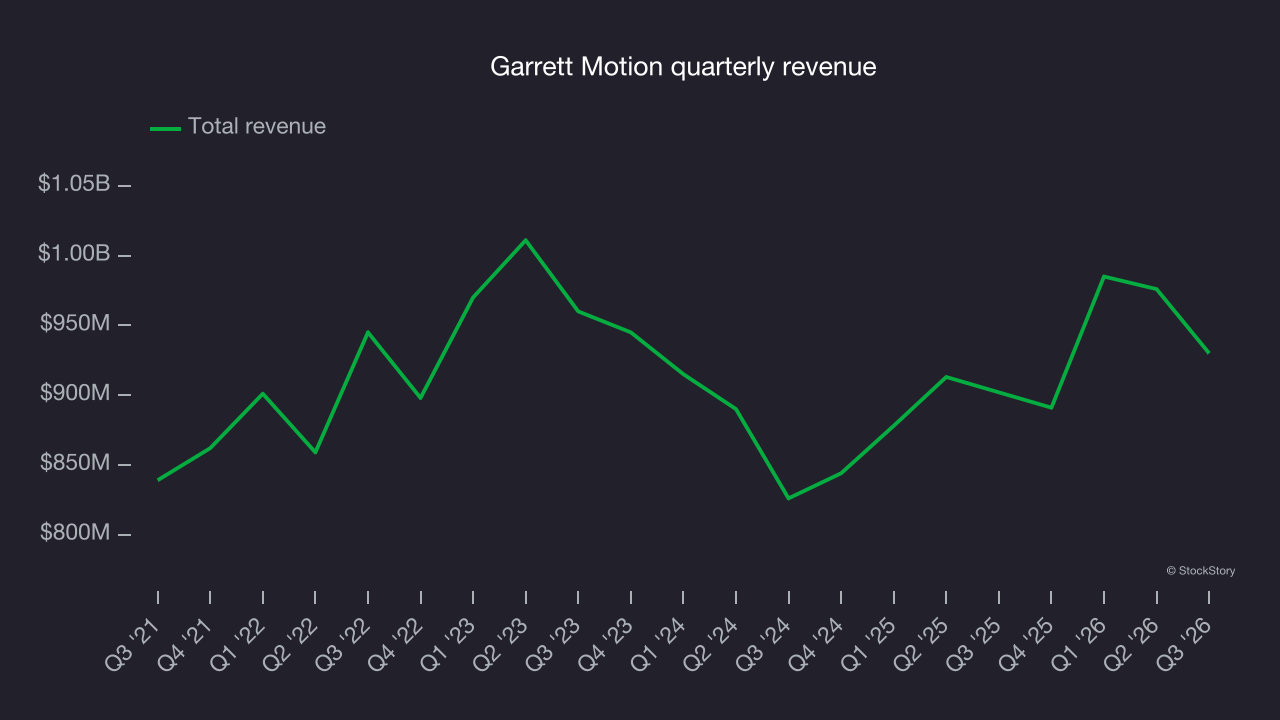
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. Garrett Motion’s annualized revenue growth of 2.8% over the last two years is above its five-year trend, a positive sign. 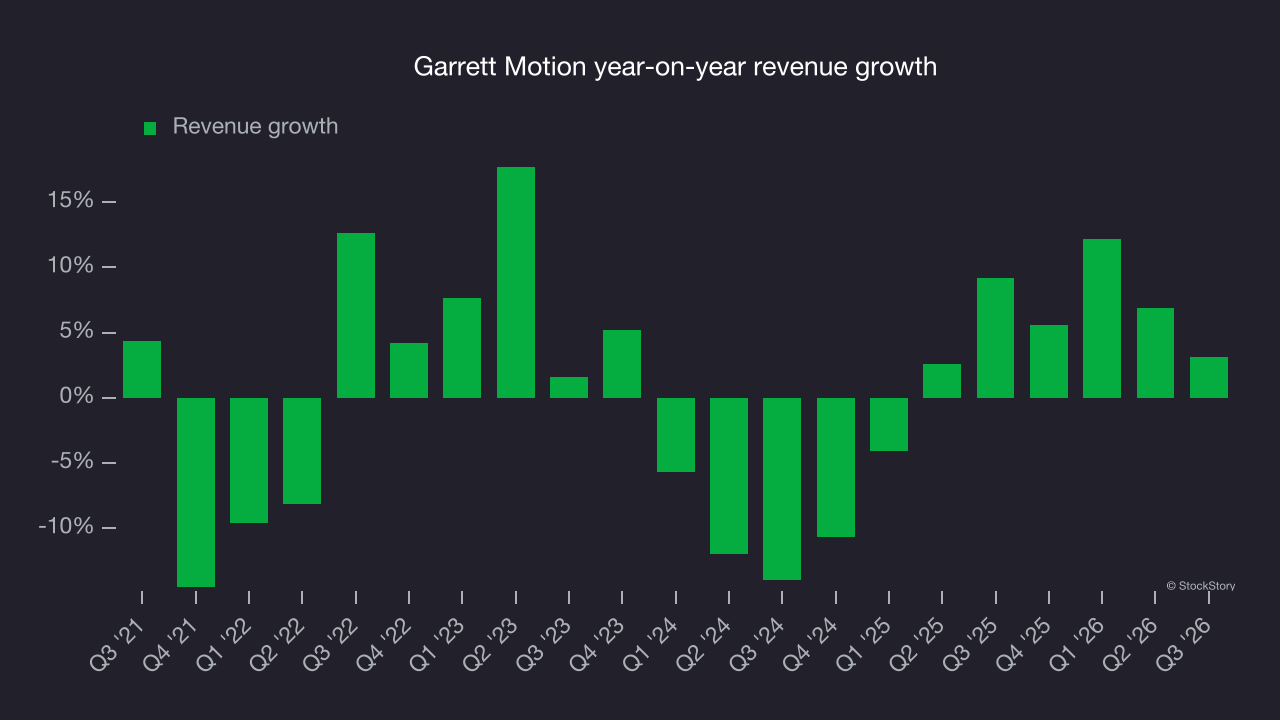
This quarter, Garrett Motion grew its revenue by 3.1% year on year, and its $930 million in revenue was in line with Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 3.2% over the next 12 months, according to S&P, similar to its two-year rate. This projection is underwhelming and suggests its newer products and services will not accelerate its top-line performance yet. At least the company is tracking well in other measures of financial health.
Operating margin
Operating margin is a key measure of profitability. Think of it as net income, or the bottom line, excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
Garrett Motion has been an efficient company over the last five years. It was one of the more profitable businesses in the industrials sector, with an average operating margin of 13.4%. This result was particularly impressive given its low gross margin, which is mostly a factor of what it sells and requires substantial shifts to change meaningfully. Companies have more control over their operating margins, and high operating margins alongside low gross margins are a sign of well-managed operations.
Analyzing the trend in its profitability, Garrett Motion’s operating margin rose by 1.6 percentage points over the last five years, showing its efficiency has improved.
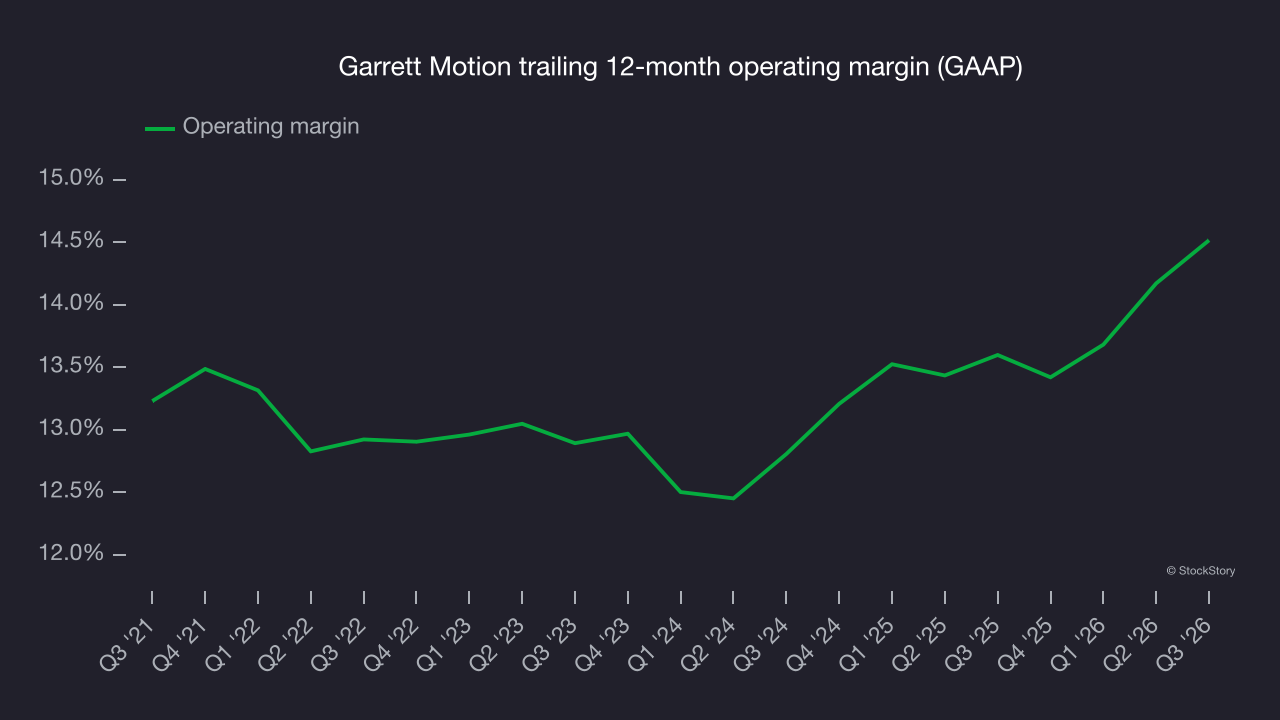
This quarter, Garrett Motion generated an operating margin of 15.6%, up 1.4 percentage points year on year. Since its gross margin expanded more than its operating margin, leverage on its cost of sales appears to have been the primary driver of the recent efficiency improvement.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth – for example, a company could inflate its revenue through excessive spending on advertising and promotions.
Garrett Motion’s EPS grew at a 41.8% compounded annual growth rate over the last five years, higher than its flat revenue. This indicates that management responded to softer demand by adapting its cost structure.
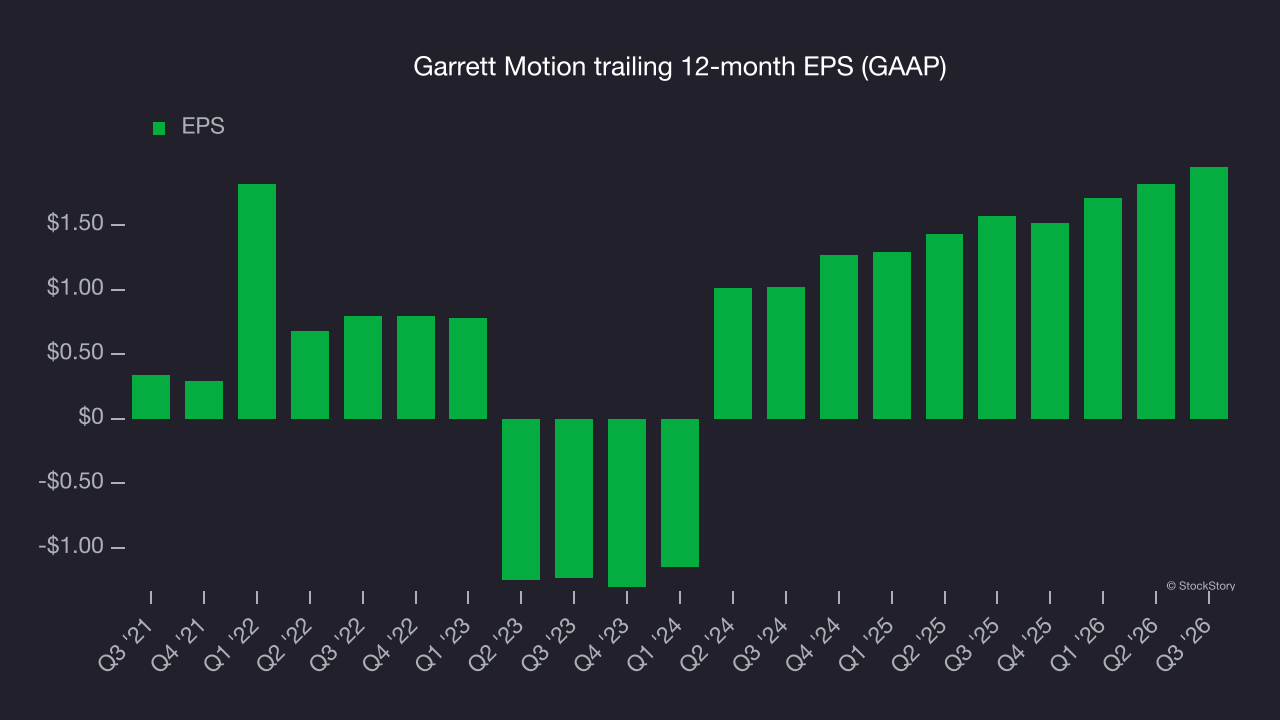
Diving into the nuances of Garrett Motion’s earnings can give us a better understanding of its performance. As we mentioned earlier, Garrett Motion’s operating margin expanded by 1.6 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its higher earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
Like with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
For Garrett Motion, its two-year annual EPS growth of 38.3% was lower than its five-year trend. Its growth was still good, but a faster pace would be welcome.
In Q3, Garrett Motion reported EPS of $0.51, up from $0.38 in the same quarter last year. EPS came in well above analysts’ consensus estimates, a positive result for shareholders. Over the next 12 months, Wall Street expects Garrett Motion’s full-year EPS to grow 3.5% from $1.95 to $2.02, according to S&P.
Key takeaways from Garrett Motion’s Q3 results
A sizable EBITDA beat led Garrett Motion’s decent quarter, with EPS also topping Wall Street’s consensus estimates. Full-year revenue guidance, however, was in line with expectations. Shares remained flat at $22.35 immediately after the results.
Garrett Motion may have had a good quarter, but that alone doesn’t make the stock a buy. What happened in the latest quarter matters, but not as much as longer-term business quality and valuation when deciding whether to invest in this stock. For more on Garrett Motion, read our full research report here (it’s free).