
Deluxe (DLX) Stock May Be Undervalued On Current Earnings Power
Deluxe has delivered a 68.3% gain over the past three years, which puts a spotlight on whether the current share price properly reflects what the business is earning today. With the stock recently closing at US$22.92, the key issue for you is whether that move lines up with the company’s profit power.
- The 68.3% three year return has rewarded holders, which now makes the relationship between Deluxe’s earnings and its market valuation more important to watch.
- The business model leans on turning recurring services into steady profit, which can influence how much investors are willing to pay for each dollar of earnings.
- Your read on Deluxe is one view; the desks covering it have another. See what analysts think Deluxe's shares could be worth.
The stock’s next move may depend on whether Deluxe’s recent earnings are strong enough to justify where the shares trade today.
If you are weighing whether Deluxe’s 68.3% three year return is backed by sustainable profit power, it can help to compare that earnings trade off against 26 high quality undervalued stocks
Is Deluxe a Bargain on Earnings?
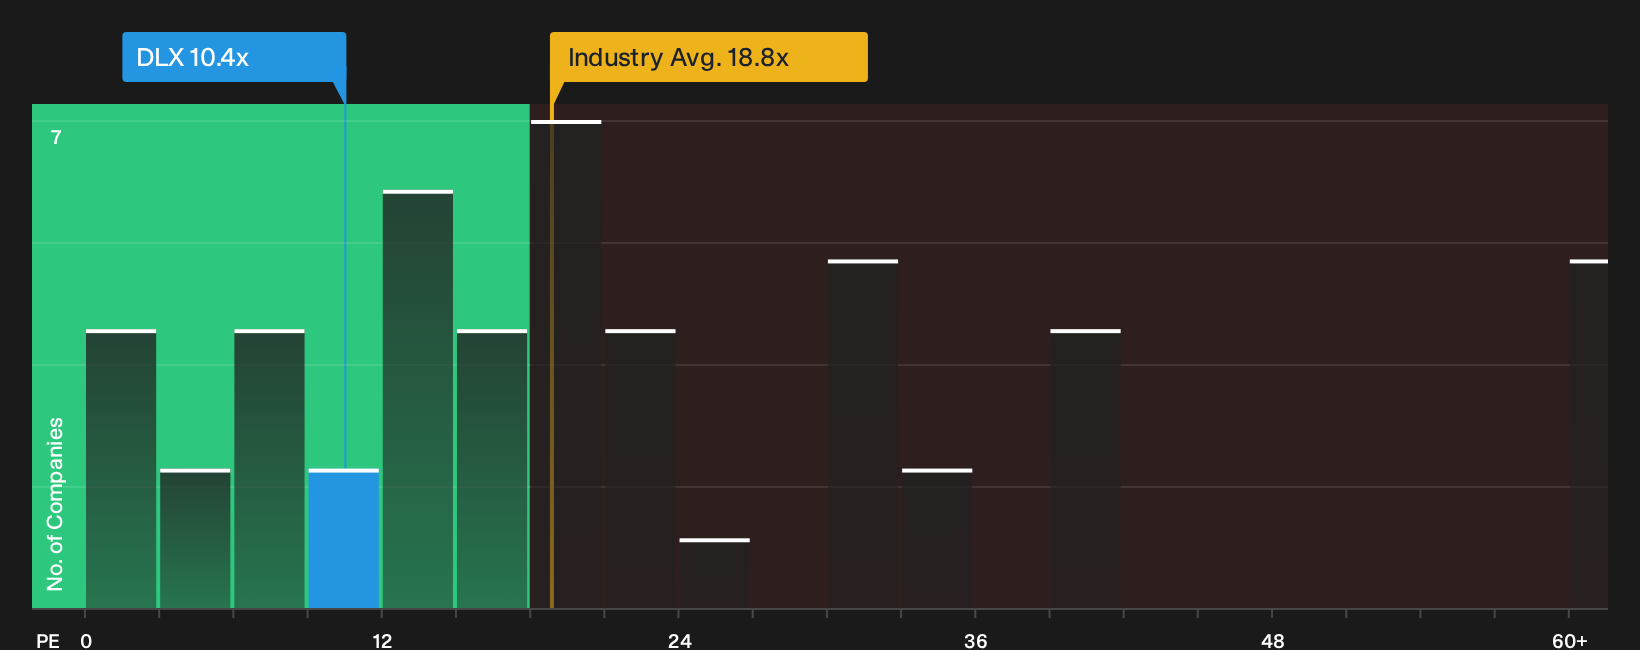
The P/E ratio suits Deluxe because earnings are a key lens for a service heavy business. At a P/E of 10.4x, the stock trades well below the Commercial Services industry average of 18.8x and also under the broader peer group at 16.9x. For an investor, that means the market is currently paying fewer dollars for each dollar of Deluxe earnings compared with many similar companies.
The Fair Ratio, which reflects what you might expect for Deluxe given its sector, profitability profile and risk, sits above the current 10.4x P/E. On this framework the shares screen as undervalued on earnings, although any conclusion still depends on your view of how reliable those profits are and how much volatility you are willing to tolerate. Explore the numbers behind Deluxe's P/E valuation.
The Deluxe Narrative: What Would Justify Today's Price?
Narratives take that low P/E for Deluxe and turn it into concrete what ifs about future growth, margins and earnings that would need to play out for the stock to look meaningfully cheaper or richer than today’s price, and they sit on Simply Wall St’s Community page. Instead of one abstract valuation output, Narratives spell out the future those numbers rely on so you can watch how Deluxe’s actual progress lines up with the story.
One of the top community narratives on Deluxe: 29% undervalued
"The current valuation implies the market is still pricing Deluxe largely as a mature print and checks company rather than as a payments and data platform..."
Discover why this Narrative puts Deluxe at 29% undervalued.
Before you make a move on Deluxe, there is one more factor to weigh
Valuation only tells part of the story for Deluxe, and our research has also surfaced risk checks that could change how you view the trade off. Take a closer look at 1 major warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com