
Hut 8 (HUT) Earnings Optimism Puts Its Valuation Back In Focus
Recent shifts in analyst expectations around Hut 8 (HUT) earnings have put the stock back on watch, as forecasts now indicate a higher probability that the miner could exceed quarterly profit estimates.
Recent price action shows how quickly sentiment on Hut 8 can swing. The 1-day share price return of 3.15% contrasts with a 30-day share price decline of 25.08% and a 90-day slide of 35.85%. At the same time, the year-to-date share price return sits at 35.48% and the 1-year total shareholder return is 33.78%, pointing to longer term gains but fading momentum in recent months as investors reassess risk and reset expectations around the latest earnings narrative.
Scan beyond Hut 8 and size up other high-conviction opportunities in energy intensive compute and digital infrastructure with a curated list of 54 AI infrastructure stocks.
Hut 8 now trades at a steep discount to analyst targets after a sharp pullback, while earnings expectations are turning more optimistic. Is the market’s caution still warranted, or has sentiment swung too far?
Most Popular Narrative: 55% Undervalued
At a last close of $69.46 against a narrative fair value of $154.04, Hut 8 is framed as heavily discounted, with that gap hinging on whether long-term AI infrastructure contracts and the financing that supports them ultimately hold together.
The main thing that has to go right is Hut 8 continuing to secure and energize large power sites under supportive regulatory frameworks so that its 8.7 GW development pipeline can convert into contracted, investment-grade AI campuses.
The Power First development system, supported by an 8.7 gigawatt pipeline and the ability to originate multiple sites under diligence or exclusivity, is now backed by approximately US$7.5b of fully amortizing investment grade project notes and an undrawn US$1.07b revolver.
See why 84 investors see Hut 8 as 55% undervalued.
Result: Fair Value of $154.04 (UNDERVALUED)
Still, Hut 8’s story can crack if Bitcoin driven losses persist, or if project delays, higher costs, and roughly US$7.6b of debt keep weighing on margins.
Find out about the key risks to this Hut 8 narrative.
Another View: Hut 8 Looks Expensive On Sales
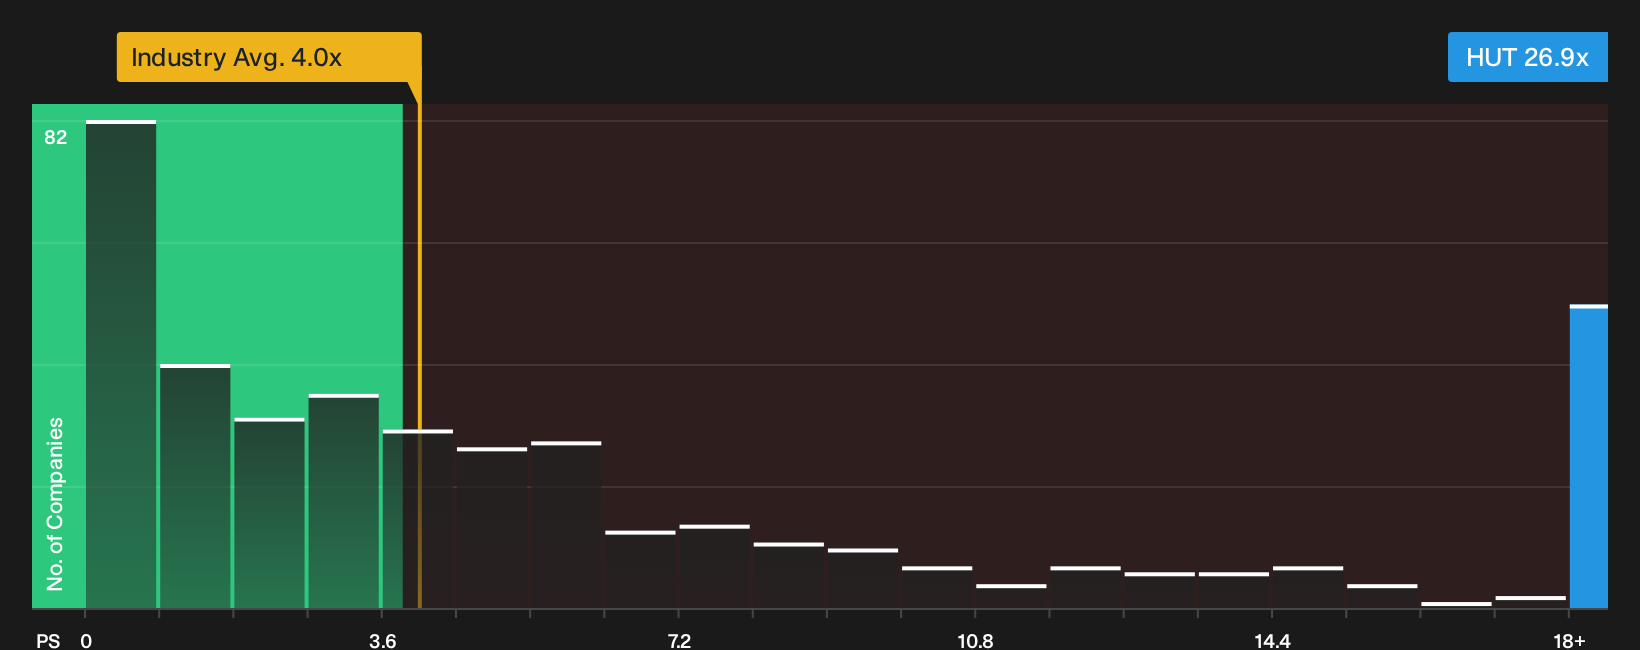
The fair value story for Hut 8 leans on long term contracts and earnings potential. Look at today's P/S ratio though and you get a very different picture. The stock trades at 26.9x sales, compared with about 4x for the wider US software group and roughly 1.6x for peers, while the fair ratio is 12.5x. That gap suggests investors are already paying up heavily for future growth that has yet to show up in profits, so the key question is how much execution risk you are comfortable owning at this price.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If sentiment around Hut 8 feels finely balanced between promise and pressure, your next move is to weigh the full data yourself and move quickly while the picture is still evolving. Start with the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Hut 8?
If Hut 8 has sharpened your focus on risk, reward, and timing, use that same mindset to hunt for other potential opportunities before the market gets there first.
- Target potential mispricings by reviewing a curated 26 high quality undervalued stocks that already combines quality fundamentals with discounted market prices.
- Prioritise resilience by scanning a list of solid balance sheet and fundamentals (24 results) so you can focus on businesses with stronger financial footing.
- Get ahead of the crowd by checking a 19 high quality undiscovered gems that highlights lesser known companies with solid underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com