
Should CEO Transition Require Action From Harmony Biosciences (HRMY) Investors?
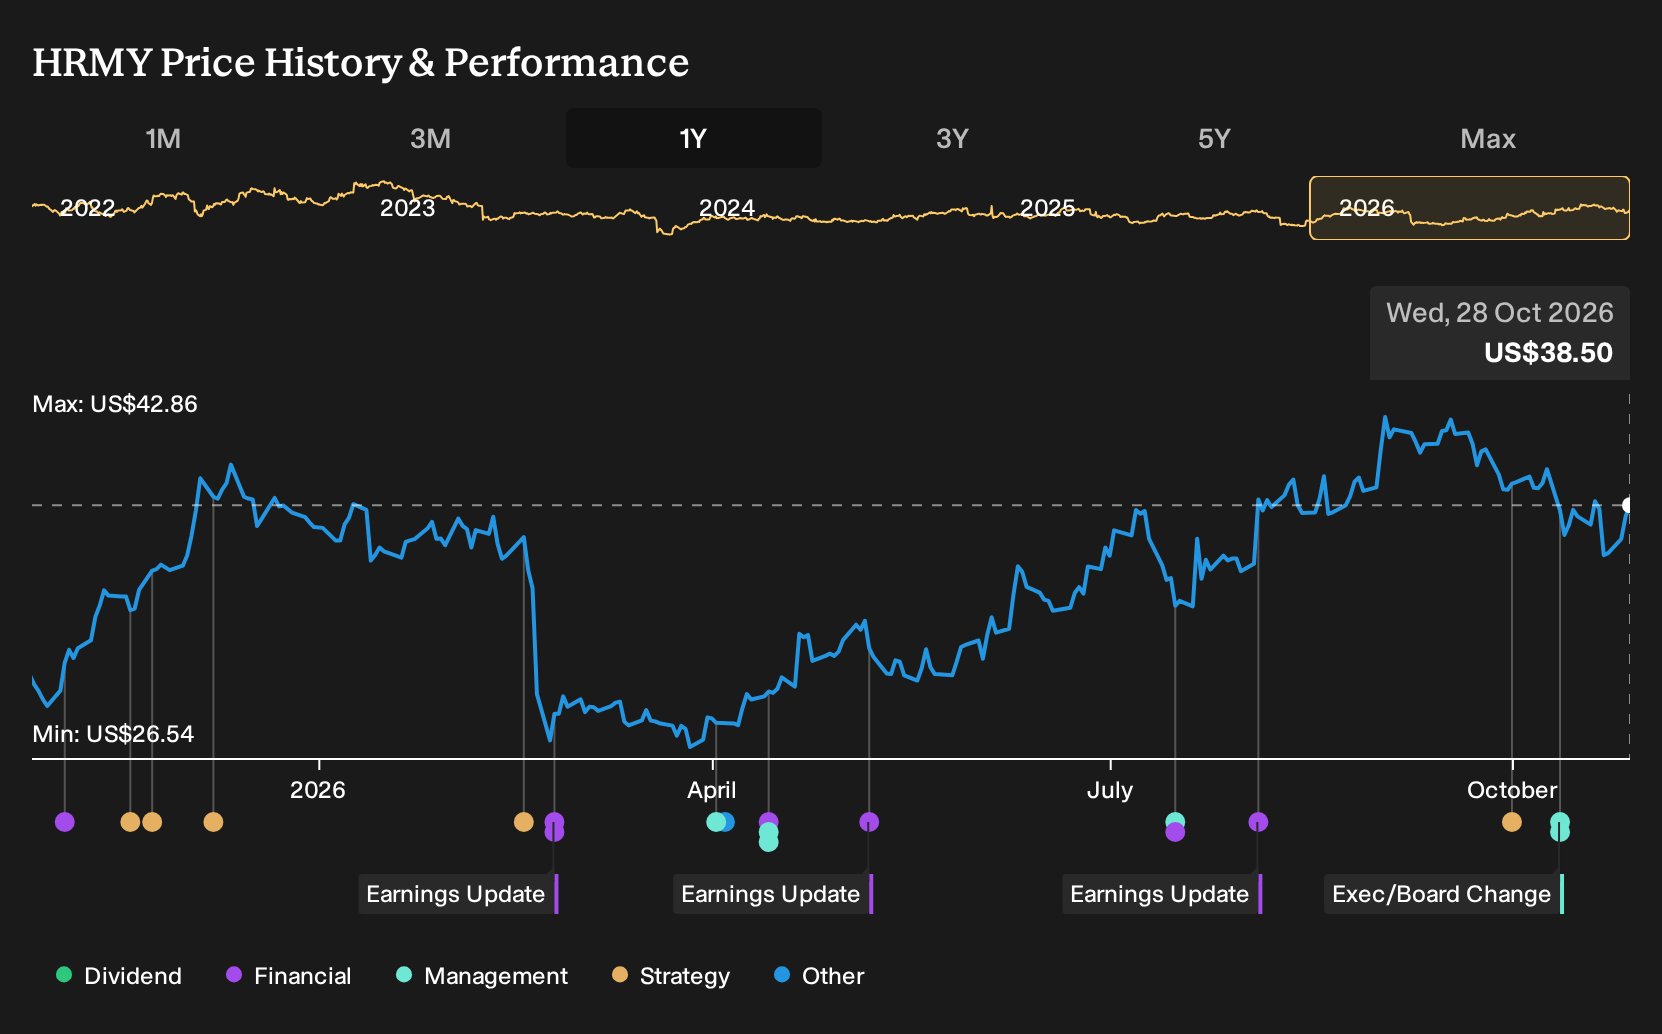
- Harmony Biosciences Holdings is working through a CEO transition that has already taken place, with the leadership change drawing fresh attention to execution on its narcolepsy portfolio and broader rare CNS pipeline.
- The leadership shift highlights how dependent Harmony Biosciences remains on clear execution around WAKIX and upcoming pitolisant and orexin 2 agonist programs to sustain its rare disease focus.
- We will look at how Harmony Biosciences' investment narrative is tested by the CEO transition and related questions about future execution.
Compare how Harmony Biosciences Holdings stacks up against other rare disease and CNS-focused players by scanning our hand picked 19 high quality undiscovered gems.
Harmony Biosciences Holdings Investment Narrative Recap
For Harmony Biosciences Holdings, the core belief for shareholders is that WAKIX can keep funding a broader rare CNS portfolio while new products like pitolisant GR, additional pitolisant indications and the orexin 2 agonist BP-205 move toward the market. The CEO transition has unsettled some holders, but the immediate operating priorities around WAKIX demand, pricing and access do not appear structurally changed by the leadership shift alone.
The key near term operational catalyst remains evidence that late stage programs, including the five Phase III pitolisant trials, stay on track without fresh delays. The biggest current risk is still concentration in WAKIX, alongside pressure from rising cost of product sold and royalties, which could squeeze margins if spending climbs faster than sales during the leadership handover.
Recent focus on the CEO handover ties directly into how Harmony Biosciences executes around its orexin 2 agonist BP1.15205, positioned as a future narcolepsy and CNS asset. Earlier data in 72 healthy volunteers showed favorable pharmacokinetics, safety and once daily dosing potential, so investor attention now sits on whether development milestones are hit cleanly under the new leadership.
This orexin 2 program matters because it offers a path to reduce dependence on WAKIX over time and broaden Harmony Biosciences Holdings beyond a single commercial product. Any disruption to development timelines, regulatory interactions or trial resourcing during the CEO transition would increase execution risk, while steady progress would support the existing rare disease and sleep disorder thesis.
Harmony Biosciences Holdings' current analyst narrative points to about US$1.4b in revenue and US$363.2 million in earnings by 2029, based on a projected 12.5% yearly revenue growth rate and a move in earnings from US$181.3 million today. This implies roughly a 2x increase in profit against that starting point.
Uncover how Harmony Biosciences Holdings' fair value indicates a 24% potential upside to its current price before other investors close that gap.
Exploring Other Perspectives
One alternate view on Harmony Biosciences centers on much slower WAKIX momentum instead of pipeline execution. The lowest analysts were already penciling in revenue of about US$1.0b and earnings of roughly US$233.1 million by 2029, far below consensus. With the CEO transition now in focus, those pre news assumptions may shift further.
Explore 3 other Harmony Biosciences Holdings fair value estimates, including one that suggests it could be worth just $47.64!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Harmony Biosciences Holdings research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Harmony Biosciences Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Harmony Biosciences Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Harmony Biosciences Holdings?
If you want to broaden your watchlist beyond Harmony Biosciences Holdings, the Simply Wall St Screener can help you quickly sort through listed companies by quality, valuation and risk profile so you are not relying on a single story.
- For investors who want potential value combined with resilient fundamentals, start with a 26 high quality undervalued stocks that already clear basic quality and balance sheet checks.
- If capital preservation sits high on your priority list, narrow your search to a 32 resilient stocks with low risk scores that may better match a more cautious temperament.
- When you prefer robust finances over hype, focus your attention on a list of solid balance sheet and fundamentals (24 results) that can help you filter for companies with stronger financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com