
Formula One Group (FWON.K) Looks Pricey Following A 102.6x P E Valuation Test
Formula One Group (FWON.K) has drawn fresh attention after recent trading left the share price at $90.86, with the stock down 4.2% over the past month and 9.1% in the past 3 months.
Over a longer window, Formula One Group shows a mixed picture, with the share price down in recent months, while the 3 year and 5 year total shareholder returns of 40.0% and 68.7% indicate momentum that has been built over time.
Contrast Formula One Group's recent pullback with a curated list of other media and entertainment businesses showing stronger momentum in our 19 high quality undiscovered gems
After a pullback that leaves Formula One Group at $90.86 despite solid multi year total returns, the question is whether the current valuation still compensates you for the risks on the track ahead.
Price-to-Earnings of 102.6x: Is it justified?
On simple earnings terms, Formula One Group looks expensive. The stock trades on a P/E of 102.6x, compared with a peer average of 38.5x and a US Entertainment industry average of 21.1x, even after the recent pullback to $90.86.
The P/E ratio compares the current share price with annual earnings per share. For a media and motorsports rights business like Formula One Group, this metric reflects how much investors are paying today for each dollar of current profitability, in a model where a lot of value is tied to long term contracts, media rights and event economics.
A triple digit P/E suggests the market is assigning a high value to future earnings growth rather than current profit. That sits next to several data points that point in a different direction: earnings declined 20.1% over the past year, net profit margins compressed from 7.5% to 5.5%, return on equity is 2.6%, and interest payments are not well covered by earnings. Against that backdrop, an estimated fair P/E of 22.9x signals a level the valuation could gravitate toward if expectations reset closer to the regression based fair ratio.
The comparison with peers reinforces that the valuation gap is wide. Formula One Group trades at 102.6x earnings while the broader US Entertainment group sits at 21.1x, and the stock is also described as expensive against the peer average of 38.5x. Revenue is forecast to grow 9.1% per year and earnings 18% per year, which analysts expect to be slower than the 20% threshold often labelled as significant growth, so the current multiple reflects a premium for growth that is not described as exceptional in the data provided.
Explore the SWS fair ratio for Formula One Group.
Result: Price-to-earnings of 102.6x (OVERVALUED)
Still, Formula One Group faces real pressure if earnings fall further or interest costs stay heavy, because a 102.6x P/E leaves little margin for disappointment.
Find out about the key risks to this Formula One Group narrative.
Another view using cash flows
The earnings multiple paints Formula One Group as expensive, yet the SWS DCF model comes out with a value of $89.72 per share against the current $90.86. That points to a stock trading only slightly above its future cash flow estimate, so the question is whether the real stretch lies in sentiment rather than fundamentals.
Look into how the SWS DCF model arrives at its fair value.
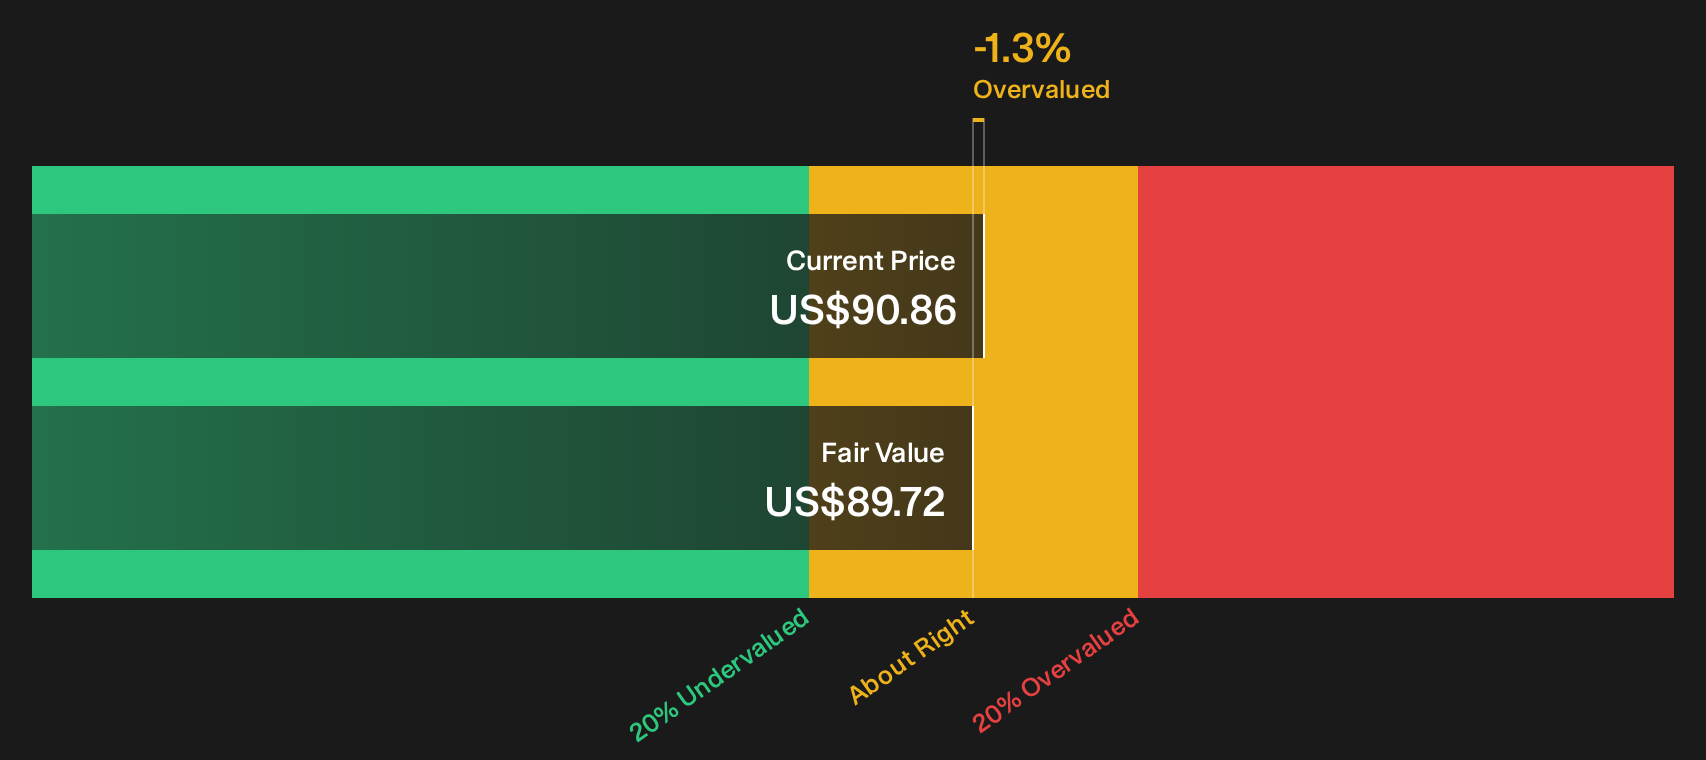
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Formula One Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 26 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With sentiment on Formula One Group split between premium pricing and real risks, the quickest way to cut through the noise is to examine the underlying metrics yourself and judge whether the trade off feels fair for your goals. To weigh both sides of the story in one place, start with the 3 key rewards and 2 important warning signs.
Looking for more Formula One Group style investment ideas?
If Formula One Group has you rethinking valuations and risk, do not stop here. Broaden your watchlist with targeted ideas sourced directly from the Simply Wall St screener.
- Target resilience by focusing on businesses that combine financial strength with low risk profiles using our 32 resilient stocks with low risk scores.
- Hunt for quality at a reasonable price by scanning companies that pair solid fundamentals with attractive pricing through the 26 high quality undervalued stocks.
- Anchor your portfolio with income focused opportunities by reviewing a curated set of higher yielding payers in the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com