
Worthington Steel (WS) Upgrade Puts Kloeckner Synergies And Valuation In Focus
Worthington Steel (WS) is back on investor radars after an analyst upgrade related to its earnings outlook and its progress integrating the recently acquired Kloeckner, where management has outlined meaningful synergy goals through fiscal 2028.
The latest move fits a broader upswing. Worthington Steel’s share price is up 20.5% over the past 90 days and 14.9% over the last month. The 1 year total shareholder return of 35.5% points to momentum building around the earnings upgrade and Kloeckner integration story.
Scan how Worthington Steel’s earnings upgrade and the Kloeckner integration story compare with other potential movers in our curated list of 26 high quality undervalued stocks.
After a 35.5% one year return and a fresh earnings upgrade, Worthington Steel has already rewarded early believers. The real question now is whether that Kloeckner fueled rerating has run its course or still leaves room on the table.
Most Popular Narrative: 11% Overvalued
Worthington Steel closed at $42.35, while the most followed valuation story anchors fair value at $38. This frames the recent rally against a slightly richer starting point for new buyers.
Worthington Steel is poised to benefit from increased demand in the electrical steel market due to AI initiatives, more data centers, and an anticipated annual power demand growth of more than 6% over the next 15 years, which is expected to lead to higher revenues.
Strategic investments and acquisitions, such as the expansion of electrical steel capabilities in Canada and Mexico and the expected closing on a 52% stake in the European company Sitem, are described as opportunities to enhance market share and drive revenue growth.
See why 5 investors see Worthington Steel as 11% overvalued.
Result: Fair Value of $38 (OVERVALUED)
Still, the narrative can unwind if shipment softness in automotive or construction persists, and if weaker heavy truck and agriculture demand keeps pressure on volumes and earnings.
Find out about the key risks to this Worthington Steel narrative.
Another View: Worthington Steel Looks Cheap On Sales
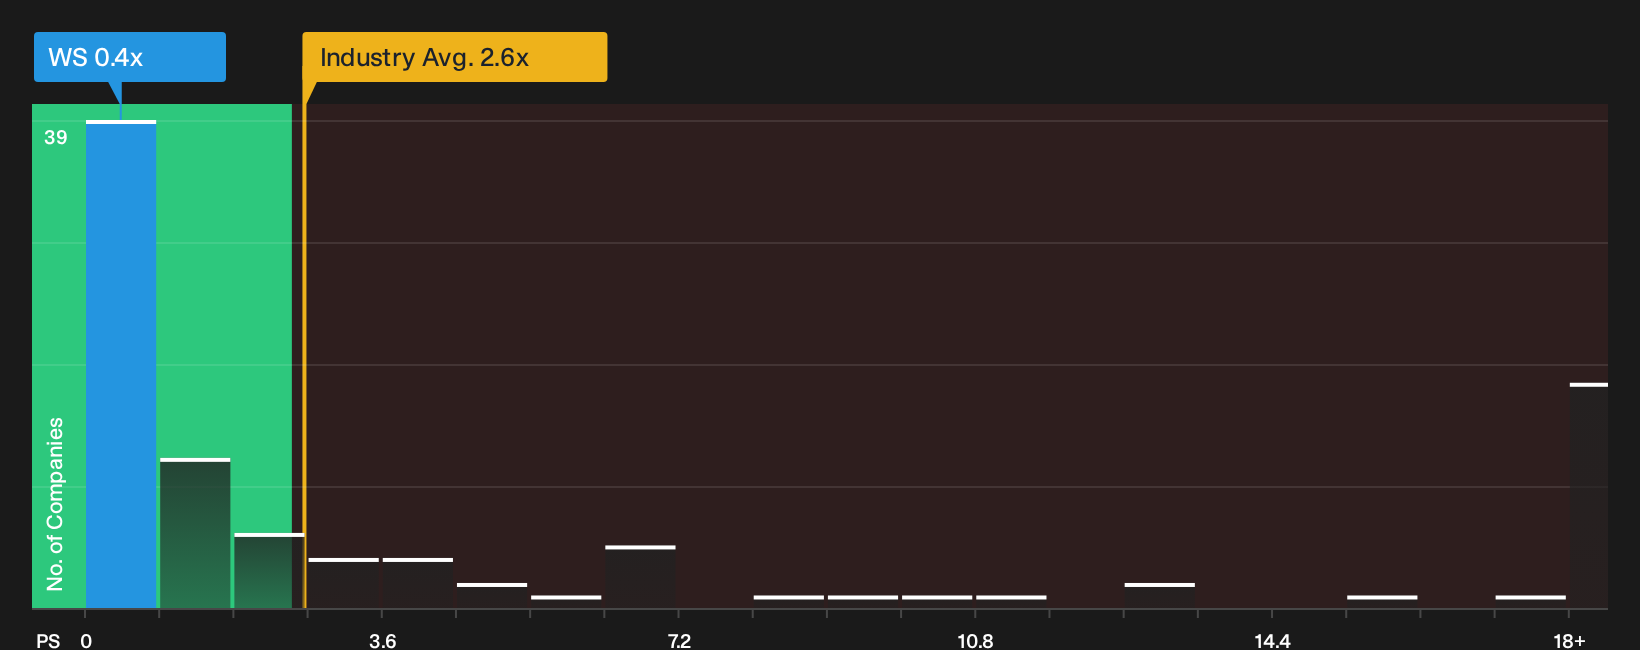
The first narrative paints Worthington Steel as 11% overvalued on a fair value of $38. Yet on simple sales math, the stock tells a different story. WS trades on a P/S of 0.4x, while peers sit at 1.6x and the fair ratio is also 1.6x.
That gap suggests the market is pricing in much more risk for Worthington Steel than for the wider Metals and Mining group, even though revenue is forecast to grow 32.2% per year. The question for you is whether that discount reflects genuine concern or leaves a potential mispricing to research further.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Worthington Steel is split enough to justify a closer look at both the bullish and cautious angles before you move on. If you want the full picture on what has investors concerned and what has them optimistic, start with these 2 key rewards and 4 important warning signs.
Looking For More Ideas Beyond Worthington Steel?
If you stop with Worthington Steel, you may overlook other setups that fit your style, risk limits, and return goals across different parts of the market.
- Target income first and let price follow by reviewing companies in our 6 dividend fortresses that focus on higher yields with solid underlying businesses.
- Spot potential mispricings early by scanning the 19 high quality undiscovered gems that combine quality fundamentals with lighter market attention.
- Dial back portfolio risk while staying invested by using the 32 resilient stocks with low risk scores to focus on businesses with more resilient profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com