
Is Oceaneering International (OII) Undervalued Following Mixed Q3 2026 Earnings?
Oceaneering International earnings spark fresh look at the stock
Oceaneering International (OII) just posted third quarter 2026 earnings, reporting higher sales but lower net income and diluted EPS compared with a year earlier. These results give investors fresh numbers to reassess the stock.
At a share price of US$41.61, Oceaneering International has seen strong momentum this year, with a year-to-date share price return of 67.44% and a 1-year total shareholder return of 80.68%. This comes even after a 90-day share price decline of 14.70%, which suggests recent earnings have prompted investors to reassess both growth potential and risk.
Scan beyond Oceaneering International and compare its earnings-driven moves with 26 high quality undervalued stocks, which pair solid cash flows with sturdier balance sheets.
Sales are higher, profits are softer, and the Oceaneering International share price has already run hard this year. Does that recent pullback now tip the risk reward in favour of new buyers, or not?
Most Popular Narrative: 5% Undervalued
On the simplest check, the prevailing fair value narrative sits at $44 per share, a touch above Oceaneering International's last close of $41.61, which suggests investors are paying slightly less than that assessment for every share.
The ongoing global energy transition and intensifying decarbonization efforts continue to limit new offshore oil & gas developments, which threatens Oceaneering's long-term project backlog and could ultimately reduce future revenue growth as the addressable market gradually contracts.
There is increasing investor and regulatory pressure to reallocate capital away from traditional oilfield service providers, this trend is likely to hinder capital flows to Oceaneering's core business lines, potentially compressing growth prospects, restraining order activity, and constraining revenue and profit expansion.
See why 12 investors see Oceaneering International as 5% undervalued.
Result: Fair Value of $44 (UNDERVALUED)
Still, a faster build out of Aerospace and Defense Technologies, or stronger recurring decommissioning work in Europe, could blunt offshore weakness and challenge that cautious fair value story.
Find out about the key risks to this Oceaneering International narrative.
Another view on Oceaneering International’s valuation
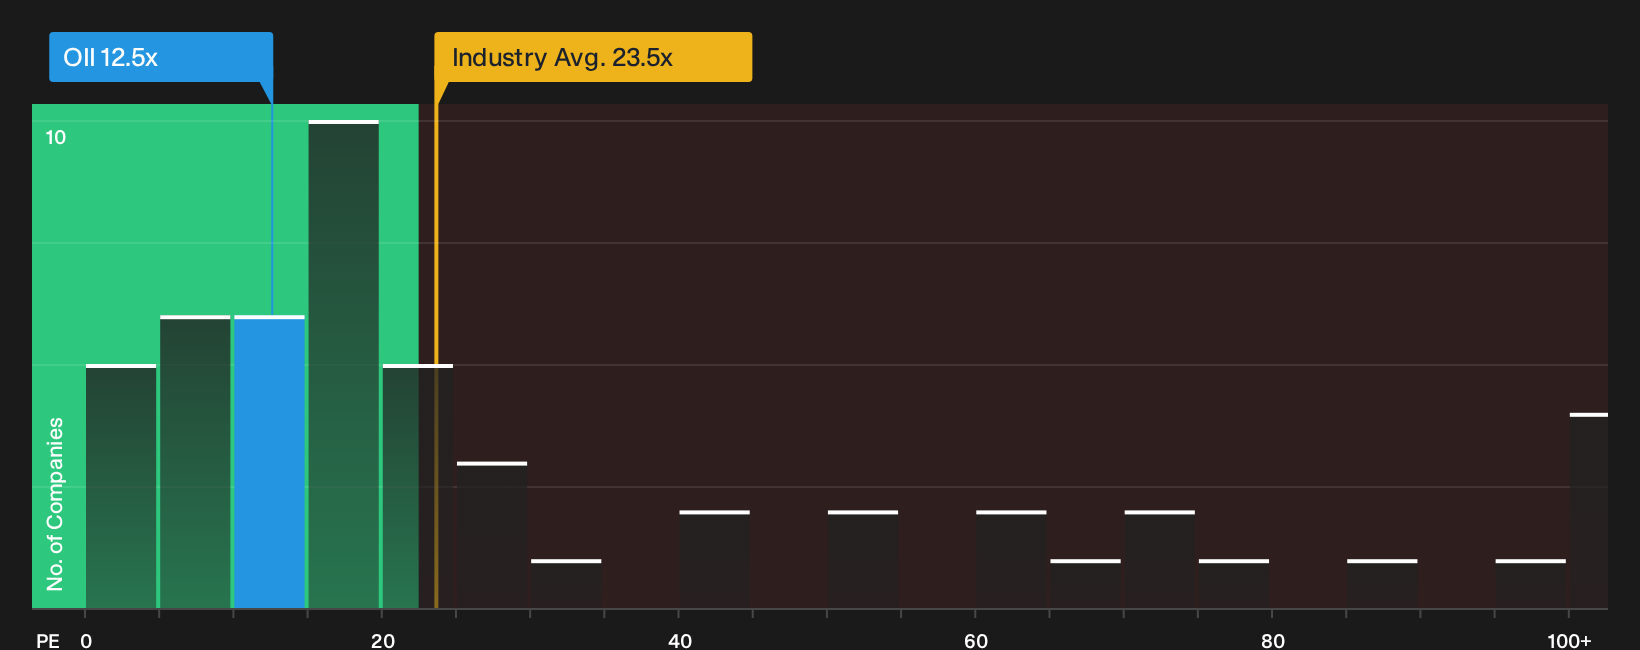
Our fair value work pegs Oceaneering International at roughly 5.9x on a fair ratio P/E, while the market is paying about 12.5x today. That is roughly half the multiple implied by this model, which points to meaningful valuation risk if sentiment cools.
The same P/E sits below the US Energy Services peer average of 23.5x, so relative pricing looks restrained even if the fair ratio signals potential compression. Which reference point do you treat as the anchor for your own thesis on OII?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Oceaneering International so far, and the window to interpret them is open right now. Weigh the potential benefits and the red flags for yourself by checking the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Oceaneering International?
If Oceaneering International has sharpened your focus on valuation and risk, you can broaden your watchlist with ideas filtered for quality, resilience, and income using the Simply Wall St Screener.
- Target potential upside by zeroing in on companies screened as 19 high quality undiscovered gems that pair stronger fundamentals with under-the-radar profiles.
- Dial back volatility by focusing on 32 resilient stocks with low risk scores that score well on financial stability and risk metrics.
- Build a steadier income stream by reviewing 6 dividend fortresses that combine higher yields with more robust fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com