
Aurora Innovation Stock Gets 500 Truck Deal And FMCSA Exemption
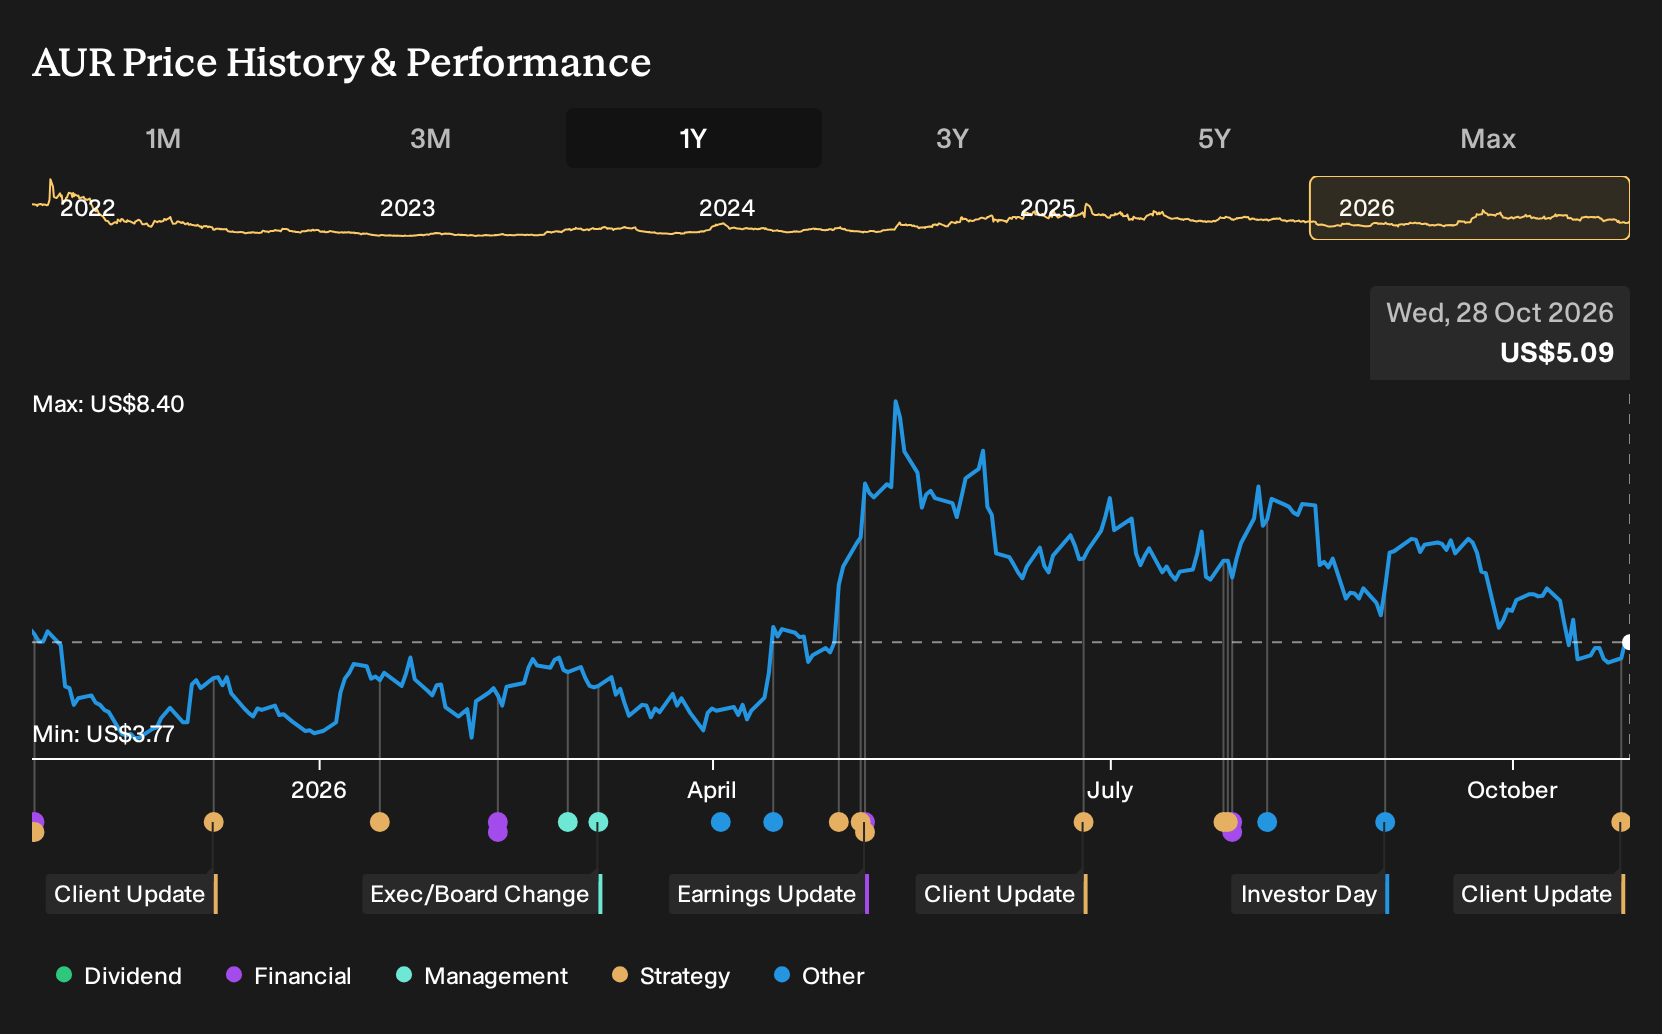
- Aurora Innovation reported third quarter 2026 sales of US$3 million and a net loss of US$234 million, reaffirming 2026 revenue guidance of about US$9 million, while signing a memorandum of understanding for up to 500 Aurora Driver powered trucks with Charger Logistics for 2027 to 2028 delivery.
- The Charger Logistics MOU, paired with a five year federal exemption allowing cab mounted warning beacons on driverless trucks, gives Aurora Innovation clearer commercial and regulatory footing for its Driver as a Service model despite the current scale of losses.
- We will now look at how Aurora Innovation's investment narrative could be influenced by the Charger Logistics truck deployment plan.
Scan beyond Aurora Innovation to compare it with hand picked autonomous and AI freight opportunities, starting with the 54 AI infrastructure stocks in this corner of the market.
Aurora Innovation Investment Narrative Recap
To own Aurora Innovation, an investor needs to believe that a small current revenue base can eventually support a much larger autonomous freight network. The story turns on whether the company can turn early commercial miles and pilot customers into recurring Driver as a Service usage at meaningful scale. The reaffirmed 2026 revenue guidance of about US$9 million keeps that thesis intact but does not change it.
The near term catalyst remains proof that paying deployments can ramp without an equally sharp rise in cash burn. Third quarter sales of US$3 million sit against a quarterly net loss of US$234 million, so funding and dilution risk stay front and center for now.
The Charger Logistics MOU for up to 500 Aurora Driver powered trucks is the clearest recent signal tied to that catalyst. It links a specific fleet plan in 2027 to 2028 with Aurora Innovation's Driver as a Service model and provides some line of sight on how customers might use the platform across high volume freight corridors.
Because the agreement is non binding and deliveries sit several years out, it does not remove execution risk. It does, however, frame what investors can watch, such as conversion of the MOU into firm orders, timing of truck production with OEM partners, and whether similar DaaS commitments emerge that justify the current spend profile.
Aurora Innovation's analyst narrative points to revenues of US$1.4b and earnings of US$158.3 million by 2029, implying very large yearly revenue growth of about 546.4% and an earnings swing of roughly US$1.06b from current earnings of a US$900.0 million loss today.
Uncover why Aurora Innovation's fair value indicates a 137% potential upside to its current price that may not be available for much longer.
Exploring Other Perspectives
You can also weigh a much harsher cash burn risk. The lowest analysts were working off a view that Aurora Innovation might only reach about US$722 million of revenue and US$88 million of earnings by 2029, with a P/E near 116x. Those harsher assumptions came before this Charger news and may shift as new information lands.
Explore 3 other Aurora Innovation fair value estimates, including one that suggests it could be worth just $12.05!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Aurora Innovation research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Aurora Innovation. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Aurora Innovation's overall financial health at a glance.
Looking for more investment ideas beyond Aurora Innovation?
If you want to stress test your thesis on Aurora Innovation, compare it with other opportunities that share similar qualities using the broader Simply Wall St screener set.
- If you prefer quality at a discount and want to see where fundamentals and valuation line up cleanly across the market, start with the 26 high quality undervalued stocks.
- If capital preservation ranks high on your checklist and you are hunting for companies with stronger financial buffers, scan the list of solid balance sheet and fundamentals (24 results).
- If you are looking for ideas that are off most investors' radar yet still backed by underlying financial strength, take a look at the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com