
Earnings Upgrade Could Be A Game Changer For Harley Davidson Stock (HOG)
- Harley-Davidson appointed two new independent directors, Anthony D. Fassino and Bryan E. Slone, bringing the Board to ten members and adding deep experience in global industrial operations, capital allocation, tax, and regulatory oversight.
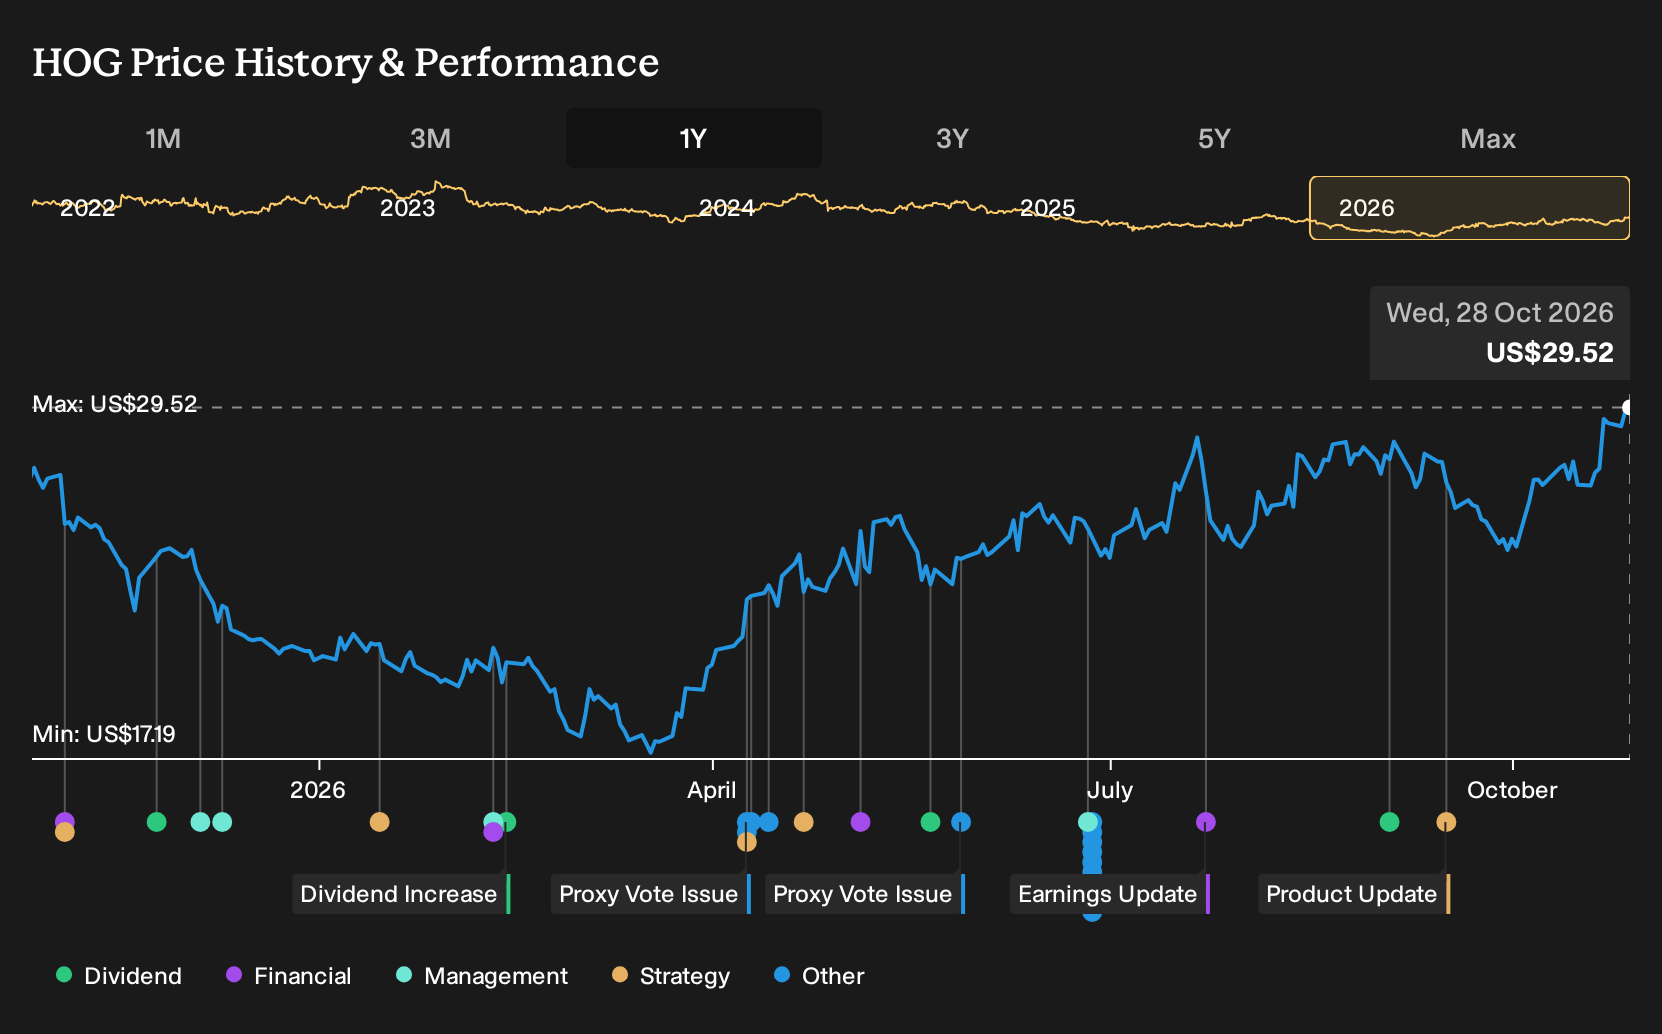
- Fresh board expertise in large scale manufacturing, supply chains, and complex financial governance arrives just as analysts point to a stronger earnings outlook and momentum ahead of the upcoming results announcement.
- Attention now turns to how Harley-Davidson's investment narrative might shift as these board additions intersect with the upgraded earnings outlook.
Harley-Davidson Investment Narrative Recap
To own Harley-Davidson, you need to believe the Back to the Bricks plan can lift earnings power even while tariffs and mix pressure sit on margins. The near-term story still revolves around cost savings, healthier dealers, and growing parts and accessories so that a softer revenue outlook does not translate straight into weaker cash generation.
The biggest swing factor over the next few quarters remains execution on margins while analysts expect a 20.2% revenue decline this quarter and watch Thursday's earnings print. Tariff costs of US$75 million to US$90 million versus 2024 and the tilt toward more affordable bikes remain the primary operational risk.
Among the recent developments, the Zacks Rank #2 upgrade for Harley-Davidson, backed by a 30.3% rise in consensus earnings estimates over three months, appears most closely tied to this board refresh. Fresh directors with global industrial and audit experience arrive just as expectations for earnings quality and capital discipline are being reset.
For you as an investor, the question is straightforward: Do you think this governance mix can help Harley-Davidson manage tariff costs, protect margins on more affordable models, and keep the financial services shift on track while LiveWire restructuring, dealer rebuild efforts, and the cost program all demand tight oversight at the same time?
Harley-Davidson's narrative projects US$4.0b revenue and US$259.6 million earnings by 2029. This assumes revenue declines by 1.9% per year and an earnings increase of about US$57 million from US$202.6 million today.
Uncover how Harley-Davidson's fair value indicates a 5% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
Some of the most optimistic analysts framed Harley-Davidson as a volume rebuild story, not just a margin repair job. Before this board refresh, the bullish camp was already penciling in roughly flat revenue and earnings of about US$344.0 million by 2029, compared with about US$259.6 million in the consensus view. That gap shows how far opinions can stretch, and why you may want to explore several scenarios and decide which assumptions feel realistic as fresh board experience filters into new forecasts.
Explore 3 other Harley-Davidson fair value estimates, including one that suggests as much as 12% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Harley-Davidson research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Harley-Davidson. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Harley-Davidson's overall financial health at a glance.
Looking For More Investment Ideas Beyond Harley-Davidson?
If you want to stress test your Harley-Davidson view against other opportunities, the Simply Wall St Screener can help you quickly line up alternatives with different risk and return profiles.
- For investors who want potential mispricing with quality fundamentals, scan through 26 high quality undervalued stocks that pair robust cash generation with disciplined balance sheets.
- If capital preservation sits high on your checklist, focus on stability using the 32 resilient stocks with low risk scores that aim to keep volatility and risk scores in check.
- When yield is the priority, build an income watchlist from 6 dividend fortresses that combine 5%+ payouts with a focus on resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com