
DocuSign (DOCU) Could Be 37% Overvalued As SAP Deal Fuels Optimism
DocuSign (DOCU) is back in focus after announcing that its Intelligent Agreement Management tools will be embedded directly into SAP Sales Cloud and SAP SuccessFactors as SAP Solution Extensions for sales and HR workflows.
The SAP announcement comes after a strong run in DocuSign’s share price, with a 30-day share price return of 24.81% and a 90-day gain of 53.99%. The 1-year total shareholder return of 21.19% compares with a much longer 3-year total shareholder return of 116.08%, while the 5-year total shareholder return is down 70.48%. This suggests that momentum has picked up recently following a much tougher earlier stretch.
Scan other workflow and AI-driven software stocks showing similar momentum by checking our hand-picked 38 profitable AI stocks that aren't just burning cash.
After a sharp rebound in DocuSign, the market price now sits well above the average analyst target while still at a sizeable discount to one intrinsic value estimate. Where does a reasonable fair value line up between those markers?
Most Popular Narrative: 37% Overvalued
On the latest user valuation, DocuSign screens as overvalued, with a fair value of $60.99 against the current share price of $83.60. That gap raises a simple question for investors: Which set of expectations is doing the heavy lifting?
On a market capitalisation basis, justifying roughly $11.0 billion at a 9% discount needs about $850 million of GAAP net income in 2031, which on 7% revenue growth implies a net margin near 19%.
The buyback lowers that materially, because the same earnings are spread across fewer shares. Once you run the inputs and I can solve the constant, I will pin the exact requirement. My provisional read is that at the current repurchase pace the requirement falls to roughly 15%, which is close to the base case, meaning DocuSign is priced near fair on these assumptions rather than obviously cheap or dear.
See why 6 investors see DocuSign as 37% overvalued.
Result: Fair Value of $60.99 (OVERVALUED)
Still, DocuSign’s story can break if IAM stalls below targets or if share-based compensation keeps pressure on GAAP margins, despite the large repurchase authorization.
Find out about the key risks to this DocuSign narrative.
Another View On DocuSign’s Valuation
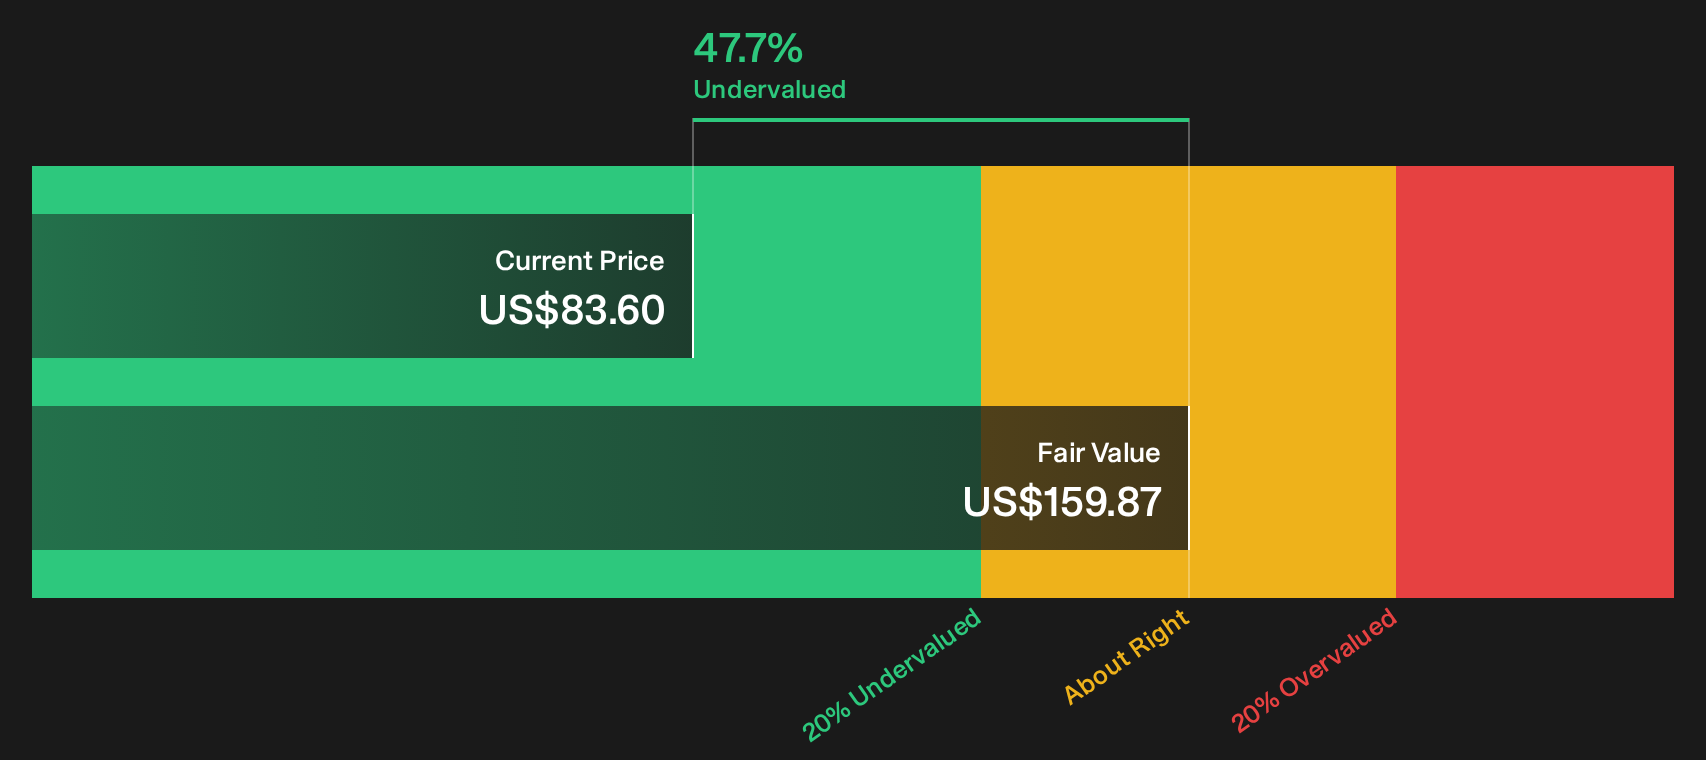
There is a very different signal coming from our DCF model for DocuSign. On that framework, the stock at $83.60 is trading below an estimated future cash flow value of $159.87, which frames the shares as undervalued rather than 37% expensive. Which lens feels more reliable to you for the next few years?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
If this mix of optimism and caution around DocuSign leaves you undecided, consider promptly reviewing the trade offs yourself and reading the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond DocuSign?
Do not stop at DocuSign. Broaden your watchlist with other clear, data backed ideas that could sharpen your next move instead of leaving you reacting late.
- Target stability first by scanning a 32 resilient stocks with low risk scores that aims to keep potential downside in tighter check when market sentiment swings around.
- Hunt for quality on sale with a 26 high quality undervalued stocks that highlights companies pairing solid fundamentals with prices that sit below their assessed worth.
- Seek reliable cash returns through a 6 dividend fortresses focused on businesses offering higher yields that may appeal if regular income matters to you.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com