
Will Managed Storage Launch Change Arrow Electronics Stock Narrative
- Arrow Electronics recently introduced managed storage services for NetApp Keystone, giving channel partners a fully managed Storage as a Service offer with lifecycle management, monitoring, cyber resilience and advisory support.
- The move makes Arrow Electronics the first distributor to package NetApp Keystone with end to end management. This development could influence how enterprise clients source and consume storage infrastructure through the channel.
- We will look at how Arrow Electronics' investment narrative interacts with this new managed Keystone storage layer for partners.
Compare Arrow Electronics' storage push with other enterprise tech distributors by reviewing the curated list of solid balance sheet and fundamentals (24 results) that may be positioned for the same Storage as a Service shift.
Arrow Electronics Investment Narrative Recap
To own Arrow Electronics, you need to be comfortable with a distributor that is leaning harder into higher margin services while still working through contract clean up in the ECS segment. The NetApp Keystone managed storage layer fits that story because it pushes Arrow further into recurring, service heavy offerings. The near term swing factor still looks like how quickly ECS profitability normalizes after prior restructuring charges.
The biggest risk remains that earnings and margins settle closer to management’s more cautious guidance while some models already flag the shares as trading above intrinsic value estimates. If the Keystone managed services ramp is slower than partners expect, that would probably not change the core thesis but could leave short term expectations looking stretched.
The Keystone managed storage launch links directly to one of the key catalysts around Arrow Electronics, which is a greater mix of value added services in ECS. This new offer builds on that direction by adding lifecycle management, monitoring and advisory support that can deepen Arrow’s role inside partner delivered data center and cloud projects.
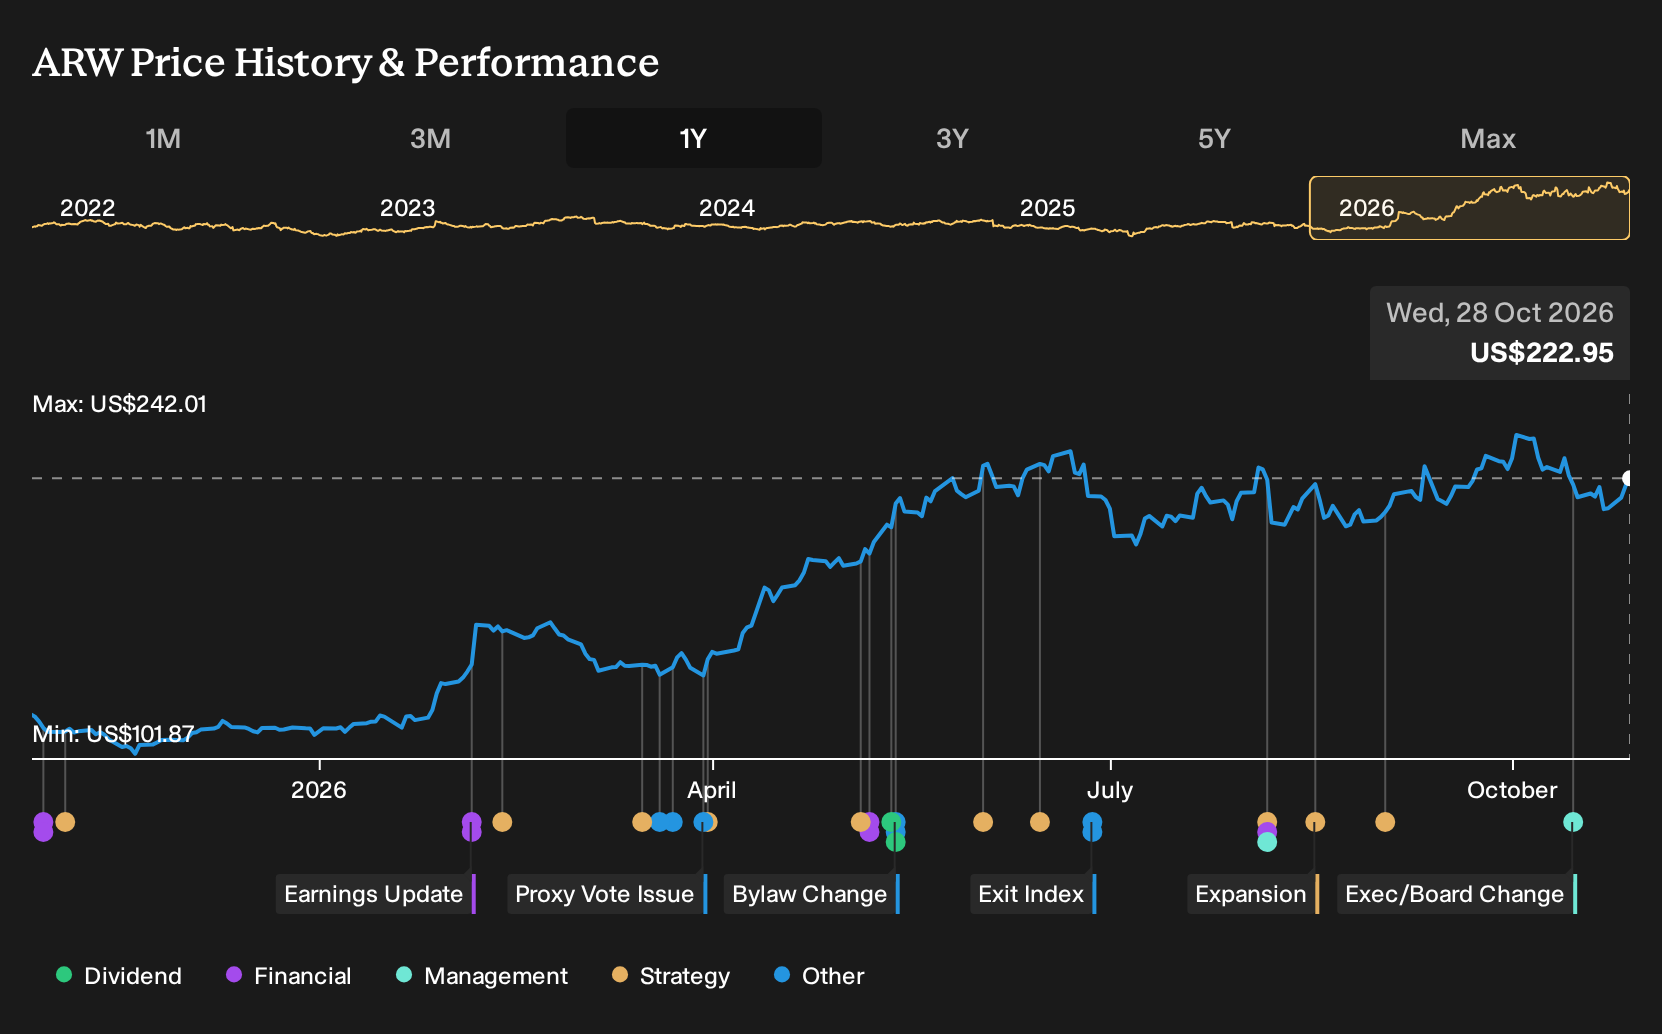
For you as an investor, the question is whether Arrow executes cleanly on this offer while transitioning ECS leadership. Eric Nowak’s planned retirement and Rodney Clark’s expected arrival bring experienced channel and commercial oversight, but any misstep around contract quality, service delivery or partner adoption would feed straight back into the same profitability and valuation risks already flagged by the market.
Arrow Electronics Forecasts Behind the Keystone Storage Push
Arrow Electronics' narrative projects US$49.4b revenue and US$1.6b earnings by 2029. Analysts are baking in 11.2% yearly revenue growth and an earnings increase of roughly US$788m from current earnings of US$811.6m.
Discover why Arrow Electronics' fair value points to a 5% potential upside to its current price before the market adjusts to the narrowing gap.
Exploring Other Perspectives
One optimistic twist in the Arrow Electronics story focuses on margins. The most bullish analysts were already assuming profit margins reach 3.6% and earnings of about US$1.8b by 2029, slightly above the US$1.6b consensus view. Those forecasts came before this Keystone managed storage launch, so you may want to compare how each camp might now revise those assumptions.
Explore 4 other Arrow Electronics fair value estimates, including one that suggests there may be as much as 12% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Arrow Electronics research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Arrow Electronics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Arrow Electronics' overall financial health at a glance.
Looking For More Ideas Beyond Arrow Electronics?
If the Arrow Electronics story has sharpened your thinking about risk, balance sheets and service heavy business models, it can help to line that up against a wider watchlist built from other high quality companies.
- If capital protection sits high on your priority list, start by reviewing a 32 resilient stocks with low risk scores that screens for resilience over excitement.
- For readers hunting for quality at a measured price, use the 26 high quality undervalued stocks to see which businesses currently screen as both financially sound and potentially mispriced.
- If income is your focus, run through the 6 dividend fortresses and compare those cash returns with what you see in Arrow Electronics today.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com