
How Investors Are Reacting To Equinix (EQIX) Raised Guidance
- Equinix reported third quarter 2026 net income of US$489 million and earnings per share from continuing operations above the prior year, raised full year guidance after double digit recurring and interconnection revenue growth, and affirmed a US$5.16 quarterly dividend payable in December.
- The business paired stronger profitability with an omnibus shelf registration covering common equity, preferred stock, multiple debt instruments and units, giving management flexible funding options as it expands capacity for AI and high density workloads.
- This article examines how Equinix's raised full year guidance and pricing strength may reshape the investment narrative built around AI driven demand.
Scan beyond Equinix and see how other data center and AI infrastructure plays are setting up right now with a curated list of 54 AI infrastructure stocks in one place.
Equinix Investment Narrative Recap
To own Equinix, you need to believe that demand for dense, interconnected data center capacity, including AI workloads, can be matched by actual build out and power access. The latest quarter supports that narrative on the operations side, with higher net income, higher EPS from continuing operations and raised full year guidance tied to recurring and interconnection revenue.
The key near term swing factor is execution on the accelerated capacity plan without grid, permitting or cost issues eroding returns. That remains the biggest operational risk. The quarter did not remove those constraints, although the raised outlook and record bookings suggest they have not yet become a binding brake on the business.
The shelf registration filing looks most relevant for investors weighing the new guidance. Management now has broad authority to issue common or preferred equity and multiple layers of debt. This gives Equinix flexibility to fund its multiyear build program and AI focused expansions while it targets low to mid 20% cash on cash returns.
For you, the operational question is how that funding toolkit interacts with risk. Heavy development plans in power constrained markets increase exposure to higher construction and financing costs, along with political and community pushback on large campuses. The shelf does not change those external pressures, but it can affect how quickly Equinix responds to demand spikes and how any future capital raising flows through to per share outcomes.
Equinix's current narrative anchors on analysts forecasting revenue of US$13.5b and earnings of US$2.3b by 2029, assuming a 10.8% yearly revenue growth rate. That outlook implies earnings moving from US$1.5b today to US$2.3b, an increase of about US$0.8b over the period.
Discover how Equinix's fair value indicates a 22% potential upside to its current price, which may not last much longer.
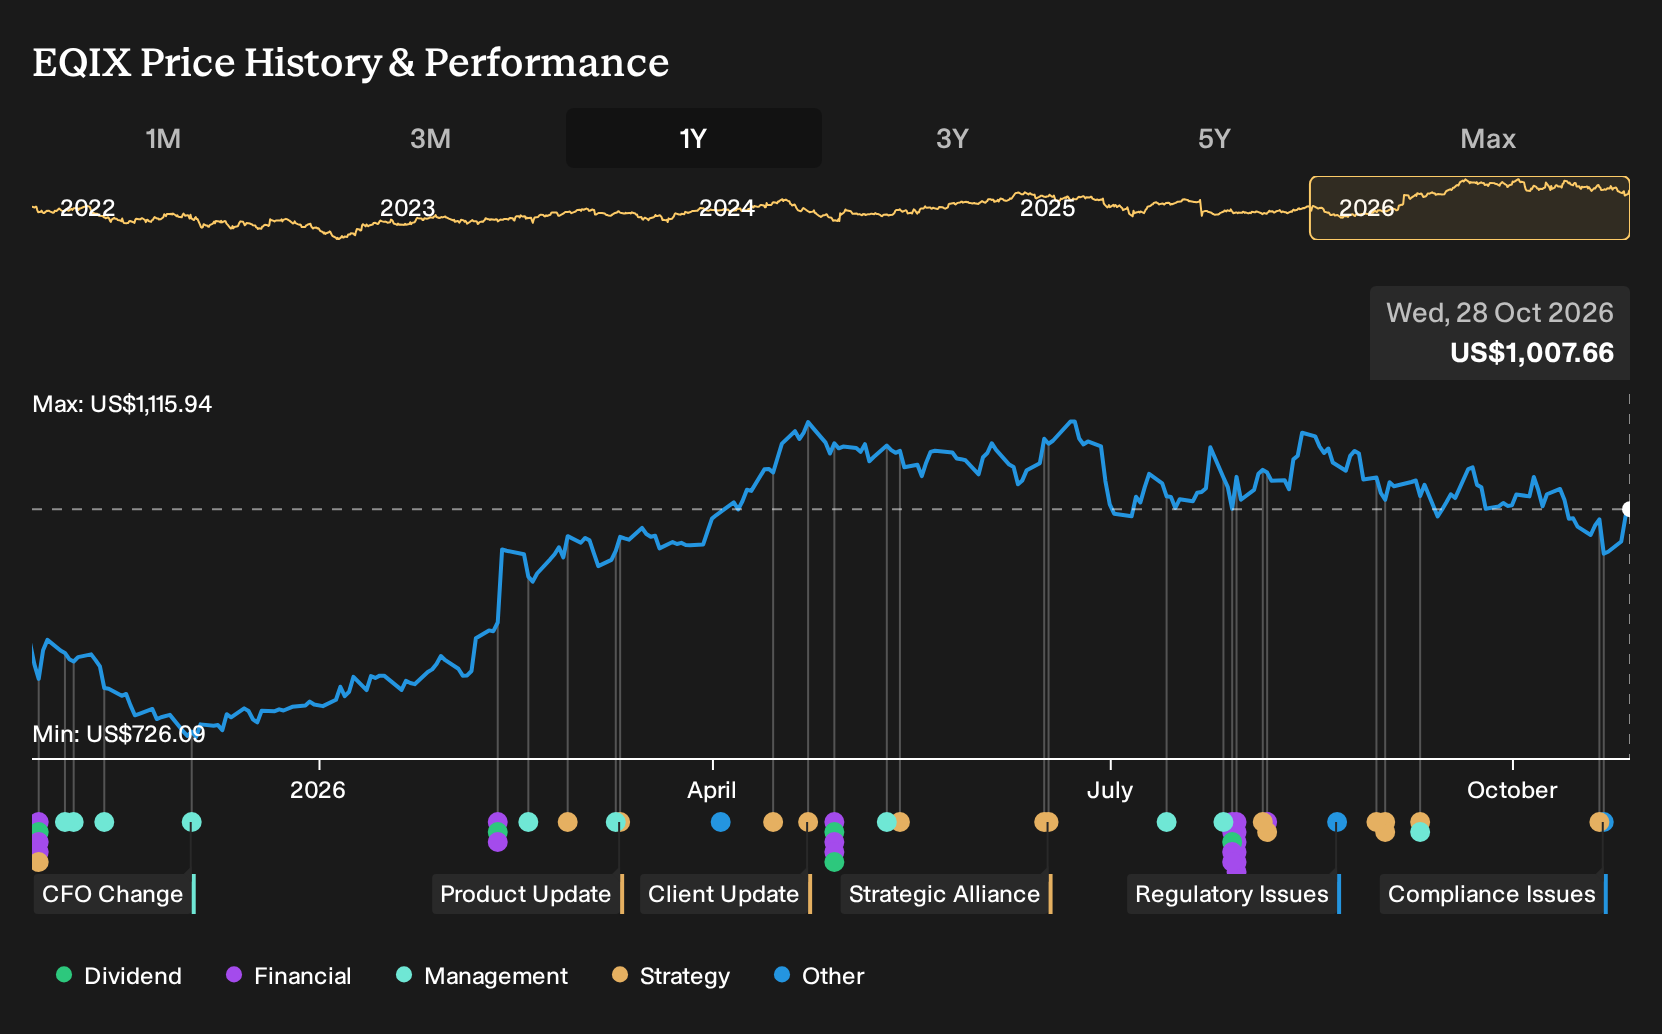
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between about US$1,231 and US$1,629 per share, so you are seeing a wide band of opinion before factoring in Equinix's latest earnings beat, dividend affirmation and shelf registration. When you also consider power grid and permitting risks, you have strong reasons to compare several viewpoints before deciding how Equinix fits your portfolio.
Explore 2 other Equinix fair value estimates, including one that suggests it could be worth just $1231!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Equinix research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Equinix. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Equinix's overall financial health at a glance.
Looking for more Equinix style investment ideas?
If the Equinix story has you thinking about where to look next, it can help to scan a wider field of opportunities that match the kind of risk and quality profile you want.
- Prefer to focus on stability and capital preservation first? Filter for companies with sturdier finances and a history of disciplined funding decisions using a 32 resilient stocks with low risk scores.
- If income is your priority, you can focus on businesses with stronger cash generation backing their payouts with a curated list of 6 dividend fortresses.
- If you want potential mispricing to be the starting point, you can sort through a 19 high quality undiscovered gems that pair solid fundamentals with less market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com