
Should Raised Full Year Guidance Require Action From InvenTrust Properties Stock Investors?
- InvenTrust Properties reported Q3 2026 basic and diluted earnings per share from continuing operations of US$0.25, compared with US$0.08 a year earlier, and lifted full year 2026 net income guidance to a range of US$0.31 to US$0.33 per diluted share, up from the prior range of US$0.12 to US$0.18.
- Management highlighted strong operating execution, with 96.4% leased occupancy, 89% tenant retention, and 3.1% same property NOI growth, which supported higher NAREIT FFO and the raised guidance.
- The following section examines how InvenTrust Properties' investment narrative is affected by the raised full year earnings guidance after solid Q3 execution.
Scan beyond InvenTrust Properties and compare its execution story with other real estate operators by reviewing our curated list of list of solid balance sheet and fundamentals (24 results)
InvenTrust Properties Investment Narrative Recap
To own InvenTrust Properties, you need to believe its Sun Belt focused, essential retail portfolio can keep high occupancy and solid leasing spreads converting into reliable cash flow, even as external growth slows. Q3’s 96.4% leased level, 89% retention, and 3.1% same property NOI growth point to healthy tenant demand supporting that view.
The key near term catalyst is execution on the signed but not open pipeline and rent escalators feeding into FFO, helped by the raised full year earnings and net income guidance. The biggest current risk is funding costs, since interest payments are not well covered by earnings and acquisition yields need to clear that hurdle.
The raised 2026 net income guidance to US$0.31 to US$0.33 per diluted share from US$0.12 to US$0.18 is the announcement that really matters here. It links directly to how well InvenTrust Properties is turning high occupancy, rent bumps, and recent acquisitions into bottom line results after a year when profit margins compressed.
For you as a shareholder, this higher range sharpens the near term earnings bar that management has set for itself. It also puts more focus on whether interest expense, acquisition pricing, and any slower external deal flow chip away at that trajectory, or whether internal growth from the existing centers does most of the heavy lifting.
InvenTrust Properties' current analyst narrative points to revenues of US$406.1 million and earnings of US$10.3 million by 2029. This set up assumes yearly revenue growth of 8.6% and an earnings decline of US$4.9 million from US$15.2 million today.
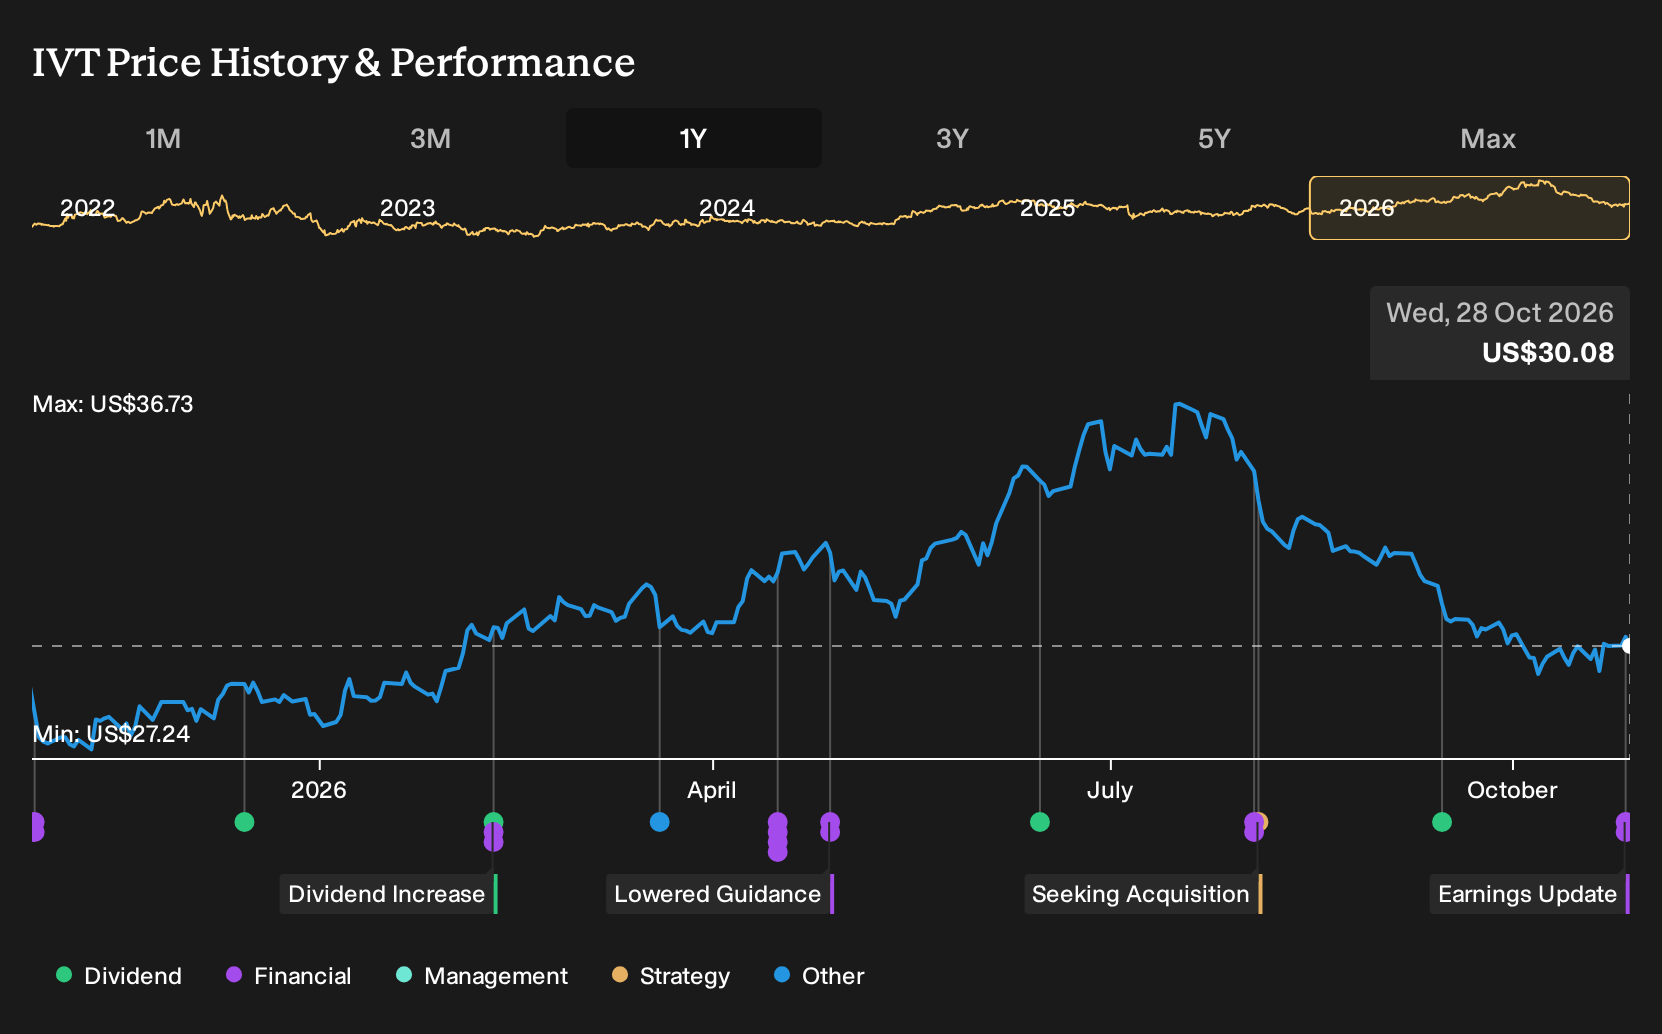
Uncover why InvenTrust Properties' fair value indicates a 22% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The two fair value estimates from the Simply Wall St Community cluster in a tight band between US$35.50 and about US$37.73, yet they still reflect different convictions on where InvenTrust Properties should trade. Set that beside Argus’ US$29 target and you can see how sharply opinions diverge. Use that gap as a prompt to compare multiple views before you commit fresh capital.
Explore another InvenTrust Properties fair value estimate, including one that suggests it could be worth just $35.50.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your InvenTrust Properties research is our analysis highlighting 1 key reward and 4 important warning signs that could impact your investment decision.
- See our latest analysis for InvenTrust Properties. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate InvenTrust Properties' overall financial health at a glance.
Looking For More Ideas Beyond InvenTrust Properties?
If the InvenTrust Properties story has sharpened your thinking, use that momentum to scan for other businesses that match your risk tolerance and income or growth goals using the Simply Wall St Screener.
- For investors who care about resilient balance sheets first and share price second, start with a list of solid balance sheet and fundamentals (24 results) that already clear strict financial health checks.
- If value is your priority and you want candidates where quality and price intersect, focus on companies in the 26 high quality undervalued stocks that still show solid fundamentals.
- Income focused investors can anchor their research on businesses in the 6 dividend fortresses that pair higher yields with a focus on sustainability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com