
How Investors May Respond To National Fuel Gas Stock As Higher Revenue Meets Lower Profit Expectations
- National Fuel Gas recently entered an earnings countdown period where analysts expect quarterly earnings per share to be lower year over year, while revenue for the September 2026 quarter is projected to be higher.
- This mix of softer profitability and firmer sales highlights pressure on costs and margins at National Fuel Gas, even as underlying demand supports top line performance.
- The focus now shifts to how National Fuel Gas's investment narrative holds up against the prospect of lower earnings alongside higher revenue.
Scan how other gas and infrastructure peers are priced for earnings pressure versus demand resilience by reviewing the hand picked list of solid balance sheet and fundamentals (24 results) alongside your view on National Fuel Gas.
National Fuel Gas Investment Narrative Recap
For a shareholder in National Fuel Gas, the core belief is that regulated pipes and utilities, combined with Appalachian gas production, can support a steady earnings base even when quarterly swings show up. The current setup, with revenue expected to be firmer while earnings soften, points to cost pressure and mix effects rather than a broken business model.
The key near term catalyst still lies in execution on projects and the pending Ohio utility expansion, where regulatory outcomes and integration discipline will shape returns. The biggest risk remains that higher debt and equity funding, plus any upstream underperformance, leave National Fuel Gas working harder just to stand still on earnings.
Recent commentary around the upcoming September 2026 quarter matters mainly as a temperature check on how efficiently National Fuel Gas is converting its revenue into profit. Expectations for lower earnings against higher sales put a spotlight on upstream well performance, operating costs and interest expense tied to the more leveraged balance sheet.
No major new announcements have been flagged alongside this earnings setup, so the most relevant reference point is still management’s prior emphasis on regulated expansion and possible separation of Integrated Upstream and Gathering. Investors will need to decide whether the current earnings wobble reflects short term noise around development timing, or a more stubborn drag on the long term story.
National Fuel Gas' current analyst narrative points to about US$3.2b in revenue and US$773.4m in earnings by 2029, built on an assumed 8.8% yearly revenue growth rate and an earnings increase of roughly US$98.1m from US$675.3m today.
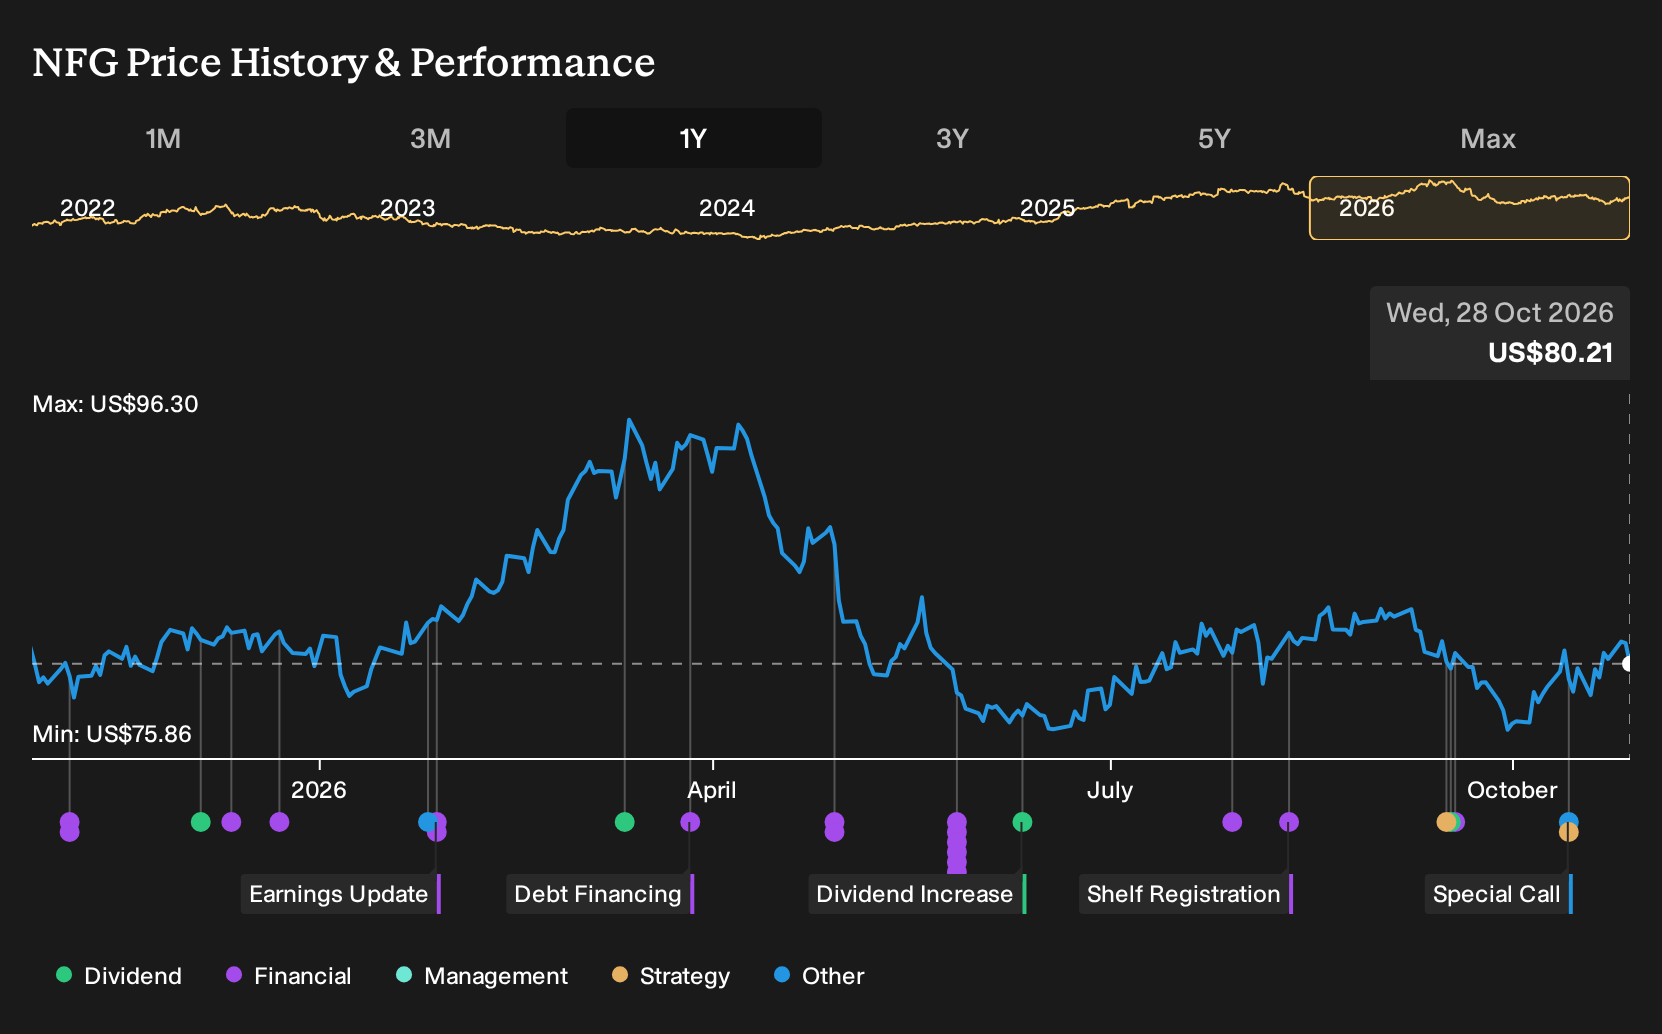
Uncover why National Fuel Gas' fair value points to a 16% potential upside to its current price, which could narrow quickly as expectations reset.
Exploring Other Perspectives
Across three fair value estimates from the Simply Wall St Community, National Fuel Gas is pegged anywhere between US$93 and about US$112.69 per share, which shows how far opinions can stretch. These views sit alongside concerns about upstream execution risk and decarbonization policy, so you are weighing both project delivery and long term demand when comparing perspectives.
Explore 2 other National Fuel Gas fair value estimates, including one that suggests it could be worth just $93.00.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your National Fuel Gas research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for National Fuel Gas. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate National Fuel Gas' overall financial health at a glance.
Looking for more National Fuel Gas sized ideas?
Once you have a view on National Fuel Gas, it can help to cross check that thinking against other opportunities that share similar qualities, or deliberately contrast it with very different profiles, using the Simply Wall St Screener.
- If you want balance sheet resilience to be non negotiable, scan a curated list of solid balance sheet and fundamentals (24 results) and compare how those businesses fund growth and handle volatility.
- For readers who care most about paying a restrained price for quality, line up your options with a focused 26 high quality undervalued stocks that filters for strong fundamentals first.
- Income focused investors can put yield and staying power side by side by reviewing a targeted 6 dividend fortresses built around higher payout levels with an emphasis on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com